State Feasibility Study Data

Wisconsin Feasibility Study Consultants

Wisconsin is one of the nation's manufacturing and agricultural powerhouses, with a roughly $360 billion economy and an SBA market whose loans run well above the national average in size, and a feasibility study in Wisconsin now sits at the center of how lenders move SBA and USDA projects from application to approval. The state added residents again in 2025, with growth concentrated in the Madison region, its Milwaukee industrial market is among the tightest in the Midwest, and its commercial real estate sectors are moving in distinctly different directions. Loan Analytics publishes the lending, demographic, and commercial real estate data behind those numbers, and prepares independent feasibility studies for SBA 7(a), SBA 504, and USDA-financed projects across Wisconsin when a lender requires the full report. This page lays out the current Wisconsin market and explains what a feasibility study consultant actually delivers for a credit file.
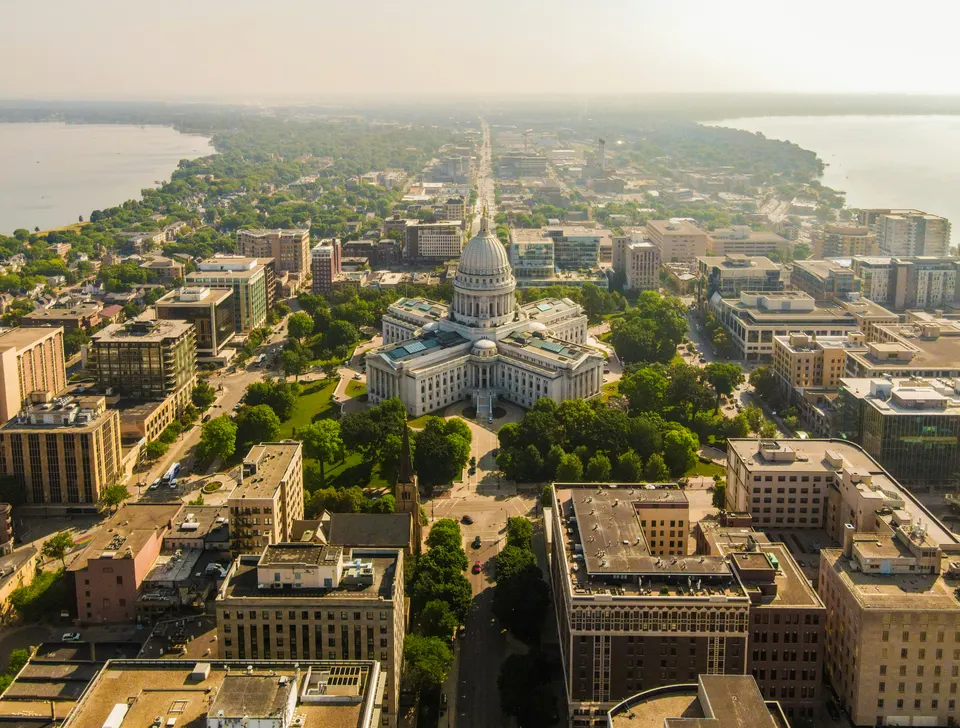
Wisconsin feasibility study consultant

As a feasibility study consultant in Wisconsin, Loan Analytics writes for borrowers and lenders whose credit file needs an independent study, and every engagement opens with the record printed on this page. From FY1991 to FY2026, Wisconsin projects drew 50,315 SBA loans under 7(a) and 504, and 13,157 of them, worth $7.19 billion, were approved from FY2017 to FY2026. In the asset classes Loan Analytics tracks, those years hold 3,860 loans and $2.59 billion. Hotels and motels take the largest dollar total, $429.6 million on 254 loans at a $1.4 million median; full-service restaurants lead by count with 651 loans; and gas stations borrow at a $780,000 median, second only to hotels.

Our study is written for the desk that will read it, and in Wisconsin one 504 lender stands far above the rest: WBD, Inc. approved 1,902 loans for $1.69 billion from FY2017 to FY2026, in a state whose whole SBA 504 book for those years is 2,186 loans. SBA 7(a) volume is spread across U.S. Bank, National Association (868 loans), The Huntington National Bank (605), Summit CU (538) and Byline Bank, whose 443 loans carry $487.1 million. For each of these readers the study defines the trade area, counts the supply competing for its customers, sets out the demand behind the projection, tests coverage under a weaker case, and says where the Wisconsin record is too thin to carry a conclusion.

The floors frame a lender's first questions. Wisconsin's tracked classes show a 10.9% cancellation floor for FY2017 to FY2024 approvals and a 2.8% charge-off floor for loans disbursed FY2017 to FY2021, the lowest in the East North Central division, yet assisted living prints a 5.5% charge-off floor and coffee shops a 15.3% cancellation floor. Each study is built around the risk its class shows in this record, and the scope form directly below is the way to commission one.

Request Scope & Timeline

Image by Nils Huenerfuerst

SBA Lending in Wisconsin: The Current Picture

Wisconsin is a solid SBA market with a notably high average loan size. Recent analysis of SBA data shows Wisconsin businesses receiving roughly $527.0 million Corrected in SBA 7(a) loan approvals across 1,003 Corrected loans in 2025, with an average loan size near $525,000, well above the national average of $443,097. That larger average points to a market weighted toward real-estate-intensive and acquisition transactions, including manufacturing, hospitality, and owner-occupied commercial property, rather than the smaller working-capital loans that dominate denser urban markets. With roughly 149 active SBA lenders competing across the state and the agency administering Wisconsin through its Milwaukee district office, borrowers draw on a deep pool of national institutions, regional banks, and community lenders.

The national program sets the backdrop for every Wisconsin deal. The SBA guaranteed 70,242 7(a) loans worth $31.1 billion in FY2024, then closed FY2025 at 84,840 Corrected combined 7(a) and 504 loans for $45.09 billion Corrected, the most capital the agency has approved in a single year on record. That record volume came alongside materially stricter underwriting standards, which means busier credit desks paired with closer scrutiny of the borrower projections inside each application. A Wisconsin feasibility study consultant earns a place in the file precisely because independent market work gives a credit committee something concrete to test the borrower's assumptions against.

The practical point for a borrower or lender searching for a feasibility study consultant in Wisconsin is that the document is not a box-checking exercise. On startup projects, on change-of-ownership transactions where the buyer has no operating history at the site, and on ground-up construction with no existing revenue to underwrite, the feasibility study is the analysis that lets a credit committee size the deal with confidence. The 504 program in particular, which finances owner-occupied real estate and major fixed assets through a Certified Development Company alongside a conventional lender, routinely involves projects large enough that an independent market study is expected, and Wisconsin's above-average loan sizes mean that threshold is reached often. For projects in the rural and agricultural parts of the state, much of Wisconsin outside the major metros sits in USDA-eligible territory, and USDA Business and Industry lending runs alongside the SBA programs in one of the country's leading agricultural states. A Wisconsin feasibility study company that understands both the SBA standard operating procedures and the local submarket is doing two jobs at once: satisfying a federal documentation requirement and giving the lender a defensible basis for its credit decision.

Where Wisconsin Is Growing: Population and County Demographics

Wisconsin is the twentieth-most-populous state at roughly 5.99 million residents, having added about 15,600 people over the year to July 2025 and roughly 78,000 since 2020, with the gains driven almost entirely by migration. The 2025 increase was smaller than the prior year's, reflecting a sharp national drop in international migration; the number of people moving to Milwaukee and Dane counties from abroad fell by more than half. Notably, domestic migration, people moving to Wisconsin from other states, actually ticked up over the same period. The composition and concentration of that growth is the single most important fact for any demand analysis.

Growth in Wisconsin is heavily concentrated in the Madison region. Dane County, home to the state capital and the University of Wisconsin, leads the state by a wide margin, adding roughly 4,050 residents in the latest year and nearly 29,000 since 2020, a gain of about 5 percent powered by a diverse economy spanning government, education, health care, and a growing biotechnology and technology sector. Milwaukee County, the state's largest at roughly 912,000 residents, has continued a slow decline, losing population since 2020 even as the broader metro holds steady. The Green Bay area's Brown County has grown solidly, adding several thousand residents, and northern tourist counties such as Vilas and Bayfield have seen gains, while many rural counties record only modest change or slight decline. Wisconsin also has a notably aging population, with seniors making up a large and rising share. A project that pencils cleanly in a fast-growing Dane or Brown County submarket can face very different demand in Milwaukee County or a declining rural county, and the Wisconsin label alone tells a lender almost nothing. The work is in the trade area.

Wisconsin Commercial Real Estate: The Five Major Markets

A Wisconsin feasibility study lives or dies on which asset class is in question, because the five major commercial real estate sectors, concentrated in metro Milwaukee and Madison, are moving in distinctly different directions.

Industrial is a genuine strength. The Milwaukee industrial market held a vacancy rate of roughly 4.8 percent in the first quarter of 2026, its lowest level since 2023, with more than a million square feet of positive net absorption, robust leasing in which newly built space accounted for a large share of activity, and a disciplined development pipeline of under two million square feet. The state's manufacturing base, logistics demand, and proximity to Chicago support steady absorption. Multifamily has been a regional outperformer: Midwest markets, including Wisconsin's, posted some of the strongest year-over-year rent growth in the country, supported by chronic housing undersupply, a diminishing construction pipeline, and steady renter demand, with Madison in particular running tight on the strength of its growing, education-anchored economy.

The remaining sectors complete the spread. Office is bifurcated and broadly stabilizing, with well-located and medical office in both Milwaukee and Madison faring far better than older, commodity space, much as in other Midwest markets. Retail has softened modestly, with metro Milwaukee vacancy edging up toward the mid-7 percent range as some space returned to the market, though grocery-anchored and essential-service centers remain resilient. Hospitality spans Milwaukee's business, convention, and lakefront demand, Madison's government and university travel, the powerful seasonal draw of the Wisconsin Dells, Door County, and the Northwoods, and Green Bay's distinctive sports-driven tourism, each with its own distinct demand structure. That divergence between sectors is precisely the question a lender asks a feasibility study to resolve.

Feasibility Studies by Asset Class in Wisconsin

Because the search market for Wisconsin commercial financing breaks down by property type, it is worth being concrete about the asset classes a feasibility study in Wisconsin most often covers, and what each one turns on. A hotel feasibility study in Wisconsin depends on demand segmentation across business, group, and leisure travel in a specific submarket, set against the existing and planned room supply, and it varies enormously between a Milwaukee convention market, a Wisconsin Dells resort destination, and a Door County getaway. A gas station and convenience store feasibility study hinges on traffic counts, fuel volumes, the competitive set within the trade area, and the inside-sales and food-service component that increasingly drives c-store margins. A car wash feasibility study turns on rooftops, daily traffic, and the membership model that now defines express-tunnel economics.

An RV park or campground feasibility study weighs Wisconsin's powerful lake, Northwoods, and Dells tourism against a short, intense season and the conversion of transient demand into longer stays. A multifamily feasibility study tests trade-area household formation and absorption against the apartment pipeline in that specific submarket, a question sharpened by the state's concentrated growth and housing shortage. A self-storage feasibility study measures square feet per capita against current and planned inventory in the immediate radius. An assisted living or senior housing feasibility study models the age-qualified population, penetration rates, and acuity mix, a category with especially deep demand given Wisconsin's aging population. A restaurant or franchise feasibility study weighs daypart demand and local competitive density against the brand's unit economics, and an industrial or warehouse feasibility study tests logistics access, clear-height and power requirements, and the absorption of comparable space nearby, a matter of real consequence in a leading manufacturing state. Each of these is a distinct analysis with its own demand drivers, and a state as varied as Milwaukee, Madison, Green Bay, the Fox Valley, and the rural dairy belt cannot be served by a generic template that simply swaps in the word Wisconsin.

Construction Costs: The Wisconsin Picture

Hard costs feed straight into total project cost, loan sizing, and the debt-service coverage a lender stress-tests, so a current read on construction inflation belongs in every Wisconsin feasibility study, and Wisconsin is one of the few markets with a precise local index. Milwaukee is one of only eight metros tracked directly by the Mortenson Construction Cost Index, and in the first quarter of 2026 Milwaukee costs rose roughly 2.19 percent for the quarter, one of the higher readings among the markets Mortenson tracks and above the national figures of 1.69 percent for the quarter and 6.77 percent year over year. For a project budgeting in southeastern Wisconsin, that is a meaningful signal that local escalation has been running ahead of the national pace.

Several Wisconsin-specific factors sit alongside that index and belong in any serious pro forma. Construction employment in the Milwaukee metro has stabilized at around 37,700 workers, with labor availability improving somewhat as overall demand eases, even as the average project size has been decreasing relative to recent years. At the same time, large-scale data center and manufacturing projects continue to create localized demand pressures for specific trades and materials. A cold-climate building season and the cost of bringing older urban and industrial building stock up to modern standards add further considerations. A market with these dynamics demands a cost basis built from current local conditions and live bids rather than last year's assumptions or a national average, and a feasibility study earns its keep by checking the cost and operating side of the pro forma against the realities of building in the specific Wisconsin submarket.

What a Wisconsin Feasibility Study Consultant Delivers

Read the lending, demographic, and market data together and the assignment becomes concrete. Wisconsin sends a steady stream of larger-than-average projects to credit committees every year, frequently in manufacturing, hospitality, and owner-occupied real estate, a profile that draws careful review under tighter underwriting. Population growth that is real but highly concentrated, with the Madison region and Green Bay growing while Milwaukee County and many rural counties stagnate or decline, means a demand case has to be built at the submarket level rather than the state level. Five commercial real estate sectors pointing in different directions, with industrial exceptionally tight and multifamily outperforming, mean asset selection drives the outcome. And construction costs that have been escalating faster than the national average in the Milwaukee metro mean a budget assembled a year ago is already stale.

A feasibility study consultant brings those threads together into a single third-party document written for the lender's file. The work that distinguishes a credible Wisconsin feasibility study company is independence and evidence: the consultant is a party independent of both borrower and lender, and the conclusions are tied to verifiable trade-area demographics, a documented competitive supply analysis, demand and absorption modeling, financial projections, and sensitivity testing organized around what a credit committee actually reviews. SBA and USDA guidelines call for exactly this kind of independent study on many startup, expansion, and new-construction projects, and the lender typically orders it once the deal is in underwriting.

The state's investment profile sharpens the need for current data. Wisconsin operates a real economy of roughly $360 billion, which grew about 1.5 percent in 2025, and its single largest sector is manufacturing, which generates more than $56 billion in output and anchors the state's identity, from machinery and fabricated metals to food and beverage processing, with major employers spanning heavy equipment, engine, and consumer-products manufacturers. Agriculture is a defining strength as well, with Wisconsin among the nation's leading dairy and cheese producers, complemented by health care, finance and insurance centered in Milwaukee, and a substantial tourism industry. Each of those forces reshapes trade-area demand, labor demand, and absorption in the markets around it, and none of it shows up in a generic template, which is the entire reason a project-specific study exists.

Work With a Wisconsin Feasibility Study Consultant

Loan Analytics prepares independent feasibility studies for SBA 7(a), SBA 504, and USDA-financed projects across Wisconsin, built on the same data published on this page and extended to the subject property. The study arrives as a third-party document, written for the lender's file, covering trade-area demographics, competitive supply, demand and absorption, financial projections, and sensitivity testing. To scope one, use the form below or write to Info@analytics.loan. Include the property type, the county, and the loan program, and we come back with scope and timeline.

Request Scope & Timeline

SBA loan record in Wisconsin, FY2017 to FY2026

SBA 7(a) and 504 loans approved for projects in Wisconsin across the asset classes Loan Analytics tracks, from SBA's own loan-level files.

LoansDollars
Both programs3,860$2.59 billion
SBA 7(a)3,037$1.80 billion
SBA 504823$786.2 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Wisconsin, FY2017 to FY2026, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Cancelled after approval, FY2017 to FY2024 approvals (a floor)10.9%
Charged off to date, FY2017 to FY2021 disbursed loans (a floor)2.8%
Charged off within five years of approval1.5%

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Wisconsin, FY2017 to FY2026, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Both rates are floors: SBA withholds the status of open loans. A rate needs at least 30 loans in its cohort.

SBA loans approved in Wisconsin by fiscal year, in the asset classes with 10 or more loans and approvals in 5 or more fiscal years

0100200300400500FY2017FY2018FY2019FY2020FY2021FY2022FY2023FY2024FY2025FY2026Loans, FY2017: 465Loans, FY2018: 422Loans, FY2019: 380Loans, FY2020: 365Loans, FY2021: 500Loans, FY2022: 396Loans, FY2023: 319Loans, FY2024: 337Loans, FY2025: 357Loans, FY2026: 275
Fiscal yearLoansDollars
FY2017465$244.9 million
FY2018422$228.2 million
FY2019380$184.6 million
FY2020365$228.1 million
FY2021500$396.7 million
FY2022396$294.3 million
FY2023319$220.6 million
FY2024337$253.5 million
FY2025357$283.4 million
FY2026275$201.3 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Wisconsin, FY2017 to FY2026, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Asset classes in Wisconsin, ranked by loans

Asset classLoansDollars
Full-service restaurant651$319.1 million
Limited-service restaurant397$187.3 million
Automotive mechanical repair (car and truck)279$108.1 million
Hotel and motel254$429.6 million
Child care center251$143.7 million
Fitness center246$108.6 million
Gas station and truck stop241$243.6 million
Beauty salon192$41.2 million
Beverage manufacturing (breweries, wineries, distilleries)161$91.7 million
Self storage139$116.8 million
Coffee shop and snack bar134$43.9 million
Dental office126$117.4 million
Assisted living (without nursing care)112$108.2 million
Grocery store97$74.4 million
Veterinary clinic88$65.7 million
Liquor store83$45.3 million
RV park and campground63$53.5 million
Nonresidential lessor (flex, office and retail investor buildings)53$35.3 million
Medical office (physicians)48$30.8 million
Car wash39$44.5 million
Caterers (includes banquet halls with catering staff)38$18.6 million
Rehabilitation and therapy clinic32$7.5 million
Skilled nursing23$25.7 million
Behavioral health and addiction treatment22$11.8 million
Warehouse and distribution21$29.2 million
Data center16$10.3 million
Cold storage10$23.7 million
Continuing care retirement community9$17.4 million
Manufactured housing community (lessors of other real estate)8$5.4 million
Marina7$7.3 million
Life science lab (research and development)5$4.2 million
Multifamily (lessors of residential buildings)4fewer than five loans
School (elementary and secondary, including charter)4fewer than five loans
Diagnostic imaging center3fewer than five loans
Hospital3fewer than five loans
Urgent care and ambulatory surgery1fewer than five loans

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Wisconsin, FY2017 to FY2026, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Most active SBA lenders in Wisconsin's largest classes

Full-service restaurant, SBA 504: lenders by loans approved
LenderLoans
WBD, Inc.115
Racine County Economic Development Corporation12

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Full-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
Byline Bank30
Nicolet National Bank28
Summit CU24
Wisconsin Women's Business Initiative Corporation23
U.S. Bank, National Association22

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Limited-service restaurant, SBA 504: lenders by loans approved
LenderLoans
WBD, Inc.42
Racine County Economic Development Corporation12

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Limited-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
Bank Five Nine24
The Huntington National Bank21
Bank First, N.A.20
Wisconsin Women's Business Initiative Corporation20
Associated Bank National Association14

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Automotive mechanical repair (car and truck), SBA 504: lenders by loans approved
LenderLoans
WBD, Inc.45

Download this table (CSV). Cite as: Loan Analytics, Automotive mechanical repair (car and truck), SBA 504: lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Automotive mechanical repair (car and truck), SBA 7(a): lenders by loans approved
LenderLoans
Summit CU25
Bank First, N.A.16
U.S. Bank, National Association15
Associated Bank National Association14
The Huntington National Bank13

Download this table (CSV). Cite as: Loan Analytics, Automotive mechanical repair (car and truck), SBA 7(a): lenders by loans approved, https://www.analytics.loan/wisconsin-feasibility-study-data#state-record.

Feasibility study data by asset class in Wisconsin

Feasibility study data by asset class and SBA program in Wisconsin

Feasibility study data by metro area in Wisconsin

Source: U.S. Small Business Administration, 7(a) and 504 loan-level FOIA files (data.sba.gov), as of 2026-09-30. Totals add the state's cells across the tracked asset classes; they are not all SBA lending in Wisconsin.

Feasibility study questions for Wisconsin

How many SBA loans have gone to Wisconsin projects in the asset classes Loan Analytics tracks?

Wisconsin's FY2017 to FY2026 record in the Loan Analytics classes holds 3,860 SBA 7(a) and 504 loans worth $2.59 billion. Wisconsin 7(a) loans account for 3,037 and $1.80 billion and Wisconsin 504 loans for 823 and $786.2 million. Wisconsin cells from SBA's loan files cover the tracked classes only, so the totals are smaller than all SBA lending in Wisconsin.

Which asset classes receive the most SBA loans in Wisconsin?

Full-service restaurants lead Wisconsin with 651 loans ($319.1 million) and limited-service restaurants follow at 397 ($187.3 million). Automotive mechanical repair ranks third at 279. Hotels and motels hold 254 loans and the largest dollar total, $429.6 million. Child care centers (251), fitness centers (246) and gas stations (241, $243.6 million) come next, then beauty salons and beverage manufacturing at 161.

How often are SBA loans in Wisconsin cancelled or charged off?

For Wisconsin, the cancellation floor is 10.9% among fiscal 2017 to 2024 approvals, while the Wisconsin charge-off floor is 2.8% among fiscal 2017 to 2021 disbursements; five years on from approval, 1.5% of Wisconsin loans were charged off. Each Wisconsin rate is a floor, since open loans carry no reported result, and none is printed without a cohort of 30 loans.

Which lenders make the most SBA loans in Wisconsin?

WBD, Inc. dominates Wisconsin's SBA 504 tables, with 115 full-service restaurant loans, 42 limited-service and 45 in automotive repair. The 7(a) tables are more spread out: Byline Bank leads full-service restaurants with 30 and Nicolet National Bank has 28, Bank Five Nine leads limited-service with 24, and Summit CU leads automotive mechanical repair with 25. Wisconsin Women's Business Initiative Corporation appears in both restaurant tables.

Which Wisconsin programs can support a project financed with an SBA or USDA loan?

The Wisconsin Economic Development Corporation (WEDC) is the state's lead economic development organization and the office to ask about programs that could aid a Wisconsin project carrying SBA or USDA debt. WEDC's pages fell outside the review for this answer, so the answer stops at naming WEDC. With 823 SBA 504 loans in Wisconsin's record, a borrower should bring the certified development company into that conversation early.

Which state permits and approvals should a feasibility study for a project in Wisconsin account for?

The Wisconsin DNR's business permits page explains when a project needs state environmental approvals, and its Enviro-Nav tool helps a business sort out which apply. Air permits cover construction and operation of sources above emission thresholds. A Wisconsin Pollutant Discharge Elimination System (WPDES) permit is needed for wastewater discharged anywhere other than a municipal treatment plant, a construction site storm water permit applies when a project disturbs an acre or more, and a private water system serving enough people triggers drinking water requirements.

Source: Business Permits and Reporting Requirements | | Wisconsin DNR, Wisconsin Department of Natural Resources

What does a feasibility study cost?

For a Wisconsin restaurant or gas station, the published-fee survey on this site prices a single-site SBA study at $5,000 to $12,500. Wisconsin hotels, which carry $429.6 million, usually need complex work in the $10,000 to $25,000 band. Program matters as much as asset class: a study written to USDA's enumerated 37 factors costs more than one written to the SBA's discretionary standard.

Source: SBA Feasibility Study Cost in 2026: Price Bands by Asset Class, and the Fee as Basis Points of the Loan, Loan Analytics

What does a feasibility study for a project in Wisconsin test first?

In Wisconsin the method begins with scoping, and with 823 SBA 504 loans in the record, many studies are framed to the 504 rules on equity and collateral. Wisconsin restaurants, 651 full-service and 397 limited-service loans, are judged first on the trade area and capture rate. Gas stations, 241 loans worth $243.6 million, need early site work on access and environmental factors, and Wisconsin hotels, 254 loans, need verified occupancy and a downside test of coverage.

Source: How a Feasibility Study Is Done: The Loan Analytics Methodology, Loan Analytics

SBA lending in Wisconsin, FY1991 to FY2026

Every SBA 7(a) and 504 loan approved for a project in Wisconsin since FY1991, by fiscal year, from SBA's own loan files.

Counts peaked in FY2005, dollars in FY2021

Wisconsin's SBA 7(a) loan count topped out in FY2005, with 1,996 loans for $376.3 million, and held near that level through FY2007 (1,964 loans). The dollar high came much later: FY2021's 1,326 SBA 7(a) loans carried $774.9 million and FY2011's 1,865 carried $738.2 million, well clear of the next largest year, FY2025 at $551.1 million. Both peaks were single-year surges, FY2011 between FY2010's $408.7 million and FY2012's $468.2 million, so a study that cites Wisconsin SBA volume as proof of a deep lending market should cite a run of years, never the best one.

FY2026: the fewest loans since FY2000

The FY2026 line shows 861 SBA 7(a) loans for Wisconsin projects, fewer than in any year since FY2000's 758. Yet those 861 loans carried $513.8 million, a total no Wisconsin year from FY1991 through FY2010 reached; the best of them was FY2010 at $408.7 million. Against FY2005, when 1,996 loans carried $376.3 million, Wisconsin lenders now approve far fewer SBA 7(a) loans and put more money behind each. A projection today carries a heavier debt service than one at the FY2005 peak, so the study tests coverage at the amount actually requested, under a downside.

The SBA 504 record belongs to recent years

Wisconsin's SBA 504 program set its record in FY2021 with 341 loans for $297.8 million, and FY2022 nearly matched it at 335 loans and $287.1 million, beside $500.1 million of SBA 7(a), the closest the programs have come in dollars in the record. The only earlier year in that range was FY2012, a one-year jump to 334 loans, and since FY2023 the line has held between 173 and 200 loans a year. As this page's market discussion describes it, a 504 loan pairs a Certified Development Company with a conventional lender to fund owner-occupied property and large fixed assets, so a Wisconsin study is often read by both, and must support the total project budget as well as the operating case.

The tracked classes, year by year

The page's fiscal-year table for the tracked classes shows the same shift: FY2017's 465 loans in those classes carried $244.9 million, FY2025's 357 carried $283.4 million, and FY2026 holds the fewest, 275 for $201.3 million. These classes are one slice of a state book of 10,971 SBA 7(a) and 2,186 SBA 504 loans over the same years, and a study should say which count it quotes.

The long record and the recent one

Of the $4.10 billion in SBA 504 loans Wisconsin projects have drawn since FY1991, $1.95 billion was approved from FY2017 to FY2026, on 2,186 of the 5,911 loans; of $13.14 billion in SBA 7(a) loans, $5.24 billion falls in the same years, on 10,971 of 44,404. The early record is a different market: FY1995 shows 1,599 SBA 7(a) loans for $234.7 million against 923 loans and $230.1 million a year earlier, a burst of small loans that barely moved the dollar total. A projection benchmarked against the full history mixes those eras, so the study benchmarks against FY2017 to FY2026.

SBA 7(a) and 504 loans approved in Wisconsin by fiscal year
Fiscal yearSBA 7(a) loansSBA 7(a) dollarsSBA 504 loansSBA 504 dollars
FY1991494$126.0 million57$21.1 million
FY1992571$171.2 million48$19.7 million
FY1993648$189.2 million61$23.5 million
FY1994923$230.1 million83$33.1 million
FY19951,599$234.7 million107$47.5 million
FY19961,007$152.4 million155$69.8 million
FY1997866$172.9 million71$27.5 million
FY1998759$147.6 million97$44.8 million
FY1999846$155.1 million115$55.1 million
FY2000758$146.8 million117$57.0 million
FY2001881$183.1 million116$58.2 million
FY20021,073$215.9 million118$57.3 million
FY20031,284$221.6 million131$62.6 million
FY20041,637$309.8 million176$84.2 million
FY20051,996$376.3 million197$118.7 million
FY20061,930$308.7 million197$107.1 million
FY20071,964$325.8 million204$115.2 million
FY20081,795$303.1 million196$108.6 million
FY20091,510$309.0 million171$98.7 million
FY20101,551$408.7 million199$130.4 million
FY20111,865$738.2 million161$97.1 million
FY20121,403$468.2 million334$247.6 million
FY20131,456$522.2 million200$135.2 million
FY20141,538$447.0 million137$97.4 million
FY20151,593$491.7 million140$115.9 million
FY20161,486$538.2 million137$118.3 million
FY20171,312$500.3 million191$150.4 million
FY20181,277$511.0 million150$116.0 million
FY20191,074$426.3 million175$136.0 million
FY2020972$458.7 million251$205.8 million
FY20211,326$774.9 million341$297.8 million
FY2022958$500.1 million335$287.1 million
FY2023964$482.1 million182$173.3 million
FY20241,099$524.5 million173$188.3 million
FY20251,128$551.1 million200$205.4 million
FY2026861$513.8 million188$191.8 million
FY1991 to FY202644,404$13.14 billion5,911$4.10 billion
FY2017 to FY202610,971$5.24 billion2,186$1.95 billion

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Download this table (CSV). Cite as: Loan Analytics, "SBA 7(a) and 504 loans approved in Wisconsin by fiscal year", https://www.analytics.loan/wisconsin-feasibility-study-data#sba-record-sba-by-year.

Back to the contents

Asset classes financed in Wisconsin, ranked

Each asset class Loan Analytics tracks, ranked by SBA loans approved in Wisconsin from FY2017 to FY2026, with loan size, program split and the cohort floors where at least 30 loans support them.

Two rankings of the same classes

By count, full-service restaurants lead Wisconsin's tracked classes with 651 loans, ahead of limited-service restaurants (397) and automotive repair (279), with hotels and motels fourth (254) and gas stations and truck stops seventh (241). By dollars, hotels and motels lead with $429.6 million, full-service restaurants follow at $319.1 million and gas stations climb to third at $243.6 million. Dental offices, twelfth by count with 126 loans, rank sixth by dollars at $117.4 million, and self storage, tenth by count, ranks seventh at $116.8 million. A study's depth follows the money at risk, not how common the class is.

Median loans by tier

Hotels and motels stand alone at a $1.4 million median. Gas stations ($780,000) and car washes ($745,000) form the next tier, then dental offices ($608,500), assisted living ($549,000) and self storage ($522,800). Beauty salons borrow least, at $119,500, then rehabilitation and therapy clinics at $150,000. Limited-service restaurants ($304,000) edge past child care centers ($303,500) and full-service restaurants ($290,000), so in Wisconsin the counter-service restaurant is the bigger restaurant loan at the median and its projection must cover the heavier payment.

Where SBA 504 outnumbers SBA 7(a)

Self storage is Wisconsin's clearest 504 class, with 74 SBA 504 loans against 65 SBA 7(a), and RV parks and campgrounds lean the same way, 39 against 24. Hotels and motels split 158 SBA 7(a) and 96 SBA 504, beverage manufacturing 120 and 41, and assisted living 74 and 38. Several classes sit almost wholly in 7(a): beauty salons have 9 SBA 504 loans in 192, coffee shops 9 in 134 and nonresidential lessors 1 in 53. A Wisconsin self storage or campground study will most likely be read by a CDC and its partner bank, and it must carry the real estate and construction budget as well as the lease-up case.

Approvals cancelled, class by class

Around the state's 10.9% cancellation floor the classes spread widely. Coffee shops and snack bars print 15.3%, limited-service restaurants 13.9%, liquor stores 13.0% and self storage 12.4%, with automotive repair and child care centers at 12.1%. Full-service restaurants print 7.9%, medical offices 5.0% and car washes 0.00% on 39 loans. Cancellation means SBA approved the loan and the deal then fell away, so in the high-floor classes a lender wants the study to show the deal can close as approved: the site under control, a budget that holds and an opening date the financing can meet.

Losses after disbursement, class by class

Charge-off floors reorder the classes again. Assisted living prints 5.5%, full-service restaurants 5.2%, liquor stores 4.9%, limited-service restaurants 4.7% and beauty salons 4.6%. Gas stations, with the second-largest median loan, print only 1.5%, and hotels and motels, child care centers, self storage, coffee shops, dental offices, veterinary clinics and RV parks print 0.00%. Full-service restaurants pair a low cancellation floor with a high charge-off floor, so their risk arrives after the money is out, and the study must stress the operating years. Every rate is a floor, since SBA withholds the outcome of open loans, and 0.00% is no proof a class cannot lose.

Classes too thin for a state measure

Under 30 loans the page prints no median and no floor, and several larger-ticket classes fall there: skilled nursing has 23 loans for $25.7 million, warehouse and distribution 21 for $29.2 million, cold storage 10 for $23.7 million and continuing care retirement communities 9 for $17.4 million. Car washes, medical offices and caterers have no reported charge-off floor. For these classes a Wisconsin study cannot lean on the state's SBA record for loss evidence; it builds the case from the subject's market, the class record nationally and nearby operators, and says plainly that the Wisconsin sample is small.

SBA loans in Wisconsin by asset class, FY2017 to FY2026
Asset classLoansDollarsMedian loanSBA 7(a) loansSBA 504 loansCancelled (floor)Charged off (floor)
Full-service restaurant651$319.1 million$290,0005171347.9%5.2%
Limited-service restaurant397$187.3 million$304,0003425513.9%4.7%
Automotive mechanical repair (car and truck)279$108.1 million$225,0002324712.1%2.3%
Hotel and motel254$429.6 million$1.4 million1589611.4%0.00%
Child care center251$143.7 million$303,5002024912.1%0.00%
Fitness center246$108.6 million$191,9002153110.8%3.7%
Gas station and truck stop241$243.6 million$780,0001954611.0%1.5%
Beauty salon192$41.2 million$119,500183911.4%4.6%
Beverage manufacturing (breweries, wineries, distilleries)161$91.7 million$298,000120419.1%1.9%
Self storage139$116.8 million$522,800657412.4%0.00%
Coffee shop and snack bar134$43.9 million$176,000125915.3%0.00%
Dental office126$117.4 million$608,500903611.6%0.00%
Assisted living (without nursing care)112$108.2 million$549,00074389.9%5.5%
Grocery store97$74.4 million$492,000732410.7%2.0%
Veterinary clinic88$65.7 million$470,500632510.4%0.00%
Liquor store83$45.3 million$340,00075813.0%4.9%
RV park and campground63$53.5 million$474,00024399.3%0.00%
Nonresidential lessor (flex, office and retail investor buildings)53$35.3 million$350,0005219.6%3.0%
Medical office (physicians)48$30.8 million$250,00038105.0%not reported: fewer than 30 loans in the cohort
Car wash39$44.5 million$745,00027120.00%not reported: fewer than 30 loans in the cohort
Caterers (includes banquet halls with catering staff)38$18.6 million$175,0003449.4%not reported: fewer than 30 loans in the cohort
Rehabilitation and therapy clinic32$7.5 million$150,000302not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Skilled nursing23$25.7 milliontoo few loans for these measures
Behavioral health and addiction treatment22$11.8 milliontoo few loans for these measures
Warehouse and distribution21$29.2 milliontoo few loans for these measures
Data center16$10.3 milliontoo few loans for these measures
Cold storage10$23.7 milliontoo few loans for these measures
Continuing care retirement community9$17.4 milliontoo few loans for these measures
Manufactured housing community (lessors of other real estate)8$5.4 milliontoo few loans for these measures
Marina7$7.3 milliontoo few loans for these measures
Life science lab (research and development)5$4.2 milliontoo few loans for these measures
Multifamily (lessors of residential buildings)4fewer than five loanstoo few loans for these measures
School (elementary and secondary, including charter)4fewer than five loanstoo few loans for these measures
Diagnostic imaging center3fewer than five loanstoo few loans for these measures
Hospital3fewer than five loanstoo few loans for these measures
Urgent care and ambulatory surgery1fewer than five loanstoo few loans for these measures

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA loans in Wisconsin by asset class, FY2017 to FY2026", https://www.analytics.loan/wisconsin-feasibility-study-data#asset-classes-classes.

Back to the contents

Metro and micro areas in Wisconsin

SBA lending in the metropolitan and micropolitan areas that reach into Wisconsin, ranked by loans: every SBA 7(a) and 504 approval in each area, all industries together, not only the asset classes Loan Analytics tracks.

Cross-border rows count the whole area

The metro table counts each area whole, and some rows cross the state line. The Minneapolis-St. Paul-Bloomington row, 12,697 loans and $6.03 billion, comes close to Wisconsin's entire statewide count of 13,157 SBA loans for the same years, so most of it lies in Minnesota. Duluth (712 loans), La Crosse-Onalaska (392) and Marinette (124) also straddle a border. A Wisconsin-side project in these areas is read against the whole area, so its study should state which side of the line its comparables come from.

Milwaukee and Madison

Among areas wholly inside Wisconsin, Milwaukee-Waukesha leads with 3,857 loans and $2.19 billion at a $268,000 median and a 2.8% charge-off floor. Madison follows with 1,680 loans and $930.4 million, at a lower median, $234,000, and a higher floor, 3.6%. The population discussion on this page puts the state's fastest growth in Dane County and a slow decline in Milwaukee County, yet in the SBA record the growing market makes the smaller loans and shows the higher loss floor. A Madison study that leans on headline growth without testing competitive supply will meet a lender who knows that 3.6% floor.

Green Bay and the Fox Valley

Green Bay (728 loans, $391.0 million, $250,000 median) and Appleton (613 loans, $308.9 million, $220,500 median) come next, with floors of 3.2% and 1.8%, and Oshkosh-Neenah adds 344 loans at a 2.9% floor. Appleton's 1.8% is the lowest printed floor of any area wholly within the state, and Appleton outranks Duluth by dollars on fewer loans, $308.9 million against $276.3 million on 712. A Fox Valley study can cite a strong local loss record, but its reader knows that record and expects projections that sit inside it.

Smaller markets, larger medians

Several smaller markets borrow more at the median than Milwaukee-Waukesha: Janesville-Beloit at $350,000, the highest in the table, on 170 loans; Fond du Lac at $318,500; Sheboygan at $310,000; and Wausau at $301,000. The lowest medians belong to Duluth ($179,250) and Racine-Mount Pleasant ($187,500). In the high-median smaller markets a study supports a bigger loan with fewer local comparables behind it, so its fieldwork verifies competitors, rents and sales directly instead of leaning on a deep local file of SBA deals.

Loss floors and withheld areas

Racine-Mount Pleasant prints the highest floor shown in the table, 5.9%, on 500 loans, and La Crosse-Onalaska follows at 4.0%. Eau Claire, Sheboygan, Kenosha, Whitewater-Elkhorn, Manitowoc, Fond du Lac, Janesville-Beloit, Watertown-Fort Atkinson and Marinette print a withheld floor, so no rate is given for them here. Dollars cut across counts here too: Eau Claire's 432 loans carry $248.7 million, more than Racine-Mount Pleasant's $232.4 million, and Kenosha's 345 loans carry $204.0 million against Sheboygan's $200.2 million on 371. A Racine-area study faces the weakest printed loss record among the state's metros and should show, with the subject's own figures, why the project differs from it.

SBA loans by metro area touching Wisconsin, FY2017 to FY2026
Metro or micro areaLoansDollarsMedian loanCharged off (floor)
Minneapolis-St. Paul-Bloomington, MN-WI Metro Area12,697$6.03 billion$200,0003.9%
Milwaukee-Waukesha, WI Metro Area3,857$2.19 billion$268,0002.8%
Madison, WI Metro Area1,680$930.4 million$234,0003.6%
Green Bay, WI Metro Area728$391.0 million$250,0003.2%
Duluth, MN-WI Metro Area712$276.3 million$179,2501.4%
Appleton, WI Metro Area613$308.9 million$220,5001.8%
Racine-Mount Pleasant, WI Metro Area500$232.4 million$187,5005.9%
Eau Claire, WI Metro Area432$248.7 million$250,000withheld
La Crosse-Onalaska, WI-MN Metro Area392$208.6 million$215,5004.0%
Sheboygan, WI Metro Area371$200.2 million$310,000withheld
Kenosha, WI Metro Area345$204.0 million$212,400withheld
Oshkosh-Neenah, WI Metro Area344$169.0 million$214,5002.9%
Wausau, WI Metro Area281$165.3 million$301,0003.6%
Whitewater-Elkhorn, WI Micro Area241$131.6 million$248,500withheld
Manitowoc, WI Micro Area219$124.8 million$250,000withheld
Fond du Lac, WI Metro Area188$125.8 million$318,500withheld
Janesville-Beloit, WI Metro Area170$119.1 million$350,000withheld
Watertown-Fort Atkinson, WI Micro Area152$82.4 million$247,000withheld
Marinette, WI-MI Micro Area124$70.0 million$243,450withheld

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA loans by metro area touching Wisconsin, FY2017 to FY2026", https://www.analytics.loan/wisconsin-feasibility-study-data#metros-metros.

Back to the contents

SBA lenders in Wisconsin

The SBA lenders with a recorded book of loans for projects in Wisconsin, ranked by loans; no lender with fewer than 5 loans is listed.

WBD, Inc. and the 504 desks

WBD, Inc. heads the Wisconsin lender table with 1,902 loans, $1.69 billion and a 0.56% charge-off floor from FY2017 to FY2026, set against 2,186 SBA 504 loans for the state over the same years, and the class tables list it as the SBA 504 lender for full-service restaurants (115 loans), limited-service restaurants (42) and automotive repair (45). Racine County Economic Development Corporation, with 185 loans, $155.2 million and a 0.00% floor, appears beside it in both restaurant 504 tables with 12 loans each. A CDC reading a Wisconsin 504 study has a large file of comparable deals and a low printed loss floor, and it judges the subject against both.

By dollars, a different order

After WBD, Inc., the largest dollar books belong to Byline Bank ($487.1 million on 443 loans), Old National Bank ($238.5 million on 261), The Huntington National Bank ($214.8 million on 605), Nicolet National Bank ($209.9 million on 479), Bank Five Nine ($199.7 million on 383) and Live Oak Banking Company ($190.6 million on 151). U.S. Bank, National Association is second by count with 868 loans but carries $173.5 million. A hotel loan near the $1.4 million class median is an ordinary ticket for Byline Bank or Live Oak Banking Company and a large one for U.S. Bank, National Association, so the study is pitched to the reader's book: large-ticket desks press on cost basis and coverage, small-loan desks on whether the borrower's experience fits the project.

Where lender loss floors diverge

Lender floors vary far more than class floors. Northeast Bank (ME) prints 23.5% on 184 loans worth $25.5 million, JPMorgan Chase Bank, National Association 11.1% on 132 loans and Wells Fargo Bank National Association 7.1% on 171. At the other end sit WBD, Inc. at 0.56%, Summit CU at 1.4% and Nicolet National Bank at 1.7%, with Lake Ridge Bank and Forward Bank at 0.00%. The highest floors belong mostly to small-loan books, though Byline Bank prints 4.9% on a large-ticket one, and many lenders, Bank First, N.A. among them, have floors withheld and get no number here. A project does not inherit its lender's floor, but the credit officer's experience sets how hard the downside case is pressed.

Community banks and credit unions

Below the largest banks, Wisconsin's SBA book runs through state and community lenders: Waukesha State Bank (276 loans, $155.7 million), Hiawatha National Bank (272), CCFBank National Association (238, $150.5 million), Lake Ridge Bank (172) and IncredibleBank (137), with Community State Bank (WI) at 221 loans and a 3.6% floor. Summit CU, fourth in the state by count with 538 loans, leads SBA 7(a) lending to automotive repair with 25 loans, and Wisconsin Women's Business Initiative Corporation, 293 loans for $42.3 million, appears in the SBA 7(a) tables of both restaurant classes. When the reader is a community lender, the study's comparables should come from the market that lender already serves.

SBA lenders by loans approved in Wisconsin, FY2017 to FY2026
LenderLoansDollarsCharged off (floor)
WBD, Inc.1,902$1.69 billion0.56%
U.S. Bank, National Association868$173.5 million5.5%
The Huntington National Bank605$214.8 million4.4%
Summit CU538$140.4 million1.4%
Nicolet National Bank479$209.9 million1.7%
Byline Bank443$487.1 million4.9%
Bank First, N.A.428withheldwithheld
Bank Five Nine383$199.7 millionwithheld
Associated Bank National Association356$111.0 millionwithheld
Wisconsin Women's Business Initiative Corporation293$42.3 millionwithheld
Waukesha State Bank276$155.7 millionwithheld
Hiawatha National Bank272$106.9 millionwithheld
Old National Bank261$238.5 millionwithheld
CCFBank National Association238$150.5 millionwithheld
Community State Bank (WI)221$49.9 million3.6%
Racine County Economic Development Corporation185$155.2 million0.00%
Northeast Bank (ME)184$25.5 million23.5%
Lake Ridge Bank172$52.1 million0.00%
Wells Fargo Bank National Association171$62.8 million7.1%
Live Oak Banking Company151$190.6 millionwithheld
IncredibleBank137$93.1 millionwithheld
JPMorgan Chase Bank, National Association132$28.7 million11.1%
Newtek Bank, National Association127$42.6 millionnot reported: fewer than 30 loans in the cohort
Readycap Lending, LLC120$38.7 millionwithheld
American National Bank-Fox Cities113$30.2 millionwithheld
BMO Bank National Association110$73.1 millionwithheld
BayFirst National Bank107$18.0 millionwithheld
Celtic Bank Corporation106$55.8 millionwithheld
Fortifi Bank101$29.6 millionwithheld
Oostburg State Bank98$44.7 millionwithheld
Forward Bank96$21.4 million0.00%
United Midwest Savings Bank National Association93$27.8 millionwithheld
Security Financial Bank92$30.3 million0.00%
Citizens State Bank of La Crosse76$17.1 millionwithheld
Fox Communities CU68$11.2 million0.00%
Citizens Bank (WI)67$21.2 millionwithheld
Town Bank, National Association67$32.1 millionwithheld
Peoples State Bank (WI, fdic-18569)63$37.8 millionnot reported: fewer than 30 loans in the cohort
Ixonia Bank62$39.7 millionwithheld
The Stephenson National Bank and Trust62$27.8 millionwithheld
Newtek Small Business Finance, LLC62$39.3 millionwithheld
National Exchange Bank and Trust60$33.6 millionwithheld
One Community Bank57$26.6 millionwithheld
Frandsen Bank and Trust54$23.8 millionwithheld
First Business Bank54$47.6 millionwithheld
Park Bank National Association47$12.1 millionwithheld
Cleveland State Bank47$20.1 millionnot reported: fewer than 30 loans in the cohort
UMB Bank, National Association46$47.5 millionwithheld
Oak Bank44$20.5 millionwithheld
First American Bank (IL)44$26.9 millionwithheld
Northeast Entrepreneur Fund, Inc.44$5.1 millionwithheld
PyraMax Bank FSB42$11.3 millionwithheld
Stearns Bank National Association40$13.9 millionwithheld
First Internet Bank of Indiana40$45.4 millionwithheld
Citizens State Bank (WI, fdic-6194)40$9.7 millionwithheld
State Bank Financial39$11.5 millionwithheld
CIBM Bank39$29.1 millionwithheld
The Bank of Kaukauna38$14.4 millionnot reported: fewer than 30 loans in the cohort
First Bank of the Lake38$28.1 millionwithheld
PNC Bank, National Association38$15.1 millionwithheld
Horicon Bank37$24.6 millionwithheld
First Citizens State Bank35$16.3 millionnot reported: fewer than 30 loans in the cohort
CenTrust Bank, A Division of SmartBiz Bank National Association33$20.6 millionnot reported: fewer than 30 loans in the cohort
Landmark Credit Union32$1.8 millionnot reported: fewer than 30 loans in the cohort
Educators Credit Union31$7.9 millionwithheld
First National Community Bank (WI)30$5.3 millionnot reported: fewer than 30 loans in the cohort
Milwaukee Economic Development Corporation30$6.3 millionwithheld
Prevail Bank29$8.4 millionwithheld
Merchants Bank, National Association29$12.0 millionwithheld
Bank of Mauston28$10.4 millionnot reported: fewer than 30 loans in the cohort
Bank of Sun Prairie28$11.0 millionwithheld
BankVista28$22.3 millionwithheld
Coulee Bank27$17.1 millionnot reported: fewer than 30 loans in the cohort
Johnson Bank27$21.5 millionnot reported: fewer than 30 loans in the cohort
Harvest Small Business Finance, LLC27$19.1 millionnot reported: fewer than 30 loans in the cohort
Twin Cities-Metro Certified Development Company26$23.4 millionwithheld
The Park Bank25$7.6 millionwithheld
Verve, a Credit Union25$4.6 millionwithheld

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lenders by loans approved in Wisconsin, FY2017 to FY2026", https://www.analytics.loan/wisconsin-feasibility-study-data#lenders-lenders.

Back to the contents

Wisconsin against its Census division and the nation

Wisconsin beside the other states of the East North Central Census division, all SBA lending and the tracked asset classes.

Fourth in the division, with Indiana closing in

Over FY1991 to FY2026 Wisconsin ranks fourth in the East North Central division with 50,315 SBA loans, behind Ohio (95,823), Illinois (75,120) and Michigan (66,059) and well ahead of Indiana (40,176). In the FY2017 to FY2026 record it holds fourth only narrowly, 13,157 loans against Indiana's 13,129, while Ohio (33,343), Michigan (24,001) and Illinois (22,837) pull away. Wisconsin's long lead over Indiana has all but vanished, so a study that quotes long-run Wisconsin volume to show demand is describing a market that has changed.

Fewer loans, larger ones

By dollars Wisconsin is also fourth, at $7.19 billion against Illinois' $12.89 billion, Ohio's $11.30 billion and Michigan's $9.53 billion, and it stays clear of Indiana's $6.28 billion on nearly identical counts. Michigan needed 24,001 loans to reach $9.53 billion; Wisconsin reached $7.19 billion on 13,157. Wisconsin borrowers take larger SBA loans than most of their division, so a study should benchmark the requested amount against Wisconsin's own loans, not a regional average pulled down by Ohio's and Michigan's smaller tickets, and should treat the national line, 647,329 loans and $353.09 billion over the same years, as context only.

Wisconsin's loss floor against its neighbors

Wisconsin's tracked-class charge-off floor, 2.8%, is the lowest of the division's states: Illinois prints 5.2%, Ohio 4.4%, Michigan 3.3% and Indiana 3.2%. Its tracked-class book ranks fourth, 3,860 loans against Ohio's 7,638, Illinois' 6,489 and Michigan's 6,223, ahead of Indiana's 3,547. A Wisconsin lender judges a projection against the best printed loss record in its region, so a study that borrows operating assumptions from Illinois or Ohio markets imports a weaker record than its reader expects the project to match.

SBA lending: Wisconsin, the East North Central division and the United States
StateAll SBA loans FY1991 to FY2026All SBA loans FY2017 to FY2026All SBA dollars FY2017 to FY2026Loans in tracked classes FY2017 to FY2026Charged off, tracked classes (floor)
Illinois75,12022,837$12.89 billion6,4895.2%
Indiana40,17613,129$6.28 billion3,5473.2%
Michigan66,05924,001$9.53 billion6,2233.3%
Ohio95,82333,343$11.30 billion7,6384.4%
Wisconsin50,31513,157$7.19 billion3,8602.8%
United States2,207,426647,329$353.09 billion

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lending: Wisconsin, the East North Central division and the United States", https://www.analytics.loan/wisconsin-feasibility-study-data#compare-compare.

Back to the contents

Wisconsin's economy for a feasibility study

The establishments, jobs and payroll of each asset class's industry in Wisconsin, and the state's population, income and output, from the Census Bureau and the Bureau of Economic Analysis.

Slow headcount, fast nominal income

By the Census Bureau's count Wisconsin had 5,822,434 residents in 2019 and 5,960,975 in 2024, and median household income climbed from $64,168 to $77,488 between those years. Wisconsin's gross domestic product, in the Bureau of Economic Analysis series, went from $346.60 billion in 2019 to $478.78 billion in 2025, and its personal income from $307.94 billion to $425.37 billion. These are current-dollar figures with different end years, so none of them is real growth; the smaller economy quoted in this page's narrative is the inflation-adjusted measure. Population rose slowly and nominal income fast, so a Wisconsin demand case rests more on real spending per household than on new households.

Restaurants: fewer full-service workers, many more coffee shops

Full-service restaurants, Wisconsin's largest SBA class, lost ground in County Business Patterns: establishments fell from 5,030 in 2018 to 4,988 in 2023 and employees from 98,142 to 87,044, on a 2023 payroll of $1.93 billion. Limited-service restaurants grew from 3,782 to 3,925 establishments with employment nearly flat, 76,342 to 76,596. The fastest growth among the food classes came in coffee shops and snack bars: 894 establishments became 1,243, and 9,327 employees became 13,801. A full-service study has to show how the subject will staff a sector that shed workers, and a coffee shop study has to test saturation, since competitors multiplied and the class prints the highest cancellation floor of any Wisconsin class with a reported rate, 15.3%.

Fuel and lodging: establishments and jobs moving apart

Gas station establishments in the larger of the industry's codes fell from 2,338 to 2,271 while employees rose from 24,668 to 28,905, and the smaller code grew from 237 to 262 establishments and from 2,835 to 4,180 employees. Fewer stations employing more people fits the class's $780,000 median and the page's point that inside sales and food service now carry the margin, so a fuel study tests those lines, not gallons alone. Hotels and motels moved the other way, from 1,097 to 1,168 establishments while employees fell from 28,717 to 27,500, and a hotel study must count the newer properties in its competitive set.

Growth classes

Breweries went from 84 to 118 establishments and from 2,625 to 3,432 employees between 2018 and 2023, and distilleries from 17 to 28; the SBA beverage manufacturing class holds 161 Wisconsin loans at a $298,000 median, with floors of 9.1% cancelled and 1.9% charged off. RV parks and campgrounds rose from 168 to 187 establishments and car washes from 210 to 261, though car wash employment fell from 1,998 to 1,750. In a growing class the competitive set comes first: entrants since 2023 are missing from these counts, and the lender expects the study to find them in the field.

Shrinking and consolidating classes

Beauty salons fell from 1,771 establishments to 1,592 and from 10,930 employees to 8,345, and the class carries a 4.6% charge-off floor. Dental offices fell from 2,009 to 1,902 establishments while employees rose from 17,671 to 18,368, so fewer offices now employ more staff; at a $608,500 median loan, a Wisconsin dental study underwrites a practice of real size and must document its patient base. Assisted living held level at 984 and 989 establishments while employees fell from 19,722 to 18,175, and with the highest printed class charge-off floor in the state, 5.5%, staffing belongs at the center of any assisted living study here.

Medical offices and the limits of the census counts

Physicians' offices carry the largest payroll in the table, $6.56 billion in 2023, after growing from 2,255 to 3,107 establishments, yet the state's SBA record holds only 48 medical office loans. County Business Patterns omits most government and self-employed activity, suppresses small cells and ends in 2023, so a study uses it to size an industry and confirms the local count in the field.

Industry establishments, employees and payroll in Wisconsin, by asset class
Asset class (NAICS)Establishments 2018Establishments 2023Employees 2018Employees 2023Annual payroll 2023
Full-service restaurant (NAICS 722511)5,0304,98898,14287,044$1.93 billion
Limited-service restaurant (NAICS 722513)3,7823,92576,34276,596$1.43 billion
Automotive mechanical repair (car and truck) (NAICS 811111)1,8681,8718,2858,948$472.1 million
Automotive mechanical repair (car and truck) (NAICS 811112)23168877$3.0 million
Automotive mechanical repair (car and truck) (NAICS 811113)5640214160$8.0 million
Automotive mechanical repair (car and truck) (NAICS 811118)5456245214$9.7 million
Hotel and motel (NAICS 721110)1,0971,16828,71727,500$742.7 million
Child care center (NAICS 624410)1,5831,58819,48519,025$543.8 million
Fitness center (NAICS 713940)74383619,90417,773$263.8 million
Gas station and truck stop (NAICS 447110)2,3382,27124,66828,905$753.8 million
Gas station and truck stop (NAICS 447190)2372622,8354,180$131.7 million
Beauty salon (NAICS 812112)1,7711,59210,9308,345$253.4 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312120)841182,6253,432$175.2 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312130)6269533610$16.7 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312140)1728131281$10.3 million
Self storage (NAICS 531130)131143293319$12.1 million
Coffee shop and snack bar (NAICS 722515)8941,2439,32713,801$247.3 million
Dental office (NAICS 621210)2,0091,90217,67118,368$1.33 billion
Assisted living (without nursing care) (NAICS 623312)98498919,72218,175$539.3 million
Grocery store (NAICS 445110)99397648,98649,922$1.24 billion
Veterinary clinic (NAICS 541940)7007027,4869,364$454.6 million
Liquor store (NAICS 445310)4244442,0852,155$50.6 million
RV park and campground (NAICS 721211)168187521735$31.6 million
Nonresidential lessor (flex, office and retail investor buildings) (NAICS 531120)3633611,6161,977$129.9 million
Medical office (physicians) (NAICS 621111)2,2553,10744,80063,015$6.56 billion
Car wash (NAICS 811192)2102611,9981,750$53.1 million
Caterers (includes banquet halls with catering staff) (NAICS 722320)2102082,3491,980$48.6 million
Rehabilitation and therapy clinic (NAICS 621340)5647475,6925,846$296.1 million

Source: U.S. Census Bureau, County Business Patterns 2018 and 2023 (NAICS 2017), through the Census Data API; establishments, March employment and annual payroll; suppressed cells print their flag. Most government and self-employed activity is outside CBP. Download this table (CSV). Cite as: Loan Analytics, "Industry establishments, employees and payroll in Wisconsin, by asset class", https://www.analytics.loan/wisconsin-feasibility-study-data#economy-industry.

Population and household income in Wisconsin
Measure20192024
Population5,822,4345,960,975
Median household income$64,168$77,488

Source: U.S. Census Bureau, American Community Survey 1-year estimates, 2019 and 2024, through the Census Data API (tables B01003 and B19013). Download this table (CSV). Cite as: Loan Analytics, "Population and household income in Wisconsin", https://www.analytics.loan/wisconsin-feasibility-study-data#economy-people.

Output and income in Wisconsin
MeasureEarlier yearLatest year
Gross domestic product, 2019 and 2025$346.60 billion$478.78 billion
Personal income, 2019 and 2025$307.94 billion$425.37 billion

Source: U.S. Bureau of Economic Analysis, regional accounts (SAGDP2 all-industry total, current dollars; SAINC1 personal income), through the BEA API. Download this table (CSV). Cite as: Loan Analytics, "Output and income in Wisconsin", https://www.analytics.loan/wisconsin-feasibility-study-data#economy-output.

Back to the contents

USDA Business and Industry guarantees in Wisconsin

New USDA B&I guaranteed loan awards for projects in Wisconsin by fiscal year, and by county, from USAspending; aggregates only.

Few awards, uneven years

USAspending records 21 new USDA Business and Industry guaranteed awards for Wisconsin projects in FY2009, worth $65.0 million net, the high of the table on both measures, and 19 awards for $30.6 million in FY2010. No later year matches either: the most awards since came in FY2021, 15 for $21.4 million, and the largest value in FY2018, $53.7 million on 12 awards. Recent years are thin, 5 awards for $22.9 million in FY2024 and 6 for $29.4 million in FY2023. FY2025 lists 1 new award and FY2022 lists 2, and neither year prints a dollar figure: a year's net value is held back when fewer than 3 Wisconsin awards were touched in it, fresh guarantees counted together with any later action on an existing one, and in both years that combined tally stayed under 3.

A net column that can turn negative

The value column is net of later changes. FY2012 records 11 new awards yet a net value of $-2.6 million, and FY2008 records 0 new awards and $-2.2 million: downward adjustments recorded in those years outweighed any new face value. FY2008's sum is printed at all only because later actions on earlier Wisconsin guarantees lifted the year's count of touched awards to at least 3, so the row reports revisions to old deals rather than any new lending. One year's B&I total in Wisconsin is therefore a weak signal of demand, and a study for a rural project should read the award counts across several years instead.

B&I beside the SBA 504 book

Against SBA lending, B&I in Wisconsin is a channel of few, large guarantees. FY2018's 12 B&I awards for $53.7 million compare with 150 SBA 504 loans for $116.0 million, and FY2024's 5 awards for $22.9 million sit beside 173 SBA 504 loans for $188.3 million. This page's market discussion places much of rural and agricultural Wisconsin in USDA-eligible territory, so a project outside the metros may be weighed for B&I and SBA financing at once.

The B&I study in a thin Wisconsin record

The B&I file answers to 7 CFR Part 5001, a standard that Loan Analytics' 2026 fee survey describes as an enumerated list, longer than the SBA's discretionary one, and a study serving both programs is scoped to the longer list. With no deep run of recent Wisconsin B&I deals to benchmark against, the study carries its evidence from the trade area itself: the operators near the site, the local labor supply and the households or businesses the project will serve.

USDA B&I guaranteed loan awards in Wisconsin by fiscal year
Fiscal yearNew awardsFace value, net
FY20251withheld: fewer than 3 awards
FY20245$22.9 million
FY20236$29.4 million
FY20222withheld: fewer than 3 awards
FY202115$21.4 million
FY202010$15.4 million
FY20198$38.3 million
FY201812$53.7 million
FY20178$28.1 million
FY20166$16.9 million
FY20157$19.1 million
FY20146$32.8 million
FY201310$21.0 million
FY201211$-2.6 million
FY20118$26.0 million
FY201019$30.6 million
FY200921$65.0 million
FY20080$-2.2 million

Source: USAspending.gov records of USDA Business and Industry guaranteed loan awards by project state, face value of the loan net of later changes, as compiled in Loan Analytics' USDA tables; a year's dollars are withheld where fewer than 3 awards were touched that year (new awards and later actions together), so a year can show dollars beside 0, 1 or 2 new awards; FY2026 runs through August 31, 2026; aggregates only, no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Wisconsin by fiscal year", https://www.analytics.loan/wisconsin-feasibility-study-data#usda-usda-by-year.

USDA B&I guaranteed loan awards in Wisconsin by county, FY2015 to FY2026
CountyAwardsFace value
Manitowoc, WI (FIPS 55071)7$25.6 million
Dane, WI (FIPS 55025)5$0
Adams, WI (FIPS 55001)4fewer than 5 awards
Fond Du Lac, WI (FIPS 55039)4fewer than 5 awards
Grant, WI (FIPS 55043)4fewer than 5 awards
Oconto, WI (FIPS 55083)4fewer than 5 awards
Racine, WI (FIPS 55101)4fewer than 5 awards
Sheboygan, WI (FIPS 55117)4fewer than 5 awards
Brown, WI (FIPS 55009)3fewer than 5 awards
Polk, WI (FIPS 55095)3fewer than 5 awards
Portage, WI (FIPS 55097)3fewer than 5 awards
Columbia, WI (FIPS 55021)2fewer than 5 awards
Iowa, WI (FIPS 55049)2fewer than 5 awards
Langlade, WI (FIPS 55067)2fewer than 5 awards
Marathon, WI (FIPS 55073)2fewer than 5 awards
Marinette, WI (FIPS 55075)2fewer than 5 awards
Ozaukee, WI (FIPS 55089)2fewer than 5 awards
Sauk, WI (FIPS 55111)2fewer than 5 awards
Vernon, WI (FIPS 55123)2fewer than 5 awards
Walworth, WI (FIPS 55127)2fewer than 5 awards
Washington, WI (FIPS 55131)2fewer than 5 awards
Ashland, WI (FIPS 55003)1fewer than 5 awards
Barron, WI (FIPS 55005)1fewer than 5 awards
Calumet, WI (FIPS 55015)1fewer than 5 awards
Chippewa, WI (FIPS 55017)1fewer than 5 awards
Dodge, WI (FIPS 55027)1fewer than 5 awards
Green, WI (FIPS 55045)1fewer than 5 awards
Jefferson, WI (FIPS 55055)1fewer than 5 awards
Monroe, WI (FIPS 55081)1fewer than 5 awards
Oneida, WI (FIPS 55085)1fewer than 5 awards
Outagamie, WI (FIPS 55087)1fewer than 5 awards
Pierce, WI (FIPS 55093)1fewer than 5 awards
Rock, WI (FIPS 55105)1fewer than 5 awards
St. Croix, WI (FIPS 55109)1fewer than 5 awards
Waukesha, WI (FIPS 55133)1fewer than 5 awards
Waupaca, WI (FIPS 55135)1fewer than 5 awards

Source: USAspending.gov award records of USDA Business and Industry guarantees (assistance listing 10.768) by place of performance county, face value net, FY2015 through August 31, 2026, aggregated by Loan Analytics; dollars are withheld where fewer than 5 awards stand behind them; no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Wisconsin by county, FY2015 to FY2026", https://www.analytics.loan/wisconsin-feasibility-study-data#usda-usda-by-county.

Back to the contents

Questions buyers ask

Who writes the feasibility study for a Wisconsin SBA loan?

Loan Analytics prepares it, standing apart from both borrower and lender, whether the loan runs through 7(a), 504 or a B&I guarantee, with each Wisconsin report signed by Daniel Smith, MAI. The work starts from the Wisconsin record on this page, 13,157 SBA loans worth $7.19 billion from FY2017 to FY2026, and narrows it to the property being financed: its trade area, its competitors, the ramp the projection assumes and the coverage the loan needs.

Will my Wisconsin lender require a feasibility study before approving the loan?

Often it will. As the market discussion on this page puts it, federal guidance for both SBA and USDA lending calls for an independent study on many new-business, expansion and construction projects, with the lender ordering it during underwriting. The SBA can also ask for one on its own, and the fee survey we published for 2026 lists when: saturation in the subject's industry and location, a concept without local precedent, a property built for one narrow use, a project oversized for the town around it, or an applicant expanding quickly on young debt. In Wisconsin that points first at hotels ($1.4 million median), gas stations ($780,000), car washes ($745,000) and the fast-growing coffee shop count.

How much time should a Wisconsin borrower allow for the study?

The timeline comes in the Loan Analytics scope reply, set for the property and program at hand. By the fee survey we published for 2026, Wisconsin files run longer with multiple sites, ground-up building whose ramp is measured from completion, a franchised concept whose brand-wide results must be checked, a USDA file built to 7 CFR Part 5001, and rural markets thin enough that competitors are checked in person. Wisconsin has many such markets: the Whitewater-Elkhorn (241 loans), Manitowoc (219) and Watertown-Fort Atkinson (152) micro areas hold far fewer comparable SBA files than Milwaukee-Waukesha with 3,857.

Is the study fee something my Wisconsin SBA loan can finance?

Usually, yes. Per the fee survey Loan Analytics ran for 2026, published on this site, the lender commissions the study, like the appraisal, so that it stays independent, while the borrower bears the cost in the sources and uses: a 7(a) loan may spend its proceeds on third-party reports, and a 504 debenture can fund eligible soft costs within what the project costs in total. With 2,186 SBA 504 loans approved for Wisconsin from FY2017 to FY2026, many projects here can carry the fee with the land and building in a 504 budget.

What will a B&I study for a rural Wisconsin project cost?

For B&I work that must satisfy 7 CFR Part 5001, the USDA tier of our published 2026 fee survey runs from $7,500 up to $18,750 and above; a single Wisconsin study meant to satisfy SBA and USDA reviewers alike is quoted against the longer USDA checklist. Wisconsin's B&I awards are few and uneven, 5 in FY2024 for $22.9 million and 6 in FY2023 for $29.4 million, so on a typical guaranteed project here the fee is small beside the loan. The exact fee depends on the scope of the specific project.

What will a Wisconsin lender want from a hotel feasibility study?

Wisconsin hotels and motels hold 254 SBA loans and $429.6 million from FY2017 to FY2026, more dollars than any other tracked class, at a $1.4 million median, 96 of them under SBA 504. The cancellation floor is 11.4%; the charge-off floor of 0.00% is a floor on a book with open loans, not a promise. Hotel establishments rose from 1,097 in 2018 to 1,168 in 2023, so a lender looks for that new supply in the competitive set, demand split by segment for the specific market, whether Milwaukee convention travel, Wisconsin Dells resort trade or seasonal Door County visits, and coverage tested through a weaker occupancy year.

What must a Wisconsin gas station study prove before the lender signs off?

Gas stations and truck stops hold 241 SBA loans and $243.6 million in Wisconsin, third among the tracked classes by dollars, at a $780,000 median, with floors of 11.0% cancelled and 1.5% charged off. Station counts in the industry's larger code fell from 2,338 to 2,271 between 2018 and 2023 while employment rose, so the study must show the inside-sales and food revenue a larger site depends on, the traffic and competitors at the specific corner, and the environmental work the site needs. For a Wisconsin station, our published 2026 fee survey also records that the SBA requires a Phase I for gas stations regardless of loan amount, so that report belongs in the budget from the start.

Where in Wisconsin are SBA loans concentrated by metro area?

Among areas wholly within the state, Milwaukee-Waukesha leads with 3,857 SBA loans and $2.19 billion from FY2017 to FY2026, then Madison (1,680 loans, $930.4 million), Green Bay (728, $391.0 million), Appleton (613, $308.9 million) and Racine-Mount Pleasant (500, $232.4 million). The Minneapolis-St. Paul-Bloomington row, 12,697 loans, is the whole MN-WI metro area and mostly Minnesota lending. Medians run from $187,500 in Racine-Mount Pleasant to $350,000 in Janesville-Beloit, so a study cites its own area's comparables.

Who makes SBA 504 loans in Wisconsin?

This page's class tables name WBD, Inc. as the SBA 504 lender in Wisconsin's largest classes, and across all classes it holds 1,902 loans and $1.69 billion from FY2017 to FY2026, beside 2,186 SBA 504 loans for the state over those years. Racine County Economic Development Corporation, with 185 loans, appears in both restaurant 504 tables, and Twin Cities-Metro Certified Development Company lists 26 Wisconsin loans for $23.4 million. Both the CDC and the first-lien bank read a 504 study, so it must answer each of them.

Are SBA losses in Wisconsin higher or lower than in Illinois, Michigan, Ohio and Indiana?

In the tracked classes Wisconsin's charge-off floor is 2.8%, the lowest in the East North Central division: Indiana prints 3.2%, Michigan 3.3%, Ohio 4.4% and Illinois 5.2%. Inside the state, Racine-Mount Pleasant (5.9%) and Madison (3.6%) print higher floors than Appleton (1.8%) or Milwaukee-Waukesha (2.8%), and assisted living (5.5%) and full-service restaurants (5.2%) lead the classes. Every rate is a floor, because open loans carry no reported outcome, and a Wisconsin lender expects the downside case to respect the state's own record.

Which questions does a lender put to a Wisconsin restaurant project?

Restaurants are Wisconsin's largest SBA classes: 651 full-service loans at a $290,000 median and 397 limited-service loans at $304,000. The full-service class prints a low cancellation floor, 7.9%, but a high charge-off floor, 5.2%, and its industry shed employees between 2018 and 2023, so a lender asks whether the subject can staff and sustain the operation well after opening. Limited-service projects lose more approvals, a 13.9% cancellation floor, so the first question there is whether the deal will close as approved.

Back to the contents

Wisconsin feasibility study consultant: request a scope

To open a Wisconsin study, send the Request Scope & Timeline form that follows, or email Info@analytics.loan, with a short brief: the kind of property, its county or the metro or micro area this page lists it under, which program the lender is using, whether SBA 7(a), the 504 program or USDA B&I, and the rough amount. If you know the desk that will read the study, a WBD, Inc. 504 file, a 7(a) loan at Byline Bank or Nicolet National Bank, a credit union such as Summit CU or a B&I application, tell us, since each of those readers presses on a different part of the case.

We reply with scope and timeline for that property. A Milwaukee hotel, a Fox Valley gas station, a Janesville-Beloit project near the state's highest metro median and a Northwoods campground under B&I rest on different parts of the Wisconsin record above, and the reply names the parts the study will use.

Request Scope & Timeline

Corrections

Figures on this page were checked against SBA's and USAspending's own records and corrected where they differed. Each corrected figure is marked in the text; what it counts and where it comes from:

  1. $527.0 million: 7(a) gross dollars, Wisconsin, 2025; calendar 2025, project state. Source: SBA loan data as of 2026-09-30.
  2. 1,003: 7(a) approvals, Wisconsin, 2025; calendar 2025, project state. Source: SBA loan data as of 2026-09-30.
  3. 84,840: 7(a) plus 504 gross approvals FY2025, cancellations included. Source: SBA loan data as of 2026-09-30.
  4. $45.09 billion: gross SBA 7(a) loan dollars plus 504 debenture dollars approved in FY2025, cancelled approvals included; the highest of any fiscal year in the SBA loan data, which begin in FY1991. Source: SBA loan data as of 2026-09-30.

Start with the data.

Contact Us