State Feasibility Study Data

Illinois Feasibility Study Consultants

Illinois is the fifth-largest economy in the country and one of the six largest states for SBA lending, and a feasibility study in Illinois now sits at the center of how lenders move SBA and USDA projects from application to approval. The state operates a $1.24 trillion economy anchored by Chicago, a global financial center and the largest rail hub in North America. Its population has grown for three consecutive years after a long decline, though only because of international migration. Its commercial real estate markets range from some of the tightest industrial and apartment markets in the country to a downtown office market still near record vacancy. Loan Analytics publishes the lending, demographic and commercial real estate data behind those numbers. We prepare independent feasibility studies for SBA 7(a), SBA 504 and USDA-financed projects across Illinois when a lender requires the full report. This page lays out the current Illinois market and explains what a feasibility study consultant actually delivers for a credit file.
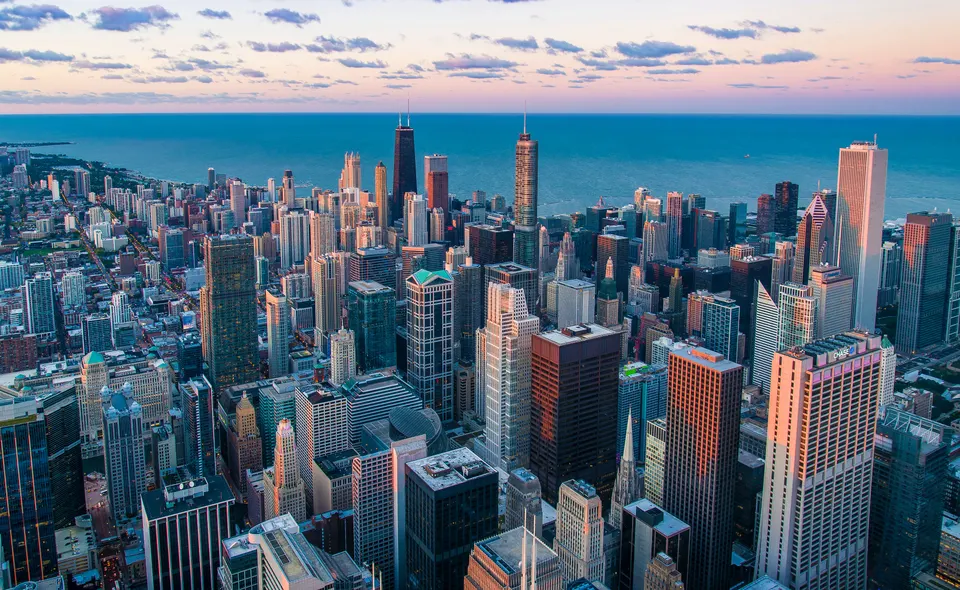
Illinois feasibility study consultant

Loan Analytics prepares the feasibility study an Illinois lender places in the credit file behind a 7(a), 504 or USDA B&I request, written for the credit officer who has to approve it. From FY2017 to FY2026 SBA approved 22,837 loans for $12.89 billion in Illinois, more dollars than in any other East North Central state, and the classes ranked on this page hold 6,489 of those loans and $4.91 billion. Restaurants, child care centers and fitness centers lead by count; hotels are the largest checks, 406 loans for $984.7 million at a $2.3 million median.

The study starts from the loss record the lender already holds. Illinois's charge-off floor in the tracked classes, 5.2% of FY2017 to FY2021 disbursements, is the highest in its division, and the classes spread wide around it: grocery stores at 13.2% and fitness centers at 9.7%, hotels at 2.2% and child care centers at 1.8%. Gas stations and truck stops carry a 20.9% cancellation floor, second only to nonresidential lessors at 28.6%. Against that record the study defines the trade area from the site outward, names and verifies the competing operators, builds demand from the county's households, income and employers, tests the budget against current Illinois costs, runs the projections through the downside a committee will press, and closes with a signed opinion on whether the project carries the debt requested.

Send the asset class, the Illinois county and the program, and Loan Analytics answers with a scope and timeline built around this page's figures for that class and place, so the lender sees which tests the study will run before work begins.

Request Scope & Timeline

Image by Pedro Lastra

SBA Lending in Illinois: The Current Picture

Illinois is one of the highest-volume SBA markets in the nation. The SBA’s own analysis ranked the state sixth by lending dollars at its fiscal 2025 pace, behind California, Texas, Florida, New York and Georgia. Illinois lenders approved about 2,835 SBA 7(a) loans worth $1.31 billion in fiscal 2025, supporting about 29,000 jobs, plus 303 504 loans worth $321 million. The average 7(a) loan of about $461,000 sat near the national figure, at a slightly lower average interest rate. Activity is concentrated in the Chicago metro, where 7(a) lending rose from about 1,750 loans in fiscal 2023 to more than 2,500 in fiscal 2025. The state’s single busiest SBA industry is long-distance trucking, a reflection of Chicago’s role in national freight. 299 Corrected lenders have made Illinois 7(a) loans over the past five years. Huntington, Northeast Bank and U.S. Bank made the most in the Chicago metro in fiscal 2025. Chicago-based Byline Bank was the tenth-largest 7(a) lender in the country by dollars and the SBA’s Illinois 7(a) Lender of the Year for the seventeenth straight year. Small Business Growth Corporation and SomerCor lead the state’s 504 lending.

The credit record shows how much property type and loan structure matter. Across ten Chicago-area asset classes, 504 loans have charged off at 4.3 percent, against 10.4 percent for 7(a) loans. Within 7(a), hotels charged off at 3.5 percent and child care centers at 3.8 percent, while restaurants reached 12.3 percent and fitness centers 13.8 percent. Nationally, SBA approvals fell in fiscal 2026 to 56,130 7(a) loans worth $32.4 billion and 6,075 504 loans worth $7.1 billion, after a 43-day shutdown froze both programs. SOP 50 10 8.1, effective 1 October 2026, now requires 1.25x debt service coverage on historical earnings for business acquisitions, an independent business valuation on every change of ownership, and a Quality of Earnings report at $3 million and above. At the same time, the combined 7(a) and 504 limit per borrower doubled to $10 million in July 2026.

The practical point for a borrower or lender searching for a feasibility study consultant in Illinois is that the document is not a box-checking exercise. Startup projects, change-of-ownership transactions where the buyer has no operating history at the site, and ground-up construction with no existing revenue to underwrite all need it. In each case, the feasibility study is the analysis that lets a credit committee size the deal with confidence. For projects in the agricultural and rural parts of the state, USDA Business and Industry loans under $5 million carry an 85 percent guarantee in fiscal 2026. The program’s rural test excludes larger cities and their urbanized areas, but many communities in outer metro counties such as Grundy, Kendall, DeKalb, McHenry and Kane still qualify. However, the administration’s fiscal 2027 budget request proposes eliminating appropriations for the program, so any capital stack that depends on B&I should carry a fallback. An Illinois feasibility study company that understands both the SBA standard operating procedures and the local submarket is doing two jobs at once: satisfying a federal documentation requirement and giving the lender a defensible basis for its credit decision.

Where Illinois Is Growing: Population and County Demographics

Illinois is the sixth-most-populous state at 12,719,141 residents as of July 2025, and it has grown for three consecutive years after roughly a decade of losses. The latest gain was modest, 16,108 residents, and its source is the single most important fact for any demand analysis. International migration added 44,752 people, while 40,017 more residents left for other states than arrived, the third-largest domestic loss in the country after California and New York. The state remains about 102,600 residents below its 2020 level. The Census Bureau expects international migration nationally to fall by roughly three-quarters from its 2024 peak, so the next estimate could show Illinois declining again. A demand case should not assume the recent growth streak continues.

The rebound is centered on Chicago and Cook County, and it is slowing. Cook County, the second-most-populous county in the nation, holds 5,194,625 residents. It gained 5,834 in the latest year, down from about 46,000 the year before, and remains 1.6 percent below its 2020 level. The City of Chicago added 5,253 residents to reach 2,731,585, after a gain of more than 22,000 a year earlier that ranked seventh nationally. The broader Chicago metro, including northwest Indiana, holds about 9.4 million people. The collar counties tell a varied story: DuPage has been essentially flat since 2020, while Kane and Lake counties hold about 526,000 and 719,000 residents respectively. Downstate, only a handful of Illinois counties have grown since 2020, and the Decatur, Peoria and Kankakee metros all lost population. Chicago-area unemployment has risen to 5.1 percent. A project that pencils cleanly in a stable collar county or a rebounding Chicago neighborhood can face very different demand in a declining downstate county, and the Illinois label alone tells a lender almost nothing. The work is in the trade area.

Illinois Commercial Real Estate: The Five Major Markets

An Illinois feasibility study lives or dies on which asset class is in question, because the five major commercial real estate sectors, concentrated in the Chicago metro, are moving in distinctly different directions.

Industrial is a genuine strength, built on Chicago’s position as the largest rail hub in North America and one of the country’s premier logistics markets. Metro vacancy runs between 4.7 and 5.9 percent in the third quarter of 2026 across five brokerages, against 6.8 percent nationally. Year-to-date absorption is between 7.5 and 12.4 million square feet. Demand is concentrating along the Interstate 80 corridor around Joliet, which accounted for about half of CBRE’s year-to-date absorption. Cushman & Wakefield reports asking rents there up 33 percent in a year, while other brokers measure gains closer to 7 percent. The pipeline of 13 to 18 million square feet is about half speculative, and it includes a 1.5-million-square-foot build-to-suit for Kimberly-Clark. Multifamily is a supply-constrained outperformer. Apartments under construction equal only about 1.7 percent of inventory, the smallest pipeline of any major U.S. market. Vacancy runs between 3.4 and 5.1 percent depending on the source, and rents reached records near $2,100 to $2,200, growing about 3 percent, the third-fastest among the top 30 markets.

The remaining sectors complete the spread. Office is the most divided. Downtown Chicago direct vacancy stands at 25.0 percent, against 13.8 percent before the pandemic. Total vacancy posted its first decline in fifteen quarters in mid-2026, but third-quarter absorption turned negative again. Trophy buildings continue to gain tenants, Fulton Market is the tightest downtown submarket at about 18 percent, and more than half of recent downtown office sales are slated for redevelopment or conversion. Suburban vacancy rose to 24.1 percent. Chicago is also a significant data center market, with 2.2 percent vacancy on about 910 megawatts of wholesale capacity and record rents. Power, however, is the binding constraint. ComEd has pushed some power deliveries to 2032 or later and requires ten-year letters of credit for projects of 50 megawatts or more. By JLL’s count, at least $200 billion in data center projects planned for Illinois went to Wisconsin, Indiana and other states instead. Retail is tight at 5.0 percent vacancy, with record asking rents and almost no new construction. Hospitality is anchored by McCormick Place and O’Hare. During major trade shows in the fall of 2026, Chicago led the 25 largest U.S. markets in revenue-per-room growth, with gains near 40 percent. Those weeks are driven by the convention calendar and should not be annualized. That divergence between sectors is precisely the question a lender asks a feasibility study to resolve.

Feasibility Studies by Asset Class in Illinois

Commercial financing in Illinois divides by property type, and each asset class a feasibility study covers turns on different questions. A hotel feasibility study in Illinois depends on demand segmentation across business, group and leisure travel in a specific submarket, set against existing and planned room supply. In downtown Chicago, it must model the McCormick Place show rotation rather than a single strong year. A gas station and convenience store feasibility study hinges on traffic counts, fuel volumes, the competitive set within the trade area, and the inside sales and food service that increasingly drive c-store margins. It also has to account for the higher loss rates this category has carried in SBA lending. A car wash feasibility study turns on rooftops, daily traffic and the membership model that now defines express-tunnel economics.

An RV park or campground feasibility study weighs Illinois’s lake, river and downstate tourism against seasonality and the conversion of transient demand into longer stays. A multifamily feasibility study tests trade-area household formation and absorption against the apartment pipeline in that specific submarket, a question of real consequence in a metro as supply-constrained as Chicago. A self-storage feasibility study measures square feet per capita against current and planned inventory in the immediate radius. An assisted living or senior housing feasibility study models the age-qualified population, penetration rates and acuity mix. A restaurant, fitness or franchise feasibility study weighs daypart demand and local competitive density against the operator’s unit economics, and it deserves the hardest stress testing, given the loss record of those categories. An industrial or warehouse feasibility study tests logistics access, clear height, power and the absorption of comparable space nearby, a matter of central importance in a state at the heart of North American rail and freight. Each of these is a distinct analysis with its own demand drivers. A state as varied as Chicago, the collar counties, Rockford, Peoria and the downstate farm belt cannot be served by a generic template that simply swaps in the word Illinois.

Construction Costs: The Illinois Picture

Hard costs feed straight into total project cost, loan sizing and the debt-service coverage a lender stress-tests, so a current read on construction inflation belongs in every Illinois feasibility study. Illinois is one of the few markets where a precise local index is available, because Chicago is one of only eight metros tracked directly by the Mortenson Construction Cost Index. Mortenson’s release for the third quarter of 2026 put Chicago costs up 2.20 percent for the quarter, faster than the national 1.58 percent, and 5.39 percent year over year. Mortenson attributes the jump to annual union contract resets and competition for electricians from data center projects. Electrical, metals and structural steel led the increases, and 2026 tariff changes had not yet been fully priced into contractor bids. A Chicago budget should carry escalation of at least 5.5 percent a year, with separate contingency for electrical and metals.

Several Illinois-specific operating costs sit alongside the construction index, and they can decide feasibility. Property taxes come first. Cook County assesses most commercial property at 25 percent of market value, against 10 percent for homes, and reassesses on a three-year cycle. The City of Chicago’s next reassessment comes in 2027, so any Chicago pro forma should model a possible step-up and the appeal path. Power costs have also risen sharply. In northern Illinois, PJM capacity prices for 2027 through 2029 have cleared between $325 and $333 per megawatt-day, against $28.92 in 2024–25. That leaves ComEd customers paying about 50 percent more for power than two years ago. State regulators project a capacity shortfall in the region beginning in 2029. Much of Chicago’s building stock is old, so renovation and adaptive reuse projects carry structural and code costs that a national average will not reflect. A market with these dynamics demands a cost basis built from current local conditions, live bids, current tax assessments and current power pricing.

What an Illinois Feasibility Study Consultant Delivers

Read the lending, demographic and market data together and the assignment becomes concrete. Illinois sends one of the largest volumes of SBA projects in the country to credit committees every year, with loss rates that vary widely by property type, and the new SBA rules now demand more evidence for each one. A population held up only by immigration, with Chicago’s rebound slowing and downstate counties declining, means a demand case has to be built at the submarket level. Five commercial real estate sectors pointing in different directions, with industrial and apartments tight and downtown office still near record vacancy, mean asset selection drives the outcome. Rising labor, power and property-tax costs mean a budget assembled a year ago is already stale.

A feasibility study consultant brings those threads together into a single third-party document written for the lender’s file. What distinguishes a credible Illinois feasibility study company is independence and evidence. The consultant is independent of both borrower and lender, and the conclusions rest on verifiable trade-area demographics, a documented competitive supply analysis, demand and absorption modeling, financial projections, and sensitivity testing organized around what a credit committee actually reviews. SBA and USDA guidelines call for exactly this kind of independent study on many startup, expansion and new-construction projects, and the lender typically orders it once the deal is in underwriting.

Several policy decisions now shape Chicago-area feasibility. A December 2025 state law created the Northern Illinois Transit Authority with about $1.5 billion a year in new funding. That averted service cuts on the CTA, Metra and Pace, at the cost of a higher regional sales tax. Chicago’s 2026 budget raised the city’s lease and cloud computing tax from 11 to 14 percent and added several consumer taxes, while rejecting a proposed per-employee head tax. On the South Side, the Illinois Quantum and Microelectronics Park is rising on the 128-acre former U.S. Steel site, backed by $500 million in state capital. Its anchor tenant, PsiQuantum, is expected to complete its facility in 2027, alongside IBM and a federal research program. The Chicago Bears’ stadium plans remain unresolved, with no deal enacted as of November 2026. A credible study treats each of these as a variable, not a background assumption.

The state’s investment profile sharpens the need for current data. Illinois’s economy produced about $1.24 trillion in 2025, fifth among the states, and grew at a 2.1 percent annual rate in the second quarter of 2026. It is one of the most diversified economies in the country. The Chicago metro anchors a global hub for futures and derivatives trading and a deep base of corporate headquarters. Beyond it, a major manufacturing base, one of the nation’s largest agricultural economies, health care, and the rail and logistics network that runs through Chicago round out the picture. Each of those forces reshapes trade-area demand, labor demand and absorption in the markets around it. None of it shows up in a generic template, which is the entire reason a project-specific study exists.

Work With an Illinois Feasibility Study Consultant

Loan Analytics prepares independent feasibility studies for SBA 7(a), SBA 504 and USDA-financed projects across Illinois, built on the same data published on this page and extended to the subject property. The study arrives as a third-party document, written for the lender’s file. It covers trade-area demographics, competitive supply, demand and absorption, property-tax and power costs where relevant, financial projections, and sensitivity testing. To scope one, use the form below or write to Info@analytics.loan. Include the property type, the county and the loan program, and we come back with scope and timeline.

Request Scope & Timeline

SBA loan record in Illinois, FY2017 to FY2026

SBA 7(a) and 504 loans approved for projects in Illinois across the asset classes Loan Analytics tracks, from SBA's own loan-level files.

LoansDollars
Both programs6,489$4.91 billion
SBA 7(a)5,510$3.99 billion
SBA 504979$917.4 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Illinois, FY2017 to FY2026, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Cancelled after approval, FY2017 to FY2024 approvals (a floor)13.5%
Charged off to date, FY2017 to FY2021 disbursed loans (a floor)5.2%
Charged off within five years of approval2.9%

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Illinois, FY2017 to FY2026, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Both rates are floors: SBA withholds the status of open loans. A rate needs at least 30 loans in its cohort.

SBA loans approved in Illinois by fiscal year, in the asset classes with 10 or more loans and approvals in 5 or more fiscal years

02004006008001000FY2017FY2018FY2019FY2020FY2021FY2022FY2023FY2024FY2025FY2026Loans, FY2017: 641Loans, FY2018: 646Loans, FY2019: 558Loans, FY2020: 536Loans, FY2021: 631Loans, FY2022: 650Loans, FY2023: 623Loans, FY2024: 702Loans, FY2025: 875Loans, FY2026: 591
Fiscal yearLoansDollars
FY2017641$415.0 million
FY2018646$412.0 million
FY2019558$418.2 million
FY2020536$424.1 million
FY2021631$513.1 million
FY2022650$543.0 million
FY2023623$468.5 million
FY2024702$579.6 million
FY2025875$637.9 million
FY2026591$476.5 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Illinois, FY2017 to FY2026, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Asset classes in Illinois, ranked by loans

Asset classLoansDollars
Full-service restaurant1,317$759.6 million
Limited-service restaurant796$425.5 million
Child care center481$349.0 million
Fitness center440$219.6 million
Automotive mechanical repair (car and truck)428$184.1 million
Hotel and motel406$984.7 million
Beauty salon327$75.3 million
Gas station and truck stop304$357.7 million
Liquor store275$214.8 million
Coffee shop and snack bar256$90.0 million
Dental office234$130.3 million
Grocery store174$161.3 million
Medical office (physicians)164$85.1 million
Car wash127$185.1 million
Beverage manufacturing (breweries, wineries, distilleries)113$83.5 million
Rehabilitation and therapy clinic97$36.0 million
Veterinary clinic81$72.2 million
Caterers (includes banquet halls with catering staff)80$69.6 million
Self storage79$125.4 million
Nonresidential lessor (flex, office and retail investor buildings)56$57.1 million
Data center39$21.2 million
Warehouse and distribution32$34.1 million
School (elementary and secondary, including charter)30$36.4 million
Assisted living (without nursing care)28$53.4 million
Behavioral health and addiction treatment24$14.0 million
Marina15$12.6 million
Manufactured housing community (lessors of other real estate)13$13.1 million
Diagnostic imaging center13$8.0 million
Skilled nursing12$24.9 million
Life science lab (research and development)12$4.1 million
Urgent care and ambulatory surgery9$7.1 million
RV park and campground8$4.9 million
Hospital8$4.1 million
Multifamily (lessors of residential buildings)5$2.2 million
Continuing care retirement community4fewer than five loans
Parking lot and garage2fewer than five loans

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Illinois, FY2017 to FY2026, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Most active SBA lenders in Illinois's largest classes

Full-service restaurant, SBA 504: lenders by loans approved
LenderLoans
Small Business Growth Corporation123
SomerCor 504, Inc.79
Rockford Local Development Corporation5

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Full-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
The Huntington National Bank293
Byline Bank98
U.S. Bank, National Association54
Newtek Bank, National Association52
Northeast Bank41

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Limited-service restaurant, SBA 504: lenders by loans approved
LenderLoans
SomerCor 504, Inc.45
Small Business Growth Corporation38
Rockford Local Development Corporation9
Wessex 504 Corporation5

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Limited-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
The Huntington National Bank156
Byline Bank90
Village Bank and Trust, National Association35
U.S. Bank, National Association28
Midland States Bank19

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Child care center, SBA 504: lenders by loans approved
LenderLoans
SomerCor 504, Inc.54
Small Business Growth Corporation48

Download this table (CSV). Cite as: Loan Analytics, Child care center, SBA 504: lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Child care center, SBA 7(a): lenders by loans approved
LenderLoans
The Huntington National Bank50
U.S. Bank, National Association27
Byline Bank26
JPMorgan Chase Bank, National Association23
Live Oak Banking Company15

Download this table (CSV). Cite as: Loan Analytics, Child care center, SBA 7(a): lenders by loans approved, https://www.analytics.loan/illinois-feasibility-study-data#state-record.

Feasibility study data by asset class in Illinois

Feasibility study data by asset class and SBA program in Illinois

Feasibility study data by metro area in Illinois

Source: U.S. Small Business Administration, 7(a) and 504 loan-level FOIA files (data.sba.gov), as of 2026-09-30. Totals add the state's cells across the tracked asset classes; they are not all SBA lending in Illinois.

Feasibility study questions for Illinois

How many SBA loans have gone to Illinois projects in the asset classes Loan Analytics tracks?

Illinois has 6,489 SBA loans for $4.91 billion in the classes this site tracks, FY2017 to FY2026; other SBA borrowers in the state are not in the figure. The 7(a) program accounts for 5,510 loans and $3.99 billion and the 504 program for 979 loans and $917.4 million. FY2025 was the strongest year, 875 loans and $637.9 million, and FY2020 the weakest at 536 loans.

Which asset classes receive the most SBA loans in Illinois?

Full-service restaurants lead Illinois with 1,317 loans and $759.6 million, followed by limited-service restaurants at 796 and child care centers at 481 ($349.0 million). Fitness centers (440) and automotive mechanical repair (428) come next. Hotels and motels, sixth by count with 406 loans, have the largest dollar total, $984.7 million, and gas stations and truck stops add 304 loans for $357.7 million.

How often are SBA loans in Illinois cancelled or charged off?

Illinois sits toward the high end of the set: its cancellation floor is 13.5% of FY2017 to FY2024 approvals, its charge-off-to-date floor is 5.2% of FY2017 to FY2021 disbursements, and its five-year charge-off floor is 2.9%. Each is a minimum on the tracked classes, which a lender should read as a cohort benchmark, not a forecast for one project.

Which lenders make the most SBA loans in Illinois?

The Huntington National Bank leads Illinois 7(a) restaurant lending by a wide margin: 293 full-service and 156 limited-service loans, with Byline Bank second at 98 and 90. It also leads child care 7(a) with 50. On the 504 side, Small Business Growth Corporation made 123 full-service restaurant loans and SomerCor 504, Inc. 79, while SomerCor led limited-service restaurants (45) and child care centers (54).

Which Illinois programs can support a project financed with an SBA or USDA loan?

The Illinois Department of Commerce and Economic Opportunity lists low-interest loan programs for businesses. Advantage Illinois provides low-interest loans to small businesses for start-up costs, working capital, equipment and inventory, and the Cannabis Loan Program supports Social Equity Applicants. The department also points owners to the SBA's own programs. A study for an Illinois project should state whether an Advantage Illinois loan sits in the capital stack and on what terms.

Source: Low Interest Loan Programs, Illinois Department of Commerce and Economic Opportunity

Which state permits and approvals should a feasibility study for a project in Illinois account for?

Illinois EPA organizes business permits by air quality, water quality, and land pollution and waste disposal, with an online permit portal, and it offers a guide titled Does My Business Need a Pollution Control Permit. Small businesses can use the Small Business Environmental Assistance Program, delivered by the Department of Commerce, for free confidential help understanding their environmental obligations. Local zoning and building approvals are separate and belong in the study's schedule.

Source: Small Business, Illinois Environmental Protection Agency

What does a feasibility study cost?

Before comparing prices, Loan Analytics' 2026 cost guide suggests four checks on any quote: which program's standard the study is written to, whether the author is independent and signs an opinion, whether competitors are verified directly, and whether the turnaround fits the loan timeline. Its published bands price single-site studies from $5,000 to $12,500 and complex ones from $10,000 to $25,000, and a sound $9,000 quote beats a weak one at $5,000.

Source: SBA Feasibility Study Cost in 2026: Price Bands by Asset Class, and the Fee as Basis Points of the Loan, Loan Analytics

What does a feasibility study for a project in Illinois test first?

Illinois lending runs heavily to restaurants and child care (1,317 full-service, 796 limited-service and 481 child care loans), so a study here usually begins by defining the trade area and quantifying demand for that segment: households and income for child care, drive-time draw for restaurants. Hotels and gas stations, with $984.7 million and $357.7 million, then call for the site, technical and downside stages, including liquidation value for these special-purpose properties.

Source: How a Feasibility Study Is Done: The Loan Analytics Methodology, Loan Analytics

Worked examples

SBA lending in Illinois, FY1991 to FY2026

Every SBA 7(a) and 504 loan approved for a project in Illinois since FY1991, by fiscal year, from SBA's own loan files.

The count peak and the dollar peak

Illinois set its 7(a) count record in FY2007, 4,236 loans for $436.1 million, and its dollar record in FY2025, 2,835 loans for $1.31 billion, the most loans in any year since FY2007. Fewer approvals now carry far larger balances, so an Illinois committee today decides on a much larger exposure per borrower than in the mid-2000s and expects projections, sensitivity cases and a debt service test sized to it.

The FY2009 stall was a 7(a) event

7(a) approvals fell from 4,236 in FY2007 to 2,810 in FY2008 and 1,267 in FY2009, with dollars down to $249.9 million, while 504 held at 351 loans in FY2008 and 322 in FY2009, for $218.1 million and $208.7 million. A project with a later phase, a planned refinance or a long ramp should show its debt still serviced if Illinois credit tightens that way again, rather than assume the latest year's volume continues.

504 has given ground since FY2022

The 504 program peaked in FY2012 at 544 loans for $443.0 million and came close on dollars in FY2022, with 468 loans and $430.5 million. Then the programs diverged: 504 fell to 297 in FY2023 and 268 in FY2024 while 7(a) rose from 1,661 to 1,956 and then 2,469, and FY2025's 303 504 loans for $321.3 million stayed well below FY2022. For an owner-occupied building the study should be written to the program the lender chose, since the sources and uses, the collateral and the debt service differ between them.

Years that distort an average

FY2026 brought 1,746 7(a) loans for $1.06 billion and 267 504 loans for $281.4 million: below FY2025 on every measure, yet the fourth-largest 7(a) dollar year on record after FY2025, FY2024 and FY2021. FY2020 cut 7(a) approvals to 1,449, the fewest since FY2009, while dollars rose to $869.1 million from $830.3 million. Across the whole record Illinois has approved 65,327 7(a) loans for $20.10 billion and 9,793 504 loans for $6.74 billion, and the FY2017 to FY2026 decade alone holds $10.04 billion and $2.85 billion of those dollars. A study that benchmarks against this record should name its window.

SBA 7(a) and 504 loans approved in Illinois by fiscal year
Fiscal yearSBA 7(a) loansSBA 7(a) dollarsSBA 504 loansSBA 504 dollars
FY1991566$130.0 million13$4.9 million
FY1992618$164.6 million20$7.0 million
FY1993692$201.7 million20$8.9 million
FY1994988$237.8 million66$29.1 million
FY19952,183$277.7 million107$46.9 million
FY19961,648$222.3 million200$84.8 million
FY19971,370$230.3 million107$46.5 million
FY19981,119$224.4 million134$52.9 million
FY19991,219$253.4 million176$75.0 million
FY20001,129$240.1 million202$88.7 million
FY20011,063$225.0 million200$84.1 million
FY20021,229$286.9 million238$108.4 million
FY20031,608$306.1 million295$148.7 million
FY20042,068$341.9 million331$163.7 million
FY20053,608$455.5 million349$208.6 million
FY20064,049$463.6 million337$224.3 million
FY20074,236$436.1 million418$247.7 million
FY20082,810$409.7 million351$218.1 million
FY20091,267$249.9 million322$208.7 million
FY20101,677$496.7 million375$215.0 million
FY20111,897$728.6 million412$273.8 million
FY20121,559$569.7 million544$443.0 million
FY20131,508$666.0 million387$268.7 million
FY20141,686$675.9 million315$215.2 million
FY20152,061$816.0 million300$192.7 million
FY20161,883$745.1 million323$221.8 million
FY20171,915$853.8 million331$251.5 million
FY20182,035$907.0 million297$196.7 million
FY20191,788$830.3 million265$205.7 million
FY20201,449$869.1 million328$226.2 million
FY20211,732$1.13 billion427$346.8 million
FY20221,661$933.7 million468$430.5 million
FY20231,956$977.6 million297$301.0 million
FY20242,469$1.17 billion268$290.0 million
FY20252,835$1.31 billion303$321.3 million
FY20261,746$1.06 billion267$281.4 million
FY1991 to FY202665,327$20.10 billion9,793$6.74 billion
FY2017 to FY202619,586$10.04 billion3,251$2.85 billion

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Download this table (CSV). Cite as: Loan Analytics, "SBA 7(a) and 504 loans approved in Illinois by fiscal year", https://www.analytics.loan/illinois-feasibility-study-data#sba-record-sba-by-year.

Back to the contents

Asset classes financed in Illinois, ranked

Each asset class Loan Analytics tracks, ranked by SBA loans approved in Illinois from FY2017 to FY2026, with loan size, program split and the cohort floors where at least 30 loans support them.

Ranked by count, ranked by dollars

Counted by loans, Illinois SBA lending is led by restaurants and child care; counted by dollars, by hotels. Hotels and motels rank sixth by count but first by dollars, $984.7 million against $759.6 million for full-service restaurants, on the largest median in the table, $2.3 million. Car washes, fourteenth by count with 127 loans, have a $1.0 million median and gas stations and truck stops $967,500, while beauty salons, seventh with 327 loans, have the smallest, $100,000. The dollar exposure sits in classes lenders approve less often, so each hotel, car wash or fuel study carries more of the book than its count suggests.

Charge-off floors, highest to lowest

Grocery stores carry the highest charge-off floor in the Illinois table, 13.2%, followed by fitness centers at 9.7%, beverage manufacturers at 8.6% and full-service restaurants at 8.0%. Child care centers (1.8%), liquor stores (1.7%) and hotels (2.2%) sit low, and dental offices, car washes, veterinary clinics, self storage and nonresidential lessors show 0.00% so far. These floors describe cohorts, not one borrower, but a grocery or fitness study here is read against them and must show the cushion its cohort lacked: payroll and rent stress, a competitor opening nearby, and baskets or memberships below plan, each carried through to debt service.

Cancellation, the risk before funding

A cancelled approval never went forward as approved, and cancellation ranks the Illinois classes differently. Nonresidential lessors reach 28.6%, gas stations and truck stops 20.9%, veterinary clinics 20.3% and automotive repair 18.3%; hotels (8.1%) and car washes (8.2%) are lowest. Grocery is high on both measures, 12.9% cancelled and 13.2% charged off, while fuel pairs heavy cancellation with a 6.9% charge-off floor, so much of its risk shows up before funding. An Illinois fuel-site study should therefore clear what could derail closing, namely the environmental record, access and supply terms, before the lender commits.

How the program split shapes the study

Full-service restaurants hold the most 504 loans, 214, ahead of child care centers (109), limited-service restaurants (100), automotive repair (85) and hotels (81). No class at least as large as car washes leans on 504 as hard as they do, 44 of 127 loans; self storage, a smaller class, splits 51 and 28. Liquor stores sit at the other pole, 271 of 275 loans through 7(a). A 504 study is read beside an appraisal of land and building, so car wash and self storage studies should carry a reasoned stabilised value, while a liquor store study rests on cash flow and the operator's record.

Classes with no state rate

Data centers (39 loans), warehouse and distribution (32), schools (30) and assisted living (28) print counts and medians but no floors, caterers print a 14.3% cancellation floor and no charge-off rate, and the classes from behavioral health to parking are too thin for a median. An assisted living project at the $1.1 million median or a school at $924,500 reaches the lender with no Illinois loss benchmark, so the study supplies the evidence, from licensed capacity and private-pay depth to enrolment, and says plainly that no state rate exists.

SBA loans in Illinois by asset class, FY2017 to FY2026
Asset classLoansDollarsMedian loanSBA 7(a) loansSBA 504 loansCancelled (floor)Charged off (floor)
Full-service restaurant1,317$759.6 million$304,0001,10321414.7%8.0%
Limited-service restaurant796$425.5 million$347,75069610011.9%5.9%
Child care center481$349.0 million$370,00037210913.1%1.8%
Fitness center440$219.6 million$294,5003924811.9%9.7%
Automotive mechanical repair (car and truck)428$184.1 million$251,5003438518.3%3.9%
Hotel and motel406$984.7 million$2.3 million325818.1%2.2%
Beauty salon327$75.3 million$100,0003002710.2%4.8%
Gas station and truck stop304$357.7 million$967,5002812320.9%6.9%
Liquor store275$214.8 million$454,000271413.6%1.7%
Coffee shop and snack bar256$90.0 million$232,000239178.4%5.5%
Dental office234$130.3 million$315,0001983611.9%0.00%
Grocery store174$161.3 million$460,0001542012.9%13.2%
Medical office (physicians)164$85.1 million$276,9501402413.6%2.7%
Car wash127$185.1 million$1.0 million83448.2%0.00%
Beverage manufacturing (breweries, wineries, distilleries)113$83.5 million$439,400852815.3%8.6%
Rehabilitation and therapy clinic97$36.0 million$180,000781912.8%2.9%
Veterinary clinic81$72.2 million$451,700681320.3%0.00%
Caterers (includes banquet halls with catering staff)80$69.6 million$420,000701014.3%not reported: fewer than 30 loans in the cohort
Self storage79$125.4 million$861,000512816.4%0.00%
Nonresidential lessor (flex, office and retail investor buildings)56$57.1 million$481,80055128.6%0.00%
Data center39$21.2 million$200,000345not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Warehouse and distribution32$34.1 million$539,050239not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
School (elementary and secondary, including charter)30$36.4 million$924,5001713not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Assisted living (without nursing care)28$53.4 million$1.1 million244not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Behavioral health and addiction treatment24$14.0 milliontoo few loans for these measures
Marina15$12.6 milliontoo few loans for these measures
Manufactured housing community (lessors of other real estate)13$13.1 milliontoo few loans for these measures
Diagnostic imaging center13$8.0 milliontoo few loans for these measures
Skilled nursing12$24.9 milliontoo few loans for these measures
Life science lab (research and development)12$4.1 milliontoo few loans for these measures
Urgent care and ambulatory surgery9$7.1 milliontoo few loans for these measures
RV park and campground8$4.9 milliontoo few loans for these measures
Hospital8$4.1 milliontoo few loans for these measures
Multifamily (lessors of residential buildings)5$2.2 milliontoo few loans for these measures
Continuing care retirement community4fewer than five loanstoo few loans for these measures
Parking lot and garage2fewer than five loanstoo few loans for these measures

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA loans in Illinois by asset class, FY2017 to FY2026", https://www.analytics.loan/illinois-feasibility-study-data#asset-classes-classes.

Back to the contents

Metro and micro areas in Illinois

SBA lending in the metropolitan and micropolitan areas that reach into Illinois, ranked by loans: every SBA 7(a) and 504 approval in each area, all industries together, not only the asset classes Loan Analytics tracks.

Chicago, St. Louis and the rest

The Chicago-Naperville-Elgin metro area recorded 20,063 SBA loans for $11.17 billion from FY2017 to FY2026; St. Louis, a distant second, 4,471 for $2.55 billion; Rockford, third, 481. Both large totals include counties in Indiana or Missouri, so neither is an Illinois-only figure. A Chicago-area project is benchmarked against a $240,000 median and a 6.2% charge-off floor, the highest printed floor in the table, and in the metros that cross the state line, Davenport-Moline-Rock Island and Cape Girardeau among them, the trade area and the competitor count should follow drive times into Iowa or Missouri.

Larger loans in smaller markets

Several downstate medians sit above Chicago's $240,000: $334,000 in Bloomington, $300,000 in Champaign-Urbana, $275,000 in Peoria and $500,000 in the Ottawa micro area, while Springfield ($175,900) and Cape Girardeau ($181,550) are the lowest. Peoria's 299 loans carry $220.6 million, more than Springfield's $162.3 million on 409, and Decatur's 161 loans total $101.2 million against Bloomington's $99.0 million on 175. Where the typical loan is larger than Chicago's and the market far smaller, the study must show that local households, employers and visitors can carry the debt.

Where the rate is withheld

Rockford and Springfield print the lowest floors, 3.6% each, against 6.0% for Davenport-Moline-Rock Island and 5.7% for St. Louis. Peoria, Champaign-Urbana, Bloomington, Decatur, Cape Girardeau and Ottawa have the rate withheld, which makes it neither low nor zero: those areas simply have no printed loss benchmark, and the study has to build the case from employers, households, named competitors and nearby comparable loans.

SBA loans by metro area touching Illinois, FY2017 to FY2026
Metro or micro areaLoansDollarsMedian loanCharged off (floor)
Chicago-Naperville-Elgin, IL-IN Metro Area20,063$11.17 billion$240,0006.2%
St. Louis, MO-IL Metro Area4,471$2.55 billion$250,0005.7%
Rockford, IL Metro Area481$271.5 million$251,0003.6%
Springfield, IL Metro Area409$162.3 million$175,9003.6%
Davenport-Moline-Rock Island, IA-IL Metro Area389$194.4 million$208,0006.0%
Peoria, IL Metro Area299$220.6 million$275,000withheld
Champaign-Urbana, IL Metro Area254$155.3 million$300,000withheld
Bloomington, IL Metro Area175$99.0 million$334,000withheld
Decatur, IL Metro Area161$101.2 million$249,000withheld
Cape Girardeau, MO-IL Metro Area106$38.9 million$181,550withheld
Ottawa, IL Micro Area101$76.3 million$500,000withheld

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA loans by metro area touching Illinois, FY2017 to FY2026", https://www.analytics.loan/illinois-feasibility-study-data#metros-metros.

Back to the contents

SBA lenders in Illinois

The SBA lenders with a recorded book of loans for projects in Illinois, ranked by loans; no lender with fewer than 5 loans is listed.

The count leader and the dollar leaders

The Huntington National Bank's 4,003 Illinois SBA loans over FY2017 to FY2026 dwarf every other lender's count, yet its $883.2 million ranks fourth by dollars, behind Small Business Growth Corporation ($1.58 billion on 1,833 loans), Byline Bank ($1.31 billion on 1,124) and SomerCor 504, Inc. ($978.0 million on 1,099). U.S. Bank, National Association, third by count with 1,455 loans, wrote $294.4 million. A hotel request near the $2.3 million median and a salon loan near $100,000 belong with different lenders in this table, and the study should be built for the one that finances projects of its size.

504 lending is concentrated

Against the 3,251 SBA 504 loans Illinois approved in the decade, the 1,833 of Small Business Growth Corporation and the 1,099 of SomerCor 504, Inc. leave little room for Wessex 504 Corporation (130 loans, $99.6 million) or Rockford Local Development Corporation (95 loans, $81.0 million), both named in the page's 504 tables by class. SomerCor 504, Inc. prints a 0.00% floor; the floor for Small Business Growth Corporation is withheld. An Illinois 504 study will most likely land on the desk of one of these lenders and on that of the first-lien bank, and must answer both.

Illinois lenders' own charge-off floors

The range across Illinois lenders dwarfs the range across classes or metros. Independence Bank prints 69.8% on 79 loans worth $9.5 million; Celtic Bank Corporation 19.4%, BayFirst National Bank 18.6% and United Midwest Savings Bank National Association 18.0%; The Huntington National Bank 9.8% on a far larger book. Live Oak Banking Company prints 4.3% on $507.3 million and Millennium Bank (IL) 0.00% on $346.6 million. These record each lender's Illinois mix, not its quality, but they explain why one project meets different downside questions at different desks, and why a study should be built for the most demanding reader if the borrower may approach several lenders.

Volume is not loan size

Similar counts hide very different dollars: GBank and Happen Bank each made 75 loans, for $198.5 million and $133.4 million, while Independence Bank's 79 came to $9.5 million; Busey Bank wrote $181.3 million on 152 loans, Bank of Springfield $40.0 million on 184. A lender whose Illinois book runs to small loans is not the natural reader for a multi-million-dollar hotel or car wash request, and the study's scope should fit the file it will sit in.

SBA lenders by loans approved in Illinois, FY2017 to FY2026
LenderLoansDollarsCharged off (floor)
The Huntington National Bank4,003$883.2 million9.8%
Small Business Growth Corporation1,833$1.58 billionwithheld
U.S. Bank, National Association1,455$294.4 million8.0%
JPMorgan Chase Bank, National Association1,202$243.6 million6.5%
Byline Bank1,124$1.31 billion6.0%
SomerCor 504, Inc.1,099$978.0 million0.00%
Northeast Bank (ME)652$106.4 millionwithheld
BayFirst National Bank454$84.3 million18.6%
Newtek Bank, National Association436$167.1 millionnot reported: fewer than 30 loans in the cohort
Village Bank and Trust, National Association412$233.3 millionwithheld
Live Oak Banking Company379$507.3 million4.3%
Fifth Third Bank367$107.5 million11.9%
PNC Bank, National Association346$106.0 million5.2%
Celtic Bank Corporation309$142.0 million19.4%
Readycap Lending, LLC295$93.4 millionnot reported: fewer than 30 loans in the cohort
First Mid Bank & Trust, National Association253$74.1 millionwithheld
Newtek Small Business Finance, LLC217$160.8 millionwithheld
CenTrust Bank, A Division of SmartBiz Bank National Association212$192.0 millionwithheld
First American Bank (IL)195$139.9 millionwithheld
United Midwest Savings Bank National Association193$67.9 million18.0%
Bank of America, National Association191$79.2 millionwithheld
Bank of Springfield184$40.0 millionwithheld
Wells Fargo Bank National Association179$96.1 million7.6%
Millennium Bank (IL)176$346.6 million0.00%
Midland States Bank164$117.2 millionwithheld
Old National Bank164$161.6 millionwithheld
Busey Bank152$181.3 millionwithheld
Harvest Small Business Finance, LLC143$133.8 million0.00%
St. Charles Bank & Trust Company, National Association136$90.8 millionwithheld
Lendistry SBLC, LLC132$28.7 millionnot reported: fewer than 30 loans in the cohort
Wessex 504 Corporation130$99.6 millionwithheld
Bank of Hope122$25.2 million7.9%
Union National Bank120$38.1 million0.00%
Hinsdale Bank & Trust Company, National Association119$90.3 million0.00%
Merchants Bank of Indiana115$168.3 million0.00%
CIBC Bank USA112$83.2 millionwithheld
Morton Community Bank105$21.8 millionwithheld
Stearns Bank National Association100$36.3 millionwithheld
Rockford Local Development Corporation95$81.0 millionwithheld
First Internet Bank of Indiana95$117.1 millionwithheld
First Merchants Bank94$86.3 millionwithheld
BMO Bank National Association89$60.1 millionwithheld
Associated Bank National Association88$34.2 millionwithheld
Peoples National Bank National Association86$40.9 million0.00%
Peoples Bank & Trust (IL)82$42.6 millionwithheld
Wintrust Bank National Association81$58.7 millionwithheld
Independence Bank79$9.5 million69.8%
Heartland Bank and Trust Company76$30.5 millionwithheld
Happen Bank75$133.4 millionwithheld
GBank75$198.5 millionwithheld
Community First Bank of the Heartland73$37.0 millionwithheld
Barrington Bank & Trust Company, National Association70$44.4 millionwithheld
Wheaton Bank & Trust Company, National Association69$36.0 millionwithheld
PCB Bank67$25.1 millionwithheld
Five Star Bank (CA)64$17.0 millionwithheld
Pan American Bank & Trust63$50.2 millionwithheld
Citibank, N.A.63$17.9 millionnot reported: fewer than 30 loans in the cohort
First Bank of the Lake61$44.3 millionnot reported: fewer than 30 loans in the cohort
American Community Bank & Trust59$32.1 millionwithheld
Scott Credit Union57$9.4 million13.3%
Citizens Bank (TN)56$52.2 millionwithheld
Beverly Bank & Trust Company, National Association56$25.9 millionwithheld
UMB Bank, National Association56$23.1 millionwithheld
VelocitySBA, LLC56$63.3 millionwithheld
Bank of Belleville55$24.0 millionwithheld
Enterprise Bank & Trust51$72.0 millionnot reported: fewer than 30 loans in the cohort
FWBank50$71.6 millionnot reported: fewer than 30 loans in the cohort
Legence Bank48$13.1 millionwithheld
Bank Five Nine48$41.3 millionwithheld
United Community Bank (IL)48$10.3 millionwithheld
Crystal Lake Bank & Trust Company, National Association48$27.9 millionnot reported: fewer than 30 loans in the cohort
Schaumburg Bank & Trust Company, National Association48$26.1 millionwithheld
Centerstone SBA Lending, Inc.48$52.0 millionwithheld
Lake Forest Bank & Trust Company, National Association47$24.1 millionwithheld
Libertyville Bank & Trust Company, National Association47$26.7 millionwithheld
First National Bank of Omaha46$18.4 millionwithheld
Esquire Bank National Association46$38.5 millionnot reported: fewer than 30 loans in the cohort
Regional Development Company45$31.7 millionnot reported: fewer than 30 loans in the cohort
INB, National Association45$12.6 millionwithheld
CRF Small Business Loan Company, LLC45$24.2 millionnot reported: fewer than 30 loans in the cohort
Grand Ridge National Bank40$30.5 millionwithheld
The Fisher National Bank39$8.1 millionwithheld
The Bancorp Bank National Association39$35.3 millionnot reported: fewer than 30 loans in the cohort
State Bank of the Lakes, National Association39$21.8 millionwithheld
First National Bank of Pennsylvania39$29.4 millionnot reported: fewer than 30 loans in the cohort
Colony Bank38$14.1 millionwithheld
Illinois Business Financial Services37$38.3 millionnot reported: fewer than 30 loans in the cohort
United Community Bank (SC)37$18.8 millionwithheld
Simmons Bank37$13.9 millionwithheld
The First National Bank of Waterloo36$3.5 millionwithheld
Midwest Regional Bank36$18.1 millionwithheld
CIBM Bank33$18.2 millionwithheld
Beacon Bank and Trust33$43.1 millionwithheld
Time Bank33$12.2 millionwithheld
Hanmi Bank31$19.8 millionnot reported: fewer than 30 loans in the cohort
Home State Bank, National Association30$3.4 millionnot reported: fewer than 30 loans in the cohort
TowneBank30$32.0 millionwithheld
Northbrook Bank & Trust Company, National Association30$14.0 millionnot reported: fewer than 30 loans in the cohort
Heritage Bank Inc29$13.1 millionnot reported: fewer than 30 loans in the cohort
Woori America Bank27$12.9 millionwithheld
Capital Bank, National Association27$23.5 millionwithheld
Pathward National Association26$40.4 millionwithheld
Commerce Bank25$4.2 millionwithheld
Foresight Bank (IL)25$6.8 millionnot reported: fewer than 30 loans in the cohort

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lenders by loans approved in Illinois, FY2017 to FY2026", https://www.analytics.loan/illinois-feasibility-study-data#lenders-lenders.

Back to the contents

Illinois against its Census division and the nation

Illinois beside the other states of the East North Central Census division, all SBA lending and the tracked asset classes.

First on dollars, third on count

Within the East North Central division Illinois leads on dollars and trails on count: its $12.89 billion from FY2017 to FY2026 beats Ohio's $11.30 billion, Michigan's $9.53 billion, Wisconsin's $7.19 billion and Indiana's $6.28 billion, yet Ohio's 33,343 loans and Michigan's 24,001 both exceed Illinois's 22,837. Illinois borrowers take larger loans on average than any neighbour's, which puts more of each credit decision on the study's projections.

The long record and the recent order

Since FY1991 Illinois has approved 75,120 SBA loans, second to Ohio's 95,823 and ahead of Michigan's 66,059, Wisconsin's 50,315 and Indiana's 40,176, but in the FY2017 to FY2026 decade Michigan's 24,001 loans moved past Illinois's 22,837. In the tracked classes Illinois's 6,489 loans trail Ohio's 7,638 and edge Michigan's 6,223. A study that borrows an Ohio or Michigan benchmark should match loan size as well as class, because the Illinois book is built on fewer, larger loans.

The highest loss floor in the division

Illinois's tracked-class charge-off floor, 5.2%, is the division's highest, against 4.4% for Ohio, 3.3% for Michigan, 3.2% for Indiana and 2.8% for Wisconsin. The page cannot separate mix, with restaurants and fitness centers heavy in the Illinois book, from market, so a study should not import a neighbour's loss experience to argue an Illinois project's risk down; it should place the project against the state's own record with Illinois rents, wages, taxes and competitors.

SBA lending: Illinois, the East North Central division and the United States
StateAll SBA loans FY1991 to FY2026All SBA loans FY2017 to FY2026All SBA dollars FY2017 to FY2026Loans in tracked classes FY2017 to FY2026Charged off, tracked classes (floor)
Illinois75,12022,837$12.89 billion6,4895.2%
Indiana40,17613,129$6.28 billion3,5473.2%
Michigan66,05924,001$9.53 billion6,2233.3%
Ohio95,82333,343$11.30 billion7,6384.4%
Wisconsin50,31513,157$7.19 billion3,8602.8%
United States2,207,426647,329$353.09 billion

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lending: Illinois, the East North Central division and the United States", https://www.analytics.loan/illinois-feasibility-study-data#compare-compare.

Back to the contents

Illinois's economy for a feasibility study

The establishments, jobs and payroll of each asset class's industry in Illinois, and the state's population, income and output, from the Census Bureau and the Bureau of Economic Analysis.

Restaurants: the formats move apart

County Business Patterns shows the formats diverging. Full-service restaurants rose from 9,851 establishments in 2018 to 9,928 in 2023 while March employment fell from 212,218 to 188,628; limited-service restaurants grew to 10,622 establishments and 189,552 employees, overtaking full service on staff, a reversal of 2018. The quickest growth among the restaurant formats came from coffee shops and snack bars, 2,126 to 2,677 establishments and 24,321 to 33,569 employees. A full-service study, in the largest SBA class with 1,317 loans and an 8.0% floor, must show staffing that holds in a format shedding workers; a coffee study must count the recent entrants in its trade area.

Hotels: fewer staff, heavy lending

Hotel and motel employment fell from 50,484 to 40,639 between 2018 and 2023 and establishments from 1,489 to 1,474, on a 2023 payroll of $1.85 billion, yet SBA lenders put $984.7 million into 406 Illinois hotel loans over FY2017 to FY2026. A hotel study has to reconcile those facts: whether the subject's market has regained the room-nights behind the lost jobs, whether the budget can staff the property at current wages, and whether a loan near the $2.3 million median is sized to stabilised results or to a recovery not yet shown.

Practices, child care and fitness

Medical offices fell from 7,152 establishments to 6,775 as employment rose from 89,948 to 106,595, on the table's largest payroll, $11.62 billion; dental offices fell from 6,009 to 5,781 with staff almost unchanged at 37,948. Child care centers grew on both counts, 3,037 to 3,138 and 38,226 to 42,273, while fitness centers held steady at 1,608 to 1,621 establishments and lost staff, 35,469 to 32,618. The SBA floors differ as sharply: 1.8% for child care, 2.7% for medical and 0.00% for dental offices against 9.7% for fitness. A practice study turns on competition from larger groups, a child care study on staffing to licensed capacity, and a fitness study on membership at 2023 levels, not 2018 ones.

Warehousing grew; the SBA book barely shows it

The main warehouse and distribution row is the fastest-growing employer in the table, from 575 establishments and 43,985 employees in 2018 to 765 and 79,406 in 2023, on a $4.33 billion payroll, yet the SBA record holds only 32 Illinois warehouse loans for $34.1 million, too few for a rate. The data center row held level on staff, 21,382 to 21,934, as establishments fell from 670 to 627, and its 39 SBA loans have a $200,000 median. Such projects reach an Illinois lender without a state loss rate, so the study carries the case: tenant demand, access, power and the large operators behind those employment figures.

Groceries, fuel, liquor and car washes

Grocery establishments numbered 2,647 in both 2018 and 2023, employment edging from 96,054 to 97,785. With no net new stores, a new or acquired grocery takes sales from an incumbent, which fits the class's 13.2% floor, the SBA table's highest; the study should name the stores it will draw from. The main gas station row moved from 3,399 to 3,407 establishments and lost staff, 30,406 to 28,186, while liquor stores grew from 1,379 to 1,496 and car washes from 742 to 783, with car wash staff up from 5,551 to 6,215. With a 0.00% charge-off floor and 8.2% cancellation, Illinois car wash lending leaves the study to prove the site and its competitors rather than the class.

Income rose while population held

Median household income climbed from $69,187 to $83,211 while population barely moved, 12,671,821 in 2019 to 12,710,158 in 2024. Gross domestic product went from $896.16 billion in 2019 to $1240.98 billion in 2025, and personal income from $741.93 billion to $1004.65 billion. Illinois growth is in income and output, not headcount, so a study projecting sales from population leans on the weakest measure the state has; it should model the trade area's own income and spending and say whether that growth is stated before or after inflation.

Industry establishments, employees and payroll in Illinois, by asset class
Asset class (NAICS)Establishments 2018Establishments 2023Employees 2018Employees 2023Annual payroll 2023
Full-service restaurant (NAICS 722511)9,8519,928212,218188,628$5.55 billion
Limited-service restaurant (NAICS 722513)10,46010,622183,705189,552$4.00 billion
Child care center (NAICS 624410)3,0373,13838,22642,273$1.41 billion
Fitness center (NAICS 713940)1,6081,62135,46932,618$655.9 million
Automotive mechanical repair (car and truck) (NAICS 811111)3,8853,89116,27618,358$1.03 billion
Automotive mechanical repair (car and truck) (NAICS 811112)9481339273$10.2 million
Automotive mechanical repair (car and truck) (NAICS 811113)154126579490$24.6 million
Automotive mechanical repair (car and truck) (NAICS 811118)140136471683$26.0 million
Hotel and motel (NAICS 721110)1,4891,47450,48440,639$1.85 billion
Beauty salon (NAICS 812112)3,3513,34621,22716,713$541.7 million
Gas station and truck stop (NAICS 447110)3,3993,40730,40628,186$774.3 million
Gas station and truck stop (NAICS 447190)4174124,6226,177$220.7 million
Liquor store (NAICS 445310)1,3791,4966,0926,993$206.1 million
Coffee shop and snack bar (NAICS 722515)2,1262,67724,32133,569$745.5 million
Dental office (NAICS 621210)6,0095,78137,68737,948$2.26 billion
Grocery store (NAICS 445110)2,6472,64796,05497,785$3.05 billion
Medical office (physicians) (NAICS 621111)7,1526,77589,948106,595$11.62 billion
Car wash (NAICS 811192)7427835,5516,215$172.1 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312120)1161551,5992,545$104.7 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312130)5766511611$21.9 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312140)2540663935$75.0 million
Rehabilitation and therapy clinic (NAICS 621340)1,9802,54520,53124,701$1.23 billion
Veterinary clinic (NAICS 541940)1,0871,15913,62016,563$851.8 million
Caterers (includes banquet halls with catering staff) (NAICS 722320)4975138,7376,537$209.1 million
Self storage (NAICS 531130)5275721,3291,476$64.4 million
Nonresidential lessor (flex, office and retail investor buildings) (NAICS 531120)1,0421,0306,6546,655$668.6 million
Data center (NAICS 518210)67062721,38221,934$2.64 billion
Warehouse and distribution (NAICS 493110)57576543,98579,406$4.33 billion
Warehouse and distribution (NAICS 493190)981101,8822,450$166.4 million
School (elementary and secondary, including charter) (NAICS 611110)90488639,51740,244$1.92 billion
Assisted living (without nursing care) (NAICS 623312)44841517,82916,715$593.9 million

Source: U.S. Census Bureau, County Business Patterns 2018 and 2023 (NAICS 2017), through the Census Data API; establishments, March employment and annual payroll; suppressed cells print their flag. Most government and self-employed activity is outside CBP. Download this table (CSV). Cite as: Loan Analytics, "Industry establishments, employees and payroll in Illinois, by asset class", https://www.analytics.loan/illinois-feasibility-study-data#economy-industry.

Population and household income in Illinois
Measure20192024
Population12,671,82112,710,158
Median household income$69,187$83,211

Source: U.S. Census Bureau, American Community Survey 1-year estimates, 2019 and 2024, through the Census Data API (tables B01003 and B19013). Download this table (CSV). Cite as: Loan Analytics, "Population and household income in Illinois", https://www.analytics.loan/illinois-feasibility-study-data#economy-people.

Output and income in Illinois
MeasureEarlier yearLatest year
Gross domestic product, 2019 and 2025$896.16 billion$1240.98 billion
Personal income, 2019 and 2025$741.93 billion$1004.65 billion

Source: U.S. Bureau of Economic Analysis, regional accounts (SAGDP2 all-industry total, current dollars; SAINC1 personal income), through the BEA API. Download this table (CSV). Cite as: Loan Analytics, "Output and income in Illinois", https://www.analytics.loan/illinois-feasibility-study-data#economy-output.

Back to the contents

USDA Business and Industry guarantees in Illinois

New USDA B&I guaranteed loan awards for projects in Illinois by fiscal year, and by county, from USAspending; aggregates only.

A handful of awards a year

USDA Business and Industry guarantees reach Illinois a handful at a time. FY2025 was the series high, 12 new awards for a net $100.5 million, ahead of FY2024's 6 for $53.0 million; FY2020 had the most awards, 16, but only $44.1 million. Against FY2025's 2,835 SBA 7(a) loans for $1.31 billion, B&I is a small channel, and one large project can move a year's B&I total.

Withheld years and negative nets

FY2026 and FY2016 print award counts, 2 and 1, but no dollars. What decides the withholding is not the number of new awards: the dollar figure is held back in any year in which under 3 awards saw activity of any kind, an original award or a later change to an older one, and in these two Illinois years that combined tally stayed below the line. FY2026 also stops at August 2026 in this record, so it is a part year. Neither withheld value is zero. FY2008 shows the rule at work, a single new award beside a printed net of $-35.2 million, because later actions carried the year past the threshold; that net and FY2009's $-9.9 million mean reductions booked in those years outweighed their new awards. A study citing Illinois B&I activity should use award counts and the printed years from FY2017 to FY2025, not a long-run sum that nets those reductions in.

What an Illinois B&I study carries

Loan Analytics writes B&I studies for Illinois projects as well as SBA ones, and per the site's 2026 fee survey they are the longer documents, written to 7 CFR Part 5001 with its enumerated factors, a signed consultant's opinion and the author's qualifications. With so few awards there is no Illinois B&I loss record to cite, so the study is the evidence: rural trade-area demand, competing operators, the budget and the projections, set out factor by factor.

USDA B&I guaranteed loan awards in Illinois by fiscal year
Fiscal yearNew awardsFace value, net
FY20262withheld: fewer than 3 awards
FY202512$100.5 million
FY20246$53.0 million
FY20235$31.6 million
FY20223$11.4 million
FY20218$33.9 million
FY202016$44.1 million
FY20198$9.8 million
FY20188$20.2 million
FY20177$10.9 million
FY20161withheld: fewer than 3 awards
FY20156$3.4 million
FY20145$8.1 million
FY20134$12.0 million
FY20125$21.0 million
FY20117$29.0 million
FY201011$29.7 million
FY20097$-9.9 million
FY20081$-35.2 million

Source: USAspending.gov records of USDA Business and Industry guaranteed loan awards by project state, face value of the loan net of later changes, as compiled in Loan Analytics' USDA tables; a year's dollars are withheld where fewer than 3 awards were touched that year (new awards and later actions together), so a year can show dollars beside 0, 1 or 2 new awards; FY2026 runs through August 31, 2026; aggregates only, no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Illinois by fiscal year", https://www.analytics.loan/illinois-feasibility-study-data#usda-usda-by-year.

USDA B&I guaranteed loan awards in Illinois by county, FY2015 to FY2026
CountyAwardsFace value
Macoupin, IL (FIPS 17117)6$17.5 million
Will, IL (FIPS 17197)5$11.6 million
Tazewell, IL (FIPS 17179)4fewer than 5 awards
Williamson, IL (FIPS 17199)4fewer than 5 awards
Brown, IL (FIPS 17009)3fewer than 5 awards
Clark, IL (FIPS 17023)3fewer than 5 awards
Edgar, IL (FIPS 17045)3fewer than 5 awards
McLean, IL (FIPS 17113)3fewer than 5 awards
Morgan, IL (FIPS 17137)3fewer than 5 awards
Randolph, IL (FIPS 17157)3fewer than 5 awards
St. Clair, IL (FIPS 17163)3fewer than 5 awards
Sangamon, IL (FIPS 17167)3fewer than 5 awards
Stephenson, IL (FIPS 17177)3fewer than 5 awards
Christian, IL (FIPS 17021)2fewer than 5 awards
Dekalb, IL (FIPS 17037)2fewer than 5 awards
Effingham, IL (FIPS 17049)2fewer than 5 awards
Knox, IL (FIPS 17095)2fewer than 5 awards
McHenry, IL (FIPS 17111)2fewer than 5 awards
Mason, IL (FIPS 17125)2fewer than 5 awards
Ogle, IL (FIPS 17141)2fewer than 5 awards
Whiteside, IL (FIPS 17195)2fewer than 5 awards
Bureau, IL (FIPS 17011)1fewer than 5 awards
Champaign, IL (FIPS 17019)1fewer than 5 awards
Clinton, IL (FIPS 17027)1fewer than 5 awards
Coles, IL (FIPS 17029)1fewer than 5 awards
Crawford, IL (FIPS 17033)1fewer than 5 awards
Hancock, IL (FIPS 17067)1fewer than 5 awards
Jo Daviess, IL (FIPS 17085)1fewer than 5 awards
Johnson, IL (FIPS 17087)1fewer than 5 awards
Kane, IL (FIPS 17089)1fewer than 5 awards
Kankakee, IL (FIPS 17091)1fewer than 5 awards
McDonough, IL (FIPS 17109)1fewer than 5 awards
Marshall, IL (FIPS 17123)1fewer than 5 awards
Mercer, IL (FIPS 17131)1fewer than 5 awards
Monroe, IL (FIPS 17133)1fewer than 5 awards
Montgomery, IL (FIPS 17135)1fewer than 5 awards
Perry, IL (FIPS 17145)1fewer than 5 awards
Pike, IL (FIPS 17149)1fewer than 5 awards
Rock Island, IL (FIPS 17161)1fewer than 5 awards
Shelby, IL (FIPS 17173)1fewer than 5 awards
Warren, IL (FIPS 17187)1fewer than 5 awards

Source: USAspending.gov award records of USDA Business and Industry guarantees (assistance listing 10.768) by place of performance county, face value net, FY2015 through August 31, 2026, aggregated by Loan Analytics; dollars are withheld where fewer than 5 awards stand behind them; no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Illinois by county, FY2015 to FY2026", https://www.analytics.loan/illinois-feasibility-study-data#usda-usda-by-county.

Back to the contents

Questions buyers ask

Who writes a feasibility study that an Illinois SBA lender will accept?

Loan Analytics does, independent of both sides of the loan, for 7(a), 504 and B&I files anywhere in Illinois, and each study ends in a signed opinion on whether the project supports the debt. Per the site's 2026 fee survey, the lender commissions the study for independence, as it does the appraisal, and the borrower bears the cost. The analysis starts from the Illinois record on this page, 22,837 SBA loans in the FY2017 to FY2026 decade with class, metro and lender detail, and extends it to the subject site.

Does every SBA loan in Illinois need a feasibility study?

No. SBA's power to ask for one is discretionary, and the conditions the site's 2026 fee survey quotes from the SOP (a saturated market, a unique concept, highly specialised property, a project oversized for its community, fast growth carrying unseasoned debt) fit several Illinois classes: hotels at a $2.3 million median, car washes at $1.0 million, fuel sites at $967,500, and high-floor classes such as grocery at 13.2% charged off. The market overview on this page adds start-ups, ownership changes with no operating record at the site and new construction.

What does a hotel feasibility study for an Illinois loan cost?

For a new-build hotel, the site's 2026 fee survey puts the published market range in its complex tier at $10,000 to $25,000, and buying an operating hotel with a trading record calls for less work than building one. The going-concern appraisal a special-purpose hotel loan also needs is listed separately, at $5,000 to $15,000. These are survey ranges, not a quote: Loan Analytics prices each Illinois hotel study with its scope, and much of the work is checking each competing hotel one by one. Either fee is small beside an Illinois hotel loan at the $2.3 million median.

How much should an Illinois gas station study cost, environmental report included?

Single-site fuel studies sit in the lower tier of the site's 2026 fee survey, published at $5,000 to $12,500. The Phase I environmental assessment is billed separately, and the survey's published Phase I range for a high-risk use such as an Illinois fuel site is $3,500 to $6,000; it also notes SBA requires one for gas stations whatever the loan size. With a 20.9% cancellation floor across 304 Illinois fuel loans, both should be finished before the lender commits.

How long does a feasibility study for an Illinois project take?

Loan Analytics sets the timeline in its scope, once it knows the asset class, the Illinois county and the program, and fits it to the loan's schedule so the file is not left waiting on an expired appraisal. Scope drives it: per the site's 2026 fee survey, more sites mean more market sections, a new build needs a cost review and a post-opening ramp, a franchise needs the brand's system results checked, and USDA adds its regulatory factors. A thin market such as the Ottawa micro area, 101 SBA loans in the FY2017 to FY2026 decade, also means in-person checks of comparable properties.

Which lenders make SBA 504 loans for Illinois projects?

Small Business Growth Corporation, with 1,833 loans for $1.58 billion, and SomerCor 504, Inc., with 1,099 for $978.0 million, lead by a wide margin against the state's 3,251 SBA 504 loans from FY2017 to FY2026. Wessex 504 Corporation and Rockford Local Development Corporation follow with 130 and 95 loans in the lender table and appear in the page's 504 class tables. The study is written to satisfy the 504 lender and the senior bank at once.

What will an Illinois lender test in a restaurant feasibility study?

Restaurants are both the largest and one of the weaker classes here: full-service restaurants hold 1,317 SBA loans with floors of 14.7% cancelled and 8.0% charged off, limited-service restaurants 796 with 11.9% and 5.9%. Saturation, one of the SOP conditions the fee survey quotes, is the obvious test, and the 2023 counts of 9,928 full-service and 10,622 limited-service establishments give it substance. The study answers with daypart demand, named competitors in the trade area, labour cost at current wages and a downside in which sales open below plan.

Where in Illinois is SBA lending concentrated?

In the Chicago-Naperville-Elgin metro area, with 20,063 SBA loans for $11.17 billion from FY2017 to FY2026, its Indiana counties included. St. Louis follows with 4,471 loans for $2.55 billion across both states, then Rockford (481 loans, $271.5 million), Springfield (409) and Davenport-Moline-Rock Island (389). Peoria has 299 loans but $220.6 million, and the Ottawa micro area the highest median, $500,000. Outside Chicago the local record is thinner, so the trade-area evidence must be stronger.

Is an SBA loan in Illinois riskier than one in Indiana, Michigan, Ohio or Wisconsin?

On the page's floors the Illinois record is weaker: 5.2% of tracked-class FY2017 to FY2021 disbursements have charged off, against 4.4% in Ohio, 3.3% in Michigan, 3.2% in Indiana and 2.8% in Wisconsin. The floors describe cohorts, and the gap may owe as much to the Illinois class mix as to its markets, but an Illinois lender will expect the study to deal with Illinois's own loss history instead of leaning on regional averages.

Does Loan Analytics prepare USDA B&I feasibility studies in Illinois, and at what cost?

Yes, Loan Analytics writes B&I studies for Illinois projects as well as SBA ones. The site's 2026 fee survey records published USDA study fees of $7,500 to $18,750 or more, since the regulation behind them, 7 CFR Part 5001, enumerates more factors than the SBA standard, and treats the study as compulsory for a new-business borrower whose B&I loan exceeds $1 million. In Illinois the program is small and uneven: 12 new awards for $100.5 million in FY2025, 6 for $53.0 million in FY2024 and 2 in FY2026 with the value withheld.

Back to the contents

Illinois feasibility study consultant: request a scope

Request a scope for your Illinois project and Loan Analytics will set it against this page before quoting: the class row with its median and floors, the metro or micro area, the lenders active in that class and, for a rural site, the B&I years. A Peoria restaurant, a Chicago-area hotel near the $2.3 million median and a fuel site in a class with a 20.9% cancellation floor need different studies, and the scope names the tests your lender will see.

Send the asset class, county, program and loan amount through the form below or to Info@analytics.loan, and the reply brings a scope and timeline written for that credit file.

Request Scope & Timeline

Corrections

Figures on this page were checked against SBA's and USAspending's own records and corrected where they differed. Each corrected figure is marked in the text; what it counts and where it comes from:

  1. 299: lenders with an Illinois 7(a) approval over five years; FY2021 to FY2025, distinct lender keys, project state IL. Source: SBA loan data as of 2026-09-30.

Start with the data.

Contact Us