State Feasibility Study Data

Connecticut Feasibility Study Consultants

Connecticut has the highest per-capita personal income of any state in the country and a roughly $293 billion economy anchored by finance, insurance, and advanced manufacturing, and a feasibility study in Connecticut now sits at the center of how lenders move SBA and USDA projects from application to approval. The state's population is growing only modestly and unevenly, its commercial real estate markets are reshaping themselves in real time through office-to-residential conversion, and its economy ranks among the most productive in the nation despite real affordability and workforce headwinds. Loan Analytics publishes the lending, demographic, and commercial real estate data behind those numbers, and prepares independent feasibility studies for SBA 7(a), SBA 504, and USDA-financed projects across Connecticut when a lender requires the full report. This page lays out the current Connecticut market and explains what a feasibility study consultant actually delivers for a credit file.
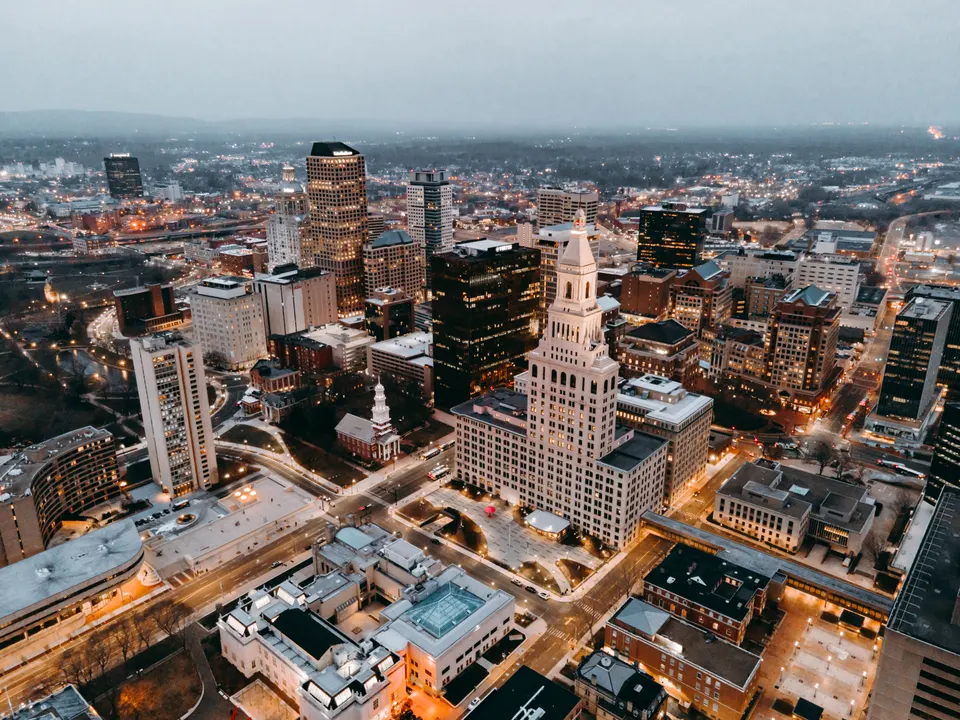
Connecticut feasibility study consultant

Loan Analytics prepares feasibility studies for Connecticut projects that a lender plans to finance through the SBA's 7(a) or 504 program or a USDA Business and Industry guarantee, and writes each one to be read by the credit officer who signs off on the loan, not as a pitch for the borrower. The demand for that work shows in the state's own record. Lenders approved 8,127 SBA loans for Connecticut projects from FY2017 to FY2026, worth $3.26 billion, second in New England only to Massachusetts, and the latest years are the largest by dollars the state has seen: 7(a) approvals reached $388.7 million on 1,005 loans in FY2025, and 504 approvals reached $109.2 million on 102 loans in FY2026, the largest 504 dollar total the table prints.

Our scope follows the classes that carry the Connecticut book. In the tracked classes, full-service restaurants come first with 413 loans, liquor stores follow with 247 and limited-service restaurants with 205, and for those small-ticket operators the study asks whether one more store fits a trade area that already holds many. Hotels are the other end of the market: only 78 loans, yet $229.2 million, more dollars than any other class, at a $3.1 million median, with 37 written under 504. A Connecticut credit desk also knows the state's floors. At least 13.7% of approvals in the tracked classes were cancelled after approval, at least 5.2% of disbursed loans have been charged off, the highest floor printed for any state in the New England division, and gas stations carry a 23.5% cancellation floor, the highest of any class measured here.

What the lender receives is a third-party study fitted to one Connecticut town, one class and one program: the trade area, each competing operator checked and sized, the demand the site can capture and how fast, a projection built on the subject's own costs, and a downside case run against the years when Connecticut lending fell, such as FY2020, when 7(a) approvals dropped to 444. The desks that will read it are listed on this page, from Manufacturers and Traders Trust Company with 1,338 loans to New England Certified Development Corporation with $322.7 million. Tell us the class, the municipality and which program the lender has in mind in the scope form below, and we reply with scope and timeline.

Request Scope & Timeline

Image by Balazs Busznyak

SBA Lending in Connecticut: The Current Picture

Connecticut is a solid SBA market. Recent analysis of SBA data shows Connecticut businesses receiving roughly $349 million in SBA 7(a) loan approvals across about 917 businesses in 2025, with an average loan size near $381,000, somewhat below the national average of $443,097. That profile reflects a market with a heavy concentration of services, professional, and consumer businesses, including a meaningful share of smaller working-capital and acquisition loans rather than the largest real-estate transactions. With roughly 84 Corrected active SBA 7(a) lenders competing across the state and the agency administering Connecticut through its district office in Hartford, borrowers draw on a deep pool of national institutions, regional banks, and community lenders.

The national program sets the backdrop for every Connecticut deal. The SBA guaranteed 70,242 7(a) loans worth $31.1 billion in FY2024, then closed FY2025 at 84,840 Corrected combined 7(a) and 504 loans for $45.09 billion Corrected, the most capital the agency has approved in a single year on record. That record volume came alongside materially stricter underwriting standards, which means busier credit desks paired with closer scrutiny of the borrower projections inside each application. A Connecticut feasibility study consultant earns a place in the file precisely because independent market work gives a credit committee something concrete to test the borrower's assumptions against.

The practical point for a borrower or lender searching for a feasibility study consultant in Connecticut is that the document is not a box-checking exercise. On startup projects, on change-of-ownership transactions where the buyer has no operating history at the site, and on ground-up construction with no existing revenue to underwrite, the feasibility study is the analysis that lets a credit committee size the deal with confidence. The 504 program in particular, which finances owner-occupied real estate and major fixed assets through a Certified Development Company alongside a conventional lender, routinely involves projects large enough that an independent market study is expected, especially given Connecticut's high real estate values. Although the state is densely developed, USDA Business and Industry lending still runs alongside the SBA programs in the rural eastern and northwestern corners of Connecticut. A Connecticut feasibility study company that understands both the SBA standard operating procedures and the local submarket is doing two jobs at once: satisfying a federal documentation requirement and giving the lender a defensible basis for its credit decision.

Where Connecticut Is Growing: Population and County Demographics

Connecticut is the twenty-ninth-most-populous state at roughly 3.6 million residents, and its growth has been modest and uneven, which is the central fact for any demand analysis. Over the year to mid-2025 the state added population primarily on the strength of international migration, a net gain of roughly 17,500 people from abroad, which offset a net loss of about 6,000 household residents to domestic out-migration along with a small natural increase. Notably, that international migration was less than half of the prior year's level, the lowest since the pandemic, which makes the recent gains fragile.

The geography of that change matters as much as the total. Fairfield County, the state's most populous at roughly 944,000 residents, sits just outside New York City and is the engine of the state's affluence, anchored by the business hub of Stamford and the wealth of Greenwich, though it is also one of the most economically unequal counties in the nation and has seen notable domestic out-migration from its western towns. Hartford County, home to the capital, and New Haven County are the state's other two large population centers, each with well over 850,000 residents. Connecticut is also among the most highly educated states in the country, with well over 40 percent of adults holding a bachelor's degree or higher, a workforce profile that shapes demand across office, housing, and retail. A project that pencils cleanly in a growing lower-Fairfield submarket can face very different demand in a struggling central city or a rural eastern town, and the Connecticut label alone tells a lender almost nothing. The work is in the trade area.

Connecticut Commercial Real Estate: The Five Major Markets

A Connecticut feasibility study lives or dies on which asset class is in question, because the five major commercial real estate sectors, spread across the Fairfield County, Hartford, and New Haven markets, are moving in distinctly different directions.

Office is undergoing a structural transformation, most visibly in Fairfield County. The county's office vacancy rate has been declining, but largely because office buildings are being removed from inventory and converted to apartments rather than because demand has rebounded: roughly four million square feet has come out of the market since 2021, shrinking total inventory to around 37 million square feet, even as tenants continue to right-size. Leasing that does happen is concentrated in the Stamford and Greenwich central business districts, where a flight to quality favors newer, amenity-rich buildings near transit and New York City. The Hartford office market is similarly elevated, with vacancy above 20 percent after several quarters of right-sizing. Industrial is the tighter, healthier sector: Central Connecticut, anchored by Hartford and a roughly 140-million-square-foot base, runs in the mid-4 percent vacancy range, with life sciences and logistics demand supporting it. Multifamily has historically been one of the state's most stable sectors, with low vacancy and steady demand, now reinforced by the new supply created through office conversions.

The remaining sectors complete the spread. Retail is generally steady, supported by the state's high household incomes and limited new construction. A distinctive growth story sits inside the office and lab markets of New Haven, where an expanding biotechnology and life sciences cluster around Yale is generating demand that existing space struggles to accommodate. Hospitality spans Fairfield County's corporate and proximity-to-Manhattan demand, the casino and resort market of southeastern Connecticut, coastal and Long Island Sound tourism, and the steady business and university travel of Hartford and New Haven, each with its own distinct demand structure. That divergence between sectors is precisely the question a lender asks a feasibility study to resolve.

Feasibility Studies by Asset Class in Connecticut

Because the search market for Connecticut commercial financing breaks down by property type, it is worth being concrete about the asset classes a feasibility study in Connecticut most often covers, and what each one turns on. A hotel feasibility study in Connecticut depends on demand segmentation across business, group, and leisure travel in a specific submarket, set against the existing and planned room supply, and it varies enormously between a Stamford corporate market, a southeastern casino-resort market, and a coastal or shoreline destination. A gas station and convenience store feasibility study hinges on traffic counts, fuel volumes, the competitive set within the trade area, and the inside-sales and food-service component that increasingly drives c-store margins, a category suited to the heavily traveled I-95 and I-84 corridors. A car wash feasibility study turns on rooftops, daily traffic, and the membership model that now defines express-tunnel economics.

An RV park or campground feasibility study weighs Connecticut's shoreline, river-valley, and quiet-corner tourism against a short season and the conversion of transient demand into longer stays. A multifamily feasibility study tests trade-area household formation and absorption against the apartment pipeline in that specific submarket, a question sharpened by the wave of office-to-residential conversions reshaping supply in places like Stamford. A self-storage feasibility study measures square feet per capita against current and planned inventory in the immediate radius. An assisted living or senior housing feasibility study models the age-qualified population, penetration rates, and acuity mix, a category with deepening demand given Connecticut's aging, affluent population. A restaurant or franchise feasibility study weighs daypart demand and local competitive density against the brand's unit economics, and an industrial or warehouse feasibility study tests logistics access, clear-height and power requirements, and the absorption of comparable space nearby, a matter of real consequence given the tight Central Connecticut industrial market and growing life-sciences demand. Each of these is a distinct analysis with its own demand drivers, and a state as varied as lower Fairfield County, Hartford, New Haven, the southeastern shoreline, and the rural eastern hills cannot be served by a generic template that simply swaps in the word Connecticut.

Construction Costs: The Connecticut Picture

Hard costs feed straight into total project cost, loan sizing, and the debt-service coverage a lender stress-tests, so a current read on construction inflation belongs in every Connecticut feasibility study. The Mortenson Construction Cost Index for the first quarter of 2026 put national nonresidential costs up 1.69 percent for the quarter and 6.77 percent year over year, a useful baseline for any project in the state.

Several forces specific to Connecticut sit on top of that national rate and belong in any serious pro forma. As a densely developed, high-cost Northeast market, Connecticut carries elevated construction costs relative to the national average, shaped by strong union labor, constrained infill development sites, and high land costs, with lower Fairfield County and its proximity to the New York metropolitan area among the more expensive submarkets in the country. The wave of office-to-residential conversion underway in Stamford and elsewhere carries its own distinctive cost and design complexity, as repositioning an aging office tower into apartments is a specialized undertaking. Laboratory and life sciences buildout around New Haven and the broader region carries higher costs as well, and a cold-climate building season and the expense of modernizing older urban building stock add further considerations. A market with these dynamics demands a cost basis built from current local conditions and live bids rather than last year's assumptions or a national average, and a feasibility study earns its keep by checking the cost and operating side of the pro forma against the realities of building in the specific Connecticut submarket.

What a Connecticut Feasibility Study Consultant Delivers

Read the lending, demographic, and market data together and the assignment becomes concrete. Connecticut sends a steady stream of projects to credit committees every year, and tighter underwriting means even strong files draw close review. Population growth that is modest and reliant on international migration, concentrated unevenly across an affluent but unequal landscape, means a demand case has to be built carefully at the submarket level rather than assumed from the state's wealth. Five commercial real estate sectors pointing in different directions, with office reshaping itself through conversion while industrial stays tight, mean asset selection and location drive the outcome. And construction costs that run high across this Northeast market, with specialized conversion and lab work higher still, mean a budget assembled a year ago is already stale.

A feasibility study consultant brings those threads together into a single third-party document written for the lender's file. The work that distinguishes a credible Connecticut feasibility study company is independence and evidence: the consultant is a party independent of both borrower and lender, and the conclusions are tied to verifiable trade-area demographics, a documented competitive supply analysis, demand and absorption modeling, financial projections, and sensitivity testing organized around what a credit committee actually reviews. SBA and USDA guidelines call for exactly this kind of independent study on many startup, expansion, and new-construction projects, and the lender typically orders it once the deal is in underwriting.

The state's investment profile sharpens the need for current data. Connecticut operates a real economy of roughly $293 billion that grew about 2.4 percent in 2025, the second-largest in New England behind Massachusetts, and it posts the highest per-capita personal income of any state in the nation. Its signature industry is finance and insurance, with Hartford long known as a global insurance center and home to major carriers, complemented by a powerful hedge-fund and financial-services presence in Fairfield County. Professional and business services is now the largest single sector, followed by real estate and finance and insurance, and advanced manufacturing is a defining strength, anchored by aerospace and defense names that build jet engines, military helicopters, and submarines in the state. A fast-growing biotechnology and life sciences cluster around New Haven rounds out the picture. The chief headwinds are a high cost of living and energy and a shrinking labor force, real constraints that any forward-looking analysis should weigh. Each of those forces reshapes trade-area demand, labor demand, and absorption in the markets around it, and none of it shows up in a generic template, which is the entire reason a project-specific study exists.

Work With a Connecticut Feasibility Study Consultant

Loan Analytics prepares independent feasibility studies for SBA 7(a), SBA 504, and USDA-financed projects across Connecticut, built on the same data published on this page and extended to the subject property. The study arrives as a third-party document, written for the lender's file, covering trade-area demographics, competitive supply, demand and absorption, financial projections, and sensitivity testing. To scope one, use the form below or write to Info@analytics.loan. Include the property type, the county, and the loan program, and we come back with scope and timeline.

Request Scope & Timeline

SBA loan record in Connecticut, FY2017 to FY2026

SBA 7(a) and 504 loans approved for projects in Connecticut across the asset classes Loan Analytics tracks, from SBA's own loan-level files.

LoansDollars
Both programs2,258$1.18 billion
SBA 7(a)1,975$875.5 million
SBA 504283$301.2 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Connecticut, FY2017 to FY2026, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Cancelled after approval, FY2017 to FY2024 approvals (a floor)13.7%
Charged off to date, FY2017 to FY2021 disbursed loans (a floor)5.2%
Charged off within five years of approval2.5%

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Connecticut, FY2017 to FY2026, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Both rates are floors: SBA withholds the status of open loans. A rate needs at least 30 loans in its cohort.

SBA loans approved in Connecticut by fiscal year, in the asset classes with 10 or more loans and approvals in 5 or more fiscal years

0100200300FY2017FY2018FY2019FY2020FY2021FY2022FY2023FY2024FY2025FY2026Loans, FY2017: 237Loans, FY2018: 224Loans, FY2019: 202Loans, FY2020: 127Loans, FY2021: 222Loans, FY2022: 198Loans, FY2023: 236Loans, FY2024: 249Loans, FY2025: 281Loans, FY2026: 228
Fiscal yearLoansDollars
FY2017237$99.0 million
FY2018224$87.2 million
FY2019202$84.7 million
FY2020127$58.8 million
FY2021222$135.6 million
FY2022198$96.6 million
FY2023236$158.2 million
FY2024249$142.6 million
FY2025281$148.8 million
FY2026228$127.9 million

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Connecticut, FY2017 to FY2026, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Asset classes in Connecticut, ranked by loans

Asset classLoansDollars
Full-service restaurant413$135.7 million
Liquor store247$89.6 million
Limited-service restaurant205$60.8 million
Fitness center164$61.7 million
Beauty salon142$22.2 million
Automotive mechanical repair (car and truck)126$33.1 million
Child care center123$70.4 million
Dental office92$42.2 million
Medical office (physicians)83$40.9 million
Gas station and truck stop79$61.2 million
Hotel and motel78$229.2 million
Coffee shop and snack bar70$17.3 million
Grocery store67$27.6 million
Beverage manufacturing (breweries, wineries, distilleries)66$36.8 million
Car wash43$49.8 million
Rehabilitation and therapy clinic37$10.4 million
Veterinary clinic34$32.7 million
Self storage32$50.5 million
Assisted living (without nursing care)30$24.0 million
Behavioral health and addiction treatment25$8.0 million
Caterers (includes banquet halls with catering staff)21$10.4 million
Nonresidential lessor (flex, office and retail investor buildings)17$15.5 million
Data center10$9.6 million
Skilled nursing8$12.3 million
Warehouse and distribution7$4.8 million
Marina7$5.6 million
Manufactured housing community (lessors of other real estate)6$1.4 million
Hospital5$424,900
Continuing care retirement community4fewer than five loans
Parking lot and garage4fewer than five loans
Multifamily (lessors of residential buildings)3fewer than five loans
School (elementary and secondary, including charter)3fewer than five loans
RV park and campground2fewer than five loans
Urgent care and ambulatory surgery2fewer than five loans
Cold storage1fewer than five loans
Land subdivision1fewer than five loans
Diagnostic imaging center1fewer than five loans

Download this table (CSV). Cite as: Loan Analytics, SBA loan record in Connecticut, FY2017 to FY2026, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Most active SBA lenders in Connecticut's largest classes

Full-service restaurant, SBA 504: lenders by loans approved
LenderLoans
New England Certified Development Corporation18
Community Investment Corporation14

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Full-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
Santander Bank, National Association76
Manufacturers and Traders Trust Company57
Liberty Bank41
TD Bank, National Association26
KeyBank National Association21

Download this table (CSV). Cite as: Loan Analytics, Full-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Liquor store, SBA 504: lenders by loans approved
LenderLoans
Community Investment Corporation7

Download this table (CSV). Cite as: Loan Analytics, Liquor store, SBA 504: lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Liquor store, SBA 7(a): lenders by loans approved
LenderLoans
Santander Bank, National Association71
Manufacturers and Traders Trust Company31
TD Bank, National Association29
Liberty Bank13
KeyBank National Association10

Download this table (CSV). Cite as: Loan Analytics, Liquor store, SBA 7(a): lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Limited-service restaurant, SBA 504: lenders by loans approved
LenderLoans
Community Investment Corporation7
New England Certified Development Corporation7

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 504: lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Limited-service restaurant, SBA 7(a): lenders by loans approved
LenderLoans
Santander Bank, National Association33
Manufacturers and Traders Trust Company29
Live Oak Banking Company14
Liberty Bank14
TD Bank, National Association11

Download this table (CSV). Cite as: Loan Analytics, Limited-service restaurant, SBA 7(a): lenders by loans approved, https://www.analytics.loan/connecticut-feasibility-study-data#state-record.

Feasibility study data by asset class in Connecticut

Feasibility study data by asset class and SBA program in Connecticut

Source: U.S. Small Business Administration, 7(a) and 504 loan-level FOIA files (data.sba.gov), as of 2026-09-30. Totals add the state's cells across the tracked asset classes; they are not all SBA lending in Connecticut.

Feasibility study questions for Connecticut

How many SBA loans have gone to Connecticut projects in the asset classes Loan Analytics tracks?

Connecticut shows 2,258 SBA loans worth $1.18 billion for FY2017 to FY2026 in the tracked asset classes, which excludes SBA borrowers in other lines of business. 7(a) made up 1,975 loans and $875.5 million; 504 made up 283 loans and $301.2 million. The count bottomed at 127 in FY2020 and reached 281 in FY2025, while the strongest dollar year was FY2023 at $158.2 million.

Which asset classes receive the most SBA loans in Connecticut?

Full-service restaurants lead Connecticut with 413 loans ($135.7 million). Liquor stores are second at 247 loans, then limited-service restaurants (205), fitness centers (164) and beauty salons (142). Child care centers (123 loans, $70.4 million) and gas stations and truck stops (79 loans, $61.2 million) carry more dollars per loan than the retail and service classes above them.

How often are SBA loans in Connecticut cancelled or charged off?

Connecticut's floors are among the higher ones in this set. Cancellation after approval touched at least 13.7% of the state's FY2017 to FY2024 approvals; charge-offs to date have reached at least 5.2% of loans disbursed FY2017 to FY2021; and at least 2.5% were charged off before their fifth year from approval ended. They are minimums across the tracked classes, not predictions for any one loan.

Which lenders make the most SBA loans in Connecticut?

Santander Bank, National Association leads every 7(a) table on the Connecticut page: 76 full-service restaurant loans, 71 liquor store loans and 33 limited-service restaurant loans. Manufacturers and Traders Trust Company is second in each, at 57, 31 and 29. Among certified development companies, New England Certified Development Corporation led full-service restaurant 504 lending with 18, and Community Investment Corporation led liquor stores with 7.

Which Connecticut programs can support a project financed with an SBA or USDA loan?

Connecticut's business portal points owners to several state-linked sources: the Small Business Boost Fund for flexible funding, the Community Economic Development Fund for businesses that cannot get traditional bank financing, CT Innovations for venture capital, and the Manufacturing Voucher Program for equipment and expertise. It also notes more than two dozen state tax incentives. These can sit beside an SBA loan, but each has its own terms that the study should reflect.

Source: Business Funding, Connecticut Business Services, State of Connecticut

Which state permits and approvals should a feasibility study for a project in Connecticut account for?

Connecticut's business portal says each type of business has its own licenses and permits, and its New Business Checklist tool lists them by business type. The eLicense site handles applications and renewals. The Department of Consumer Protection licenses industries such as construction and retail, the Department of Public Health covers healthcare facilities, and environmental, transportation and childcare licensing are covered in a separate article. A study should confirm the full set before projecting an opening.

Source: Business Licenses and Permits in CT, Connecticut Business Services, State of Connecticut

What does a feasibility study cost?

The fee rarely needs a separate check. Under SBA rules, as Loan Analytics' cost survey explains, 504 soft costs are financed inside the debenture and 7(a) third-party report fees are eligible uses of proceeds. The study itself is priced in published bands of $5,000 to $12,500 for a single-site restaurant or gas station and $10,000 to $25,000 for complex projects, and a lender-ordered study is a pass-through cost, not Form 159 agent compensation.

Source: SBA Feasibility Study Cost in 2026: Price Bands by Asset Class, and the Fee as Basis Points of the Loan, Loan Analytics

What does a feasibility study for a project in Connecticut test first?

Connecticut's lending is concentrated in restaurants and liquor stores, both small-format uses that depend on the local market. The method's first steps fit them: define a trade area from drive times and access rather than a radius, then document the competing places that are truly substitutable. For child care centers and gas stations, site and technical factors such as access, utilities and environmental conditions come forward, because they can stop a project the market would support.

Source: How a Feasibility Study Is Done: The Loan Analytics Methodology, Loan Analytics

Worked examples

SBA lending in Connecticut, FY1991 to FY2026

Every SBA 7(a) and 504 loan approved for a project in Connecticut since FY1991, by fiscal year, from SBA's own loan files.

A count peak and a dollar peak

Connecticut approved the most 7(a) loans in FY2005, 1,515 of them, for $183.5 million. The dollar peak came much later: FY2025 produced $388.7 million on 1,005 loans, the largest 7(a) dollar total on the table and the most approvals in a year since the 1,114 of FY2007. FY2026 eased to 850 loans and $298.4 million, a total that only FY2025 and FY2024 exceed. A Connecticut 7(a) loan now carries far more debt on average than one from the count peak, and a reviewer will expect the revenue case in a study to be sized for a loan of the current scale, not for the FY2005 vintage.

How far the count can fall

The table also shows how hard Connecticut volume can drop. 7(a) approvals fell from 1,351 in FY2006 to 742 in FY2008 and 510 in FY2009, when dollars sank to $104.7 million, the lowest of any year in the dollar series that begins in FY1994. A second trough came in FY2012 and FY2013, at 509 and 502 loans, and a third in FY2020, when approvals slid from 660 to 444, fewer than in any year since FY1993. A credit officer who has worked through those years will want the study's downside case built from a slower ramp and thinner revenue rather than from a flat haircut on the base case, and will want it shown whether debt service is still covered there, or what reserve fills the gap.

Dollars recovered ahead of loans

After FY2020 the 7(a) dollars moved ahead of the count. FY2021 carried $294.9 million on 632 loans, more dollars than any Connecticut year before it, although the count was below FY2017, FY2018 and FY2019. FY2023 returned $290.4 million on 744 loans and FY2024 $319.0 million on 902. Over FY2017 to FY2026 the state approved 7,311 7(a) loans for $2.62 billion; set beside the full record of 26,966 loans and $6.57 billion, the recent decade's share of the dollars is well above its share of the count. A study that benchmarks its subject on loan sizes from the early 2000s understates the debt a Connecticut business now carries, so its comparison set should be drawn from the recent years.

The 504 line

504 lending in Connecticut followed its own line. Approvals never passed 36 in a year through FY2001, rose to 53 in FY2002 and 101 in FY2005, and reached their highest counts in FY2022 and FY2026, at 104 and 102. In FY2020, when 7(a) approvals fell, the 504 count went the other way, from 64 to 73. The dollar side is the newer story: FY2021, FY2022 and FY2023 each carried between $70.8 million and $71.7 million, FY2025 reached $90.9 million and FY2026 $109.2 million. 504 finances buildings the business itself occupies and long-lived fixed assets, and the market review on this page notes that such projects are often big enough for a lender to expect independent market evidence, so the rising 504 dollars mark where a study is most often a condition of the Connecticut file.

Reading the table on one basis

Two cautions apply when a study cites this table. The dollar columns for FY1991 to FY1993 are withheld for 7(a) and marked fewer than 5 loans for 504, so a long-run average should begin in FY1994 rather than treat those cells as empty. And the table counts gross approvals by fiscal year with cancelled approvals included, which is why its FY2025 line of 1,005 7(a) loans and $388.7 million is not the same measure as the 2025 estimate quoted in the market review above. A Connecticut study should name the basis it uses and keep to it, because with at least 13.7% of tracked-class approvals cancelled, a gross approval count runs ahead of the loans that actually closed.

SBA 7(a) and 504 loans approved in Connecticut by fiscal year
Fiscal yearSBA 7(a) loansSBA 7(a) dollarsSBA 504 loansSBA 504 dollars
FY199184withheld3fewer than 5 loans
FY1992180withheld2fewer than 5 loans
FY1993250withheld3fewer than 5 loans
FY1994478$146.7 million18$5.5 million
FY1995755$147.0 million21$7.4 million
FY1996845$175.4 million36$14.7 million
FY1997781$184.3 million18$4.7 million
FY1998719$162.6 million26$7.4 million
FY1999828$170.1 million33$12.4 million
FY20001,038$168.8 million23$7.9 million
FY20011,043$154.3 million26$10.7 million
FY2002966$153.6 million53$25.9 million
FY20031,189$135.7 million73$28.6 million
FY20041,215$162.9 million80$37.0 million
FY20051,515$183.5 million101$47.3 million
FY20061,351$186.4 million92$49.7 million
FY20071,114$155.7 million80$33.5 million
FY2008742$149.1 million67$34.5 million
FY2009510$104.7 million44$21.9 million
FY2010557$124.6 million72$35.6 million
FY2011612$178.5 million83$45.2 million
FY2012509$152.2 million68$33.0 million
FY2013502$182.6 million70$42.4 million
FY2014535$181.2 million51$39.4 million
FY2015647$200.9 million52$37.5 million
FY2016690$201.6 million55$35.8 million
FY2017702$207.8 million66$33.0 million
FY2018736$204.1 million72$46.7 million
FY2019660$219.4 million64$40.6 million
FY2020444$165.5 million73$40.0 million
FY2021632$294.9 million86$71.5 million
FY2022636$234.7 million104$70.8 million
FY2023744$290.4 million90$71.7 million
FY2024902$319.0 million73$62.7 million
FY20251,005$388.7 million86$90.9 million
FY2026850$298.4 million102$109.2 million
FY1991 to FY202626,966$6.57 billion2,066$1.26 billion
FY2017 to FY20267,311$2.62 billion816$637.1 million

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Download this table (CSV). Cite as: Loan Analytics, "SBA 7(a) and 504 loans approved in Connecticut by fiscal year", https://www.analytics.loan/connecticut-feasibility-study-data#sba-record-sba-by-year.

Back to the contents

Asset classes financed in Connecticut, ranked

Each asset class Loan Analytics tracks, ranked by SBA loans approved in Connecticut from FY2017 to FY2026, with loan size, program split and the cohort floors where at least 30 loans support them.

Restaurants and package stores lead the count

Full-service restaurants rank first in Connecticut with 413 loans and $135.7 million, liquor stores second with 247 and $89.6 million, and limited-service restaurants third with 205. Fitness centers (164) and beauty salons (142) follow, then auto repair (126) and child care centers (123). Liquor stores rank above every service and health class in the table, with a $200,000 median and 235 of their 247 loans written under 7(a). For these small-ticket operators the study is a competition study before it is anything else: how many licensed stores or restaurants already share the trade area, how they price, and what sales the subject can take from them without assuming the market grows to meet it.

Hotels hold the dollars

Rank the same table by dollars and the order changes. Hotels and motels, eleventh by loans with 78, carry $229.2 million, well above full-service restaurants on 413 loans, and their $3.1 million median is the largest of any class by a wide distance; self storage ($864,150), car washes ($775,000), assisted living ($559,500) and veterinary clinics ($540,200) come next. Hotels also hold more 504 loans than any other class, 37 against 34 for full-service restaurants. A Connecticut hotel loan of that size rests on occupancy and rate that do not exist yet, so the study bears more of the credit decision here than in any other class, and its competitive set has to be documented property by property.

Where approvals fall through

Cancellation floors spread widely across the classes the table can measure. Gas stations and truck stops show the highest, at least 23.5% of approvals cancelled, then coffee shops and snack bars at 22.2%, dental offices at 19.5% and limited-service restaurants at 17.5%; beverage manufacturers (6.3%), grocery stores (6.4%) and beauty salons (6.7%) sit at the low end. The table does not say why a given approval fell away, and a study should not claim to know. Its job is to settle, before approval, the questions a later stage would otherwise reopen: for a Connecticut gas station the site's access and environmental condition and the cost to build or rebuild, for a coffee shop the morning traffic the location can actually capture.

Where loans are charged off

Charge-off floors can be printed for fewer classes, and they rank differently. Limited-service restaurants carry the highest, at least 9.3% of disbursed loans charged off, ahead of liquor stores (7.8%), beauty salons (7.7%) and auto repair (6.8%), while beverage manufacturing shows the lowest at 2.4%. Beauty salons are the one class whose charge-off floor is above its cancellation floor, 7.7% against 6.7%: their loans close readily, at a $59,800 median that is the smallest on the table, and on the floors this page can report more of their trouble comes after closing than before it. Dental offices show the opposite shape, 19.5% cancelled against 4.5% charged off. A salon study therefore has to test the operating case, chairs, rent and staff retention, while a dental study should expect its hardest reading before approval.

The mid-sized loans with real estate behind them

Between the small operators and the hotels sits a band of larger loans. Child care centers have 123 loans at a $422,000 median, 22 of them under 504, and both of their floors, 10.4% cancelled and 4.5% charged off, are below the state's tracked-class figures of 13.7% and 5.2%. Medical offices (83 loans, $332,000 median, 17 under 504) and veterinary clinics (34 loans, $540,200 median, a 16.7% cancellation floor) sit in the same range. Car washes (43 loans at $775,000) and self storage (32 loans at $864,150) add 13 and 14 loans under 504. In these classes a Connecticut study has to handle construction cost and absorption as well as demand, because a lender will check the projection against the budget line by line.

The classes the record cannot benchmark

The bottom of the table matters as much as the top. Multifamily shows 3 loans, RV parks and campgrounds 2, warehouse and distribution 7, skilled nursing 8 and data centers 10, and for each of them the table prints neither a median nor a floor, because the counts are too small. The market review on this page discusses multifamily, RV parks and industrial space as Connecticut study types, yet the state's SBA record holds almost nothing to set such a project beside. A study for one of those classes here has to build its benchmark from the trade area, from operating comparables and from the class's national record on this site's asset pages, and should say plainly that Connecticut's own SBA history is too thin to lean on.

SBA loans in Connecticut by asset class, FY2017 to FY2026
Asset classLoansDollarsMedian loanSBA 7(a) loansSBA 504 loansCancelled (floor)Charged off (floor)
Full-service restaurant413$135.7 million$150,0003793414.3%5.6%
Liquor store247$89.6 million$200,0002351215.5%7.8%
Limited-service restaurant205$60.8 million$155,4001901517.5%9.3%
Fitness center164$61.7 million$160,0001491513.4%5.5%
Beauty salon142$22.2 million$59,80013846.7%7.7%
Automotive mechanical repair (car and truck)126$33.1 million$109,5001091713.5%6.8%
Child care center123$70.4 million$422,0001012210.4%4.5%
Dental office92$42.2 million$285,900791319.5%4.5%
Medical office (physicians)83$40.9 million$332,000661713.3%not reported: fewer than 30 loans in the cohort
Gas station and truck stop79$61.2 million$400,000681123.5%not reported: fewer than 30 loans in the cohort
Hotel and motel78$229.2 million$3.1 million413711.9%not reported: fewer than 30 loans in the cohort
Coffee shop and snack bar70$17.3 million$113,85069122.2%not reported: fewer than 30 loans in the cohort
Grocery store67$27.6 million$100,0006346.4%not reported: fewer than 30 loans in the cohort
Beverage manufacturing (breweries, wineries, distilleries)66$36.8 million$325,00054126.3%2.4%
Car wash43$49.8 million$775,00030138.3%not reported: fewer than 30 loans in the cohort
Rehabilitation and therapy clinic37$10.4 million$85,000325not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Veterinary clinic34$32.7 million$540,20029516.7%not reported: fewer than 30 loans in the cohort
Self storage32$50.5 million$864,1501814not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Assisted living (without nursing care)30$24.0 million$559,500228not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Behavioral health and addiction treatment25$8.0 million$120,000223not reported: fewer than 30 loans in the cohortnot reported: fewer than 30 loans in the cohort
Caterers (includes banquet halls with catering staff)21$10.4 milliontoo few loans for these measures
Nonresidential lessor (flex, office and retail investor buildings)17$15.5 milliontoo few loans for these measures
Data center10$9.6 milliontoo few loans for these measures
Skilled nursing8$12.3 milliontoo few loans for these measures
Warehouse and distribution7$4.8 milliontoo few loans for these measures
Marina7$5.6 milliontoo few loans for these measures
Manufactured housing community (lessors of other real estate)6$1.4 milliontoo few loans for these measures
Hospital5$424,900too few loans for these measures
Continuing care retirement community4fewer than five loanstoo few loans for these measures
Parking lot and garage4fewer than five loanstoo few loans for these measures
Multifamily (lessors of residential buildings)3fewer than five loanstoo few loans for these measures
School (elementary and secondary, including charter)3fewer than five loanstoo few loans for these measures
RV park and campground2fewer than five loanstoo few loans for these measures
Urgent care and ambulatory surgery2fewer than five loanstoo few loans for these measures
Cold storage1fewer than five loanstoo few loans for these measures
Land subdivision1fewer than five loanstoo few loans for these measures
Diagnostic imaging center1fewer than five loanstoo few loans for these measures

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA loans in Connecticut by asset class, FY2017 to FY2026", https://www.analytics.loan/connecticut-feasibility-study-data#asset-classes-classes.

Back to the contents

SBA lenders in Connecticut

The SBA lenders with a recorded book of loans for projects in Connecticut, ranked by loans; no lender with fewer than 5 loans is listed.

Three banks lead the count

Manufacturers and Traders Trust Company leads Connecticut with 1,338 SBA loans from FY2017 to FY2026, Santander Bank, National Association follows with 1,046 and TD Bank, National Association with 807, well ahead of Liberty Bank (CT) in fourth with 464. Their dollars diverge: Santander Bank, National Association wrote $316.3 million, Manufacturers and Traders Trust Company $169.9 million on more loans, and TD Bank, National Association $104.0 million. The same study may land on any of these desks, but the loans each has made in the state differ in size, so the sensitivity tests should be scaled to the subject's own debt rather than to a state average that blends such different books.

The dollar leaders

By dollars the order changes. New England Certified Development Corporation leads every lender with $322.7 million on 387 loans, Santander Bank, National Association is second with $316.3 million, Community Investment Corporation third with $259.8 million on 433 loans, and Live Oak Banking Company fourth with $243.1 million on only 185. Both certified development companies in that group sit on the 504 side of the market, where the development company lends beside a conventional bank, so a Connecticut 504 study is read twice: once for the strength of the real estate and once for the cash flow of the business that will occupy it.

Charge-off floors by lender

Where a floor can be printed it varies more by lender than by class. TD Bank, National Association shows at least 15.8% of its measured cohort charged off and Celtic Bank Corporation 14.9%, against 1.6% for Santander Bank, National Association and 0.00% printed for New England Certified Development Corporation and Ives Bank. Manufacturers and Traders Trust Company sits at 8.6%, KeyBank National Association at 5.9%, Liberty Bank (CT) at 5.7% and Beacon Bank and Trust at 5.6%. A printed 0.00% records no charge-off in a cohort big enough to measure, not a promise that none will come, and the many lenders marked withheld, Community Investment Corporation and Live Oak Banking Company among them, carry no rate on this page at all. A floor says nothing about one new file, but the spread explains why the same projection can meet different questions at different Connecticut desks.

Smaller banks with town names

Below the large banks sits a band of smaller lenders, several named for Connecticut towns: Thomaston Savings Bank with 76 loans for $20.7 million, Newtown Savings Bank with 72 for $27.7 million, Jewett City Savings Bank with 51 for $9.7 million, Torrington Savings Bank with 37 for $5.6 million and Chelsea Groton Bank with 27 for $5.7 million, alongside Connecticut Community Bank, National Association with 88 for $57.2 million, Union Savings Bank with 44 and Ion Bank with 42. Every charge-off floor in that group is withheld or not reported, so the page offers no loss rate for any of them. Their tickets run from small, as Torrington Savings Bank's book shows, to larger, as Connecticut Community Bank, National Association's does, and a study for a loan from one of them should be proportionate to that loan while its trade-area evidence still holds up for a reader who may know the town well.

Equal counts, different tickets

The middle of the list shows how far loan size varies at the same volume. Celtic Bank Corporation and BayFirst National Bank each made 133 Connecticut loans, for $110.5 million and $26.5 million. Newtek Bank, National Association made 206 for $97.6 million and Newtek Small Business Finance, LLC 163 for $130.7 million, while Northeast Bank (ME) made 167 for $24.6 million. Readycap Lending, LLC wrote 109 loans for $49.7 million and Wells Fargo Bank National Association 123 for $35.2 million. A borrower choosing among these lenders is choosing among very different ticket sizes, and the study behind a large loan from one of them bears more of the credit decision than one written for a small working-capital loan.

SBA lenders by loans approved in Connecticut, FY2017 to FY2026
LenderLoansDollarsCharged off (floor)
Manufacturers and Traders Trust Company1,338$169.9 million8.6%
Santander Bank, National Association1,046$316.3 million1.6%
TD Bank, National Association807$104.0 million15.8%
Liberty Bank (CT)464$82.6 million5.7%
Community Investment Corporation433$259.8 millionwithheld
New England Certified Development Corporation387$322.7 million0.00%
KeyBank National Association288$78.9 million5.9%
Beacon Bank and Trust214$128.6 million5.6%
Newtek Bank, National Association206$97.6 millionnot reported: fewer than 30 loans in the cohort
Live Oak Banking Company185$243.1 millionwithheld
Northeast Bank (ME)167$24.6 millionnot reported: fewer than 30 loans in the cohort
Newtek Small Business Finance, LLC163$130.7 millionwithheld
BayFirst National Bank133$26.5 millionwithheld
Celtic Bank Corporation133$110.5 million14.9%
Wells Fargo Bank National Association123$35.2 millionwithheld
The Huntington National Bank122$39.4 millionwithheld
Ives Bank115$42.0 million0.00%
Readycap Lending, LLC109$49.7 millionnot reported: fewer than 30 loans in the cohort
Citizens Bank, National Association99$33.5 millionwithheld
JPMorgan Chase Bank, National Association95$24.9 millionwithheld
Connecticut Community Bank, National Association88$57.2 millionwithheld
Thomaston Savings Bank76$20.7 millionwithheld
Newtown Savings Bank72$27.7 millionwithheld
United Midwest Savings Bank National Association69$18.9 millionwithheld
Bank of America, National Association65$32.3 millionnot reported: fewer than 30 loans in the cohort
Jewett City Savings Bank51$9.7 millionwithheld
Union Savings Bank44$6.0 millionnot reported: fewer than 30 loans in the cohort
Ion Bank42$25.4 millionwithheld
Torrington Savings Bank37$5.6 millionwithheld
Stearns Bank National Association35$9.3 millionwithheld
Bay Colony Development Corporation31$34.8 millionwithheld
Chelsea Groton Bank27$5.7 millionwithheld

Source: Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lenders by loans approved in Connecticut, FY2017 to FY2026", https://www.analytics.loan/connecticut-feasibility-study-data#lenders-lenders.

Back to the contents

Connecticut against its Census division and the nation

Connecticut beside the other states of the New England Census division, all SBA lending and the tracked asset classes.

Second in New England

Connecticut ranks second in the New England division on every volume column: 29,032 SBA loans from FY1991 to FY2026, 8,127 from FY2017 to FY2026 and $3.26 billion in that decade, behind Massachusetts at 65,435, 19,097 and $5.99 billion, and ahead of New Hampshire at 24,762, 5,801 and $1.70 billion. In the tracked classes its 2,258 loans also rank second, against 4,909 in Massachusetts and 1,503 in New Hampshire. Rhode Island ranks above Maine on the full record, 16,765 loans to 13,569, but below it in the recent decade, 2,919 to 3,595, and Vermont trails on both at 9,725 and 1,962.

More dollars per loan than the neighbours

Lay the dollars beside the loans and a difference appears that neither column shows alone: Connecticut's $3.26 billion over 8,127 loans is more per loan than any other New England state carries, Massachusetts included, though still less than the national record of $353.09 billion over 647,329 loans. Inside Connecticut the class table shows where the large tickets come from, since hotels at a $3.1 million median and $229.2 million weigh on the state total in a way no small-business class does. For a study the consequence is that a Connecticut SBA loan is, on average, larger than a loan in the neighbouring states, and the sensitivity tests have to be sized to that debt rather than borrowed from a smaller market.

Connecticut's loss floor tops New England

Connecticut's tracked-class charge-off floor of 5.2% is the highest printed for any state in the division, above Rhode Island at 5.0%, Vermont at 4.0%, Massachusetts at 3.9%, Maine at 2.2% and New Hampshire at 1.9%. The class table shows where it sits: limited-service restaurants at 9.3%, liquor stores at 7.8%, beauty salons at 7.7% and auto repair at 6.8% all run above the state figure, and each ranks among the largest classes by count. A study for a restaurant, package store or salon in Connecticut should therefore show how the subject differs from the loans behind that floor: a better site, a stronger operator, a market with fewer competitors, or a downside case that still covers debt service.

Who kept their volume

Set the long column beside the recent one and Connecticut has held on to its SBA activity better than New Hampshire or Rhode Island. New Hampshire's full record of 24,762 loans is not far below Connecticut's 29,032, yet in the recent decade New Hampshire approved 5,801 against Connecticut's 8,127, and Rhode Island's 16,765 loans since FY1991 shrink to 2,919 in the same decade. The practical meaning for a Connecticut study is that the competitors it surveys include many operators financed in this decade, whose debt, rent and pricing are current, and the competitive analysis has to find and size them rather than rely on an older directory.

SBA lending: Connecticut, the New England division and the United States
StateAll SBA loans FY1991 to FY2026All SBA loans FY2017 to FY2026All SBA dollars FY2017 to FY2026Loans in tracked classes FY2017 to FY2026Charged off, tracked classes (floor)
Connecticut29,0328,127$3.26 billion2,2585.2%
Maine13,5693,595$1.12 billion1,1112.2%
Massachusetts65,43519,097$5.99 billion4,9093.9%
New Hampshire24,7625,801$1.70 billion1,5031.9%
Rhode Island16,7652,919$997.7 million8905.0%
Vermont9,7251,962$507.5 million5234.0%
United States2,207,426647,329$353.09 billion

Source: SBA 7(a) and 504 loan-level FOIA files as of 2026-09-30 (data.sba.gov; gross approvals, cancelled approvals included), aggregated by Loan Analytics; each figure is kept with its source file and retrieval date. Loan Analytics' SBA loan record from SBA's 7(a) and 504 loan-level files, approvals FY2017 to FY2026 as of 2026-09-30; rates are floors and need at least 30 loans in their cohort; dollars are not shown where fewer than five loans would reveal a single loan. Download this table (CSV). Cite as: Loan Analytics, "SBA lending: Connecticut, the New England division and the United States", https://www.analytics.loan/connecticut-feasibility-study-data#compare-compare.

Back to the contents

Connecticut's economy for a feasibility study

The establishments, jobs and payroll of each asset class's industry in Connecticut, and the state's population, income and output, from the Census Bureau and the Bureau of Economic Analysis.

Food service: full-service flat, quick-service growing

County Business Patterns counts 3,462 full-service restaurants in Connecticut in 2018 and 3,484 in 2023, with employment slipping from 58,678 to 58,365, a class SBA lenders financed 413 times in the decade. Limited-service restaurants grew from 2,713 establishments to 2,883 and from 33,260 employees to 37,321, and the coffee shop and snack bar row went from 1,060 establishments to 1,158 and from 13,935 employees to 14,998. The quick-service formats are adding sites while full-service holds still, yet limited-service carries the state's highest charge-off floor, 9.3%, and coffee shops a 22.2% cancellation floor. A study for either has to show that the new unit takes sales from a growing segment rather than splitting them with the entrants that growth has already brought.

Package stores: more stores, the same staff

Liquor stores rose from 881 establishments to 940 while employment stayed flat, 3,570 to 3,550, on $104.7 million of 2023 payroll. The count of stores grew while the people working in them did not, so the average store now employs fewer people and each new license splits the market further. With 247 SBA loans, the second largest class in the state, and floors of 15.5% cancelled and 7.8% charged off, a package store study in Connecticut has to measure the subject's share of a market that is adding competitors faster than jobs, and test the debt against that share rather than against statewide sales.

Shrinking and shifting service counts

Fitness centers fell from 619 establishments to 578 and from 14,222 employees to 11,064; beauty salons from 1,158 to 1,049 and from 7,142 to 5,521; car washes held almost level at 223 and 218 establishments while employees dropped from 1,964 to 1,473. Yet fitness centers drew 164 SBA loans and beauty salons 142 in the decade. A new gym or salon in Connecticut enters an industry with fewer sites than in 2018, and its study has to show where the members or clients come from: a closed competitor, an underserved town, or a format the existing operators lack. For a car wash, staff falling faster than the site count bears on the labor line of the pro forma, which should follow how Connecticut operators now staff. The service and health rows shift in other ways too. Dental offices fell from 1,769 to 1,625 establishments with employment nearly unchanged, 12,946 to 12,507, which points to fewer and larger practices; veterinary clinics added staff, from 4,928 to 6,018, on 369 and 378 clinics; general auto repair lost establishments, 958 to 908, but gained employees, 4,259 to 4,455. In each of these classes the competitive survey should start from the 2023 count, not the 2018 one.

Health, care and craft beverages: the growth rows

The largest gains in the table are in health, care and craft beverages. The outpatient behavioral health row rose from 169 establishments to 285 and from 4,744 employees to 8,169; physician offices stayed nearly level at 2,664 and 2,648 establishments while employment rose from 35,809 to 50,259, on $5.30 billion of 2023 payroll, the largest in the table; assisted living grew from 140 to 170 establishments and from 5,181 to 6,192 employees; child care from 912 to 948 and from 14,517 to 16,532. Breweries went from 54 to 84 establishments, wineries from 24 to 31 and distilleries from 5 to 16. Growth is a demand signal, but it is also new supply, so in behavioral health and assisted living the study must list every operator that opened in the trade area after 2018 before it claims unmet need.

Hotels: fewer properties, fewer workers

Hotel and motel establishments fell from 382 in 2018 to 347 in 2023 and employment from 11,040 to 8,219, on $296.1 million of 2023 payroll, while SBA lenders put $229.2 million into 78 Connecticut hotel loans over the decade. A falling property count can mean a weaker market or a consolidating one in which older motels leave and newer hotels replace them, and the Census table cannot say which. The hotel study has to answer that submarket by submarket, with the supply that closed as well as the supply that opened, and with staffing costs drawn from a market that now employs fewer people per property.

Population, household income and state output

ACS one-year estimates count 3,565,287 Connecticut residents in 2019 and 3,675,069 in 2024, with a median household income that rose from $78,833 to $96,049 over the same span. BEA's regional accounts put gross domestic product at $286.53 billion in 2019 and $382.60 billion in 2025, and personal income at $267.53 billion and $377.36 billion. Household income has risen much faster than population, though part of that rise is inflation, so a study should state its income growth in the same dollars as its price and cost assumptions, and should not assume population growth faster than the modest rise the survey shows. The BEA line is the all-industry total, a different measure from the real economy figure quoted in the market review above, and a study should cite one measure consistently.

Industry establishments, employees and payroll in Connecticut, by asset class
Asset class (NAICS)Establishments 2018Establishments 2023Employees 2018Employees 2023Annual payroll 2023
Full-service restaurant (NAICS 722511)3,4623,48458,67858,365$1.77 billion
Liquor store (NAICS 445310)8819403,5703,550$104.7 million
Limited-service restaurant (NAICS 722513)2,7132,88333,26037,321$859.3 million
Fitness center (NAICS 713940)61957814,22211,064$252.3 million
Beauty salon (NAICS 812112)1,1581,0497,1425,521$181.8 million
Automotive mechanical repair (car and truck) (NAICS 811111)9589084,2594,455$245.0 million
Automotive mechanical repair (car and truck) (NAICS 811112)23169738$1.3 million
Automotive mechanical repair (car and truck) (NAICS 811113)4337165133$7.5 million
Automotive mechanical repair (car and truck) (NAICS 811118)3023205102$4.9 million
Child care center (NAICS 624410)91294814,51716,532$516.0 million
Dental office (NAICS 621210)1,7691,62512,94612,507$783.9 million
Medical office (physicians) (NAICS 621111)2,6642,64835,80950,259$5.30 billion
Gas station and truck stop (NAICS 447110)8909084,9384,859$150.1 million
Gas station and truck stop (NAICS 447190)1761521,2061,040$42.4 million
Hotel and motel (NAICS 721110)38234711,0408,219$296.1 million
Coffee shop and snack bar (NAICS 722515)1,0601,15813,93514,998$309.2 million
Grocery store (NAICS 445110)81476737,88136,416$1.15 billion
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312120)54845941,202$49.6 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312130)2431168272$9.1 million
Beverage manufacturing (breweries, wineries, distilleries) (NAICS 312140)5161569$3.3 million
Car wash (NAICS 811192)2232181,9641,473$44.3 million
Rehabilitation and therapy clinic (NAICS 621340)4485206,2036,188$291.8 million
Veterinary clinic (NAICS 541940)3693784,9286,018$351.4 million
Self storage (NAICS 531130)168164375369$15.9 million
Assisted living (without nursing care) (NAICS 623312)1401705,1816,192$249.6 million
Behavioral health and addiction treatment (NAICS 621420)1692854,7448,169$570.4 million
Behavioral health and addiction treatment (NAICS 623220)1391453,5994,693$241.1 million

Source: U.S. Census Bureau, County Business Patterns 2018 and 2023 (NAICS 2017), through the Census Data API; establishments, March employment and annual payroll; suppressed cells print their flag. Most government and self-employed activity is outside CBP. Download this table (CSV). Cite as: Loan Analytics, "Industry establishments, employees and payroll in Connecticut, by asset class", https://www.analytics.loan/connecticut-feasibility-study-data#economy-industry.

Population and household income in Connecticut
Measure20192024
Population3,565,2873,675,069
Median household income$78,833$96,049

Source: U.S. Census Bureau, American Community Survey 1-year estimates, 2019 and 2024, through the Census Data API (tables B01003 and B19013). Download this table (CSV). Cite as: Loan Analytics, "Population and household income in Connecticut", https://www.analytics.loan/connecticut-feasibility-study-data#economy-people.

Output and income in Connecticut
MeasureEarlier yearLatest year
Gross domestic product, 2019 and 2025$286.53 billion$382.60 billion
Personal income, 2019 and 2025$267.53 billion$377.36 billion

Source: U.S. Bureau of Economic Analysis, regional accounts (SAGDP2 all-industry total, current dollars; SAINC1 personal income), through the BEA API. Download this table (CSV). Cite as: Loan Analytics, "Output and income in Connecticut", https://www.analytics.loan/connecticut-feasibility-study-data#economy-output.

Back to the contents

USDA Business and Industry guarantees in Connecticut

New USDA B&I guaranteed loan awards for projects in Connecticut by fiscal year, and by county, from USAspending; aggregates only.

A thin B&I record

USDA Business and Industry guarantees are rare in Connecticut. The largest face value the table prints is FY2019's, 3 new awards worth $15.0 million net, and its busiest year by count is FY2013, 4 awards for $6.7 million; FY2010 and FY2011 each show 3 awards, for $7.3 million and $337,580. Every other year listed has fewer than 3 awards and a withheld face value, including FY2023, FY2024 and FY2025 with 1 award each. Beside the 1,005 SBA 7(a) loans of FY2025 alone, B&I is a niche route in this state, used for a handful of projects, not a market a study can benchmark against.

Why the study carries the case under B&I

Because the Connecticut record is so thin, a B&I study cannot point to comparable guaranteed loans in the state; it has to stand on the trade area and on the project's own numbers. The market review on this page places B&I activity in the state's rural east and northwest, and our fee survey for 2026 adds that a thin rural market means more fieldwork, since comparable properties there have to be visited, not looked up. The worked example linked on this page, a USDA Business and Industry hotel study in Connecticut, shows how such a study is laid out for the lender who reads it.

Withheld years are not empty years

Most rows in this table print a withheld face value because fewer than 3 awards stand behind them. A withheld cell is not a zero, and a study should read it neither as zero nor as small. The table also carries rows only for years with a record, so years it omits, such as FY2017, FY2018 and FY2020 to FY2022, simply are not shown. A lender weighing B&I against SBA 504 for a Connecticut project gets no state benchmark from this table, which is one more reason the study, not the program's history in the state, has to carry the credit case.

USDA B&I guaranteed loan awards in Connecticut by fiscal year
Fiscal yearNew awardsFace value, net
FY20251withheld: fewer than 3 awards
FY20241withheld: fewer than 3 awards
FY20231withheld: fewer than 3 awards
FY20193$15.0 million
FY20161withheld: fewer than 3 awards
FY20152withheld: fewer than 3 awards
FY20134$6.7 million
FY20113$337,580
FY20103$7.3 million
FY20092withheld: fewer than 3 awards

Source: USAspending.gov records of USDA Business and Industry guaranteed loan awards by project state, face value of the loan net of later changes, as compiled in Loan Analytics' USDA tables; a year's dollars are withheld where fewer than 3 awards were touched that year (new awards and later actions together), so a year can show dollars beside 0, 1 or 2 new awards; FY2026 runs through August 31, 2026; aggregates only, no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Connecticut by fiscal year", https://www.analytics.loan/connecticut-feasibility-study-data#usda-usda-by-year.

USDA B&I guaranteed loan awards in Connecticut by county, FY2015 to FY2026
CountyAwardsFace value
New London, CT (FIPS 09011)6withheld so a smaller cell cannot be found by subtraction
Litchfield, CT (FIPS 09005)2fewer than 5 awards
Southeastern Connecticut, CT (FIPS 09180)1fewer than 5 awards

Source: USAspending.gov award records of USDA Business and Industry guarantees (assistance listing 10.768) by place of performance county, face value net, FY2015 through August 31, 2026, aggregated by Loan Analytics; dollars are withheld where fewer than 5 awards stand behind them; no recipient is named. Download this table (CSV). Cite as: Loan Analytics, "USDA B&I guaranteed loan awards in Connecticut by county, FY2015 to FY2026", https://www.analytics.loan/connecticut-feasibility-study-data#usda-usda-by-county.

Back to the contents

Questions buyers ask

Who writes SBA feasibility studies for Connecticut projects?

Loan Analytics writes them for Connecticut projects, whichever of the federal programs on this page stands behind the loan, and Daniel Smith, MAI signs each study as a party with nothing riding on whether the loan closes. It is normally commissioned once the file has reached underwriting. The readers are the desks in this page's lender table, from Manufacturers and Traders Trust Company with 1,338 Connecticut SBA loans to New England Certified Development Corporation with 387 loans and $322.7 million on the 504 side.

Does a Connecticut SBA lender always require a feasibility study?

No. The Loan Analytics fee survey for 2026 summarizes when the SBA's procedure lets the agency ask for one: when the location is already saturated with the same kind of business; when the concept is unique; when the property is highly specialized, as hotels and car washes are; when a Connecticut project would be outsized for its town; or when fast growth leaves the applicant carrying unseasoned debt. Lenders' own credit policies add start-ups and special-purpose real estate to that list. In Connecticut the saturation test is live in the largest classes, 413 full-service restaurant and 247 liquor store loans, and the special-purpose test in hotels, car washes and self storage.

Does a USDA B&I loan for a Connecticut project need a feasibility study, and at what cost?

Our 2026 survey of study fees reads the USDA rule as making a study compulsory for B&I loans to new businesses once the loan passes $1 million, and its USDA tier, the studies that follow 7 CFR Part 5001 as a Connecticut B&I file must, is listed with a low of $7,500 and a high of $18,750 before larger projects push it further. In Connecticut such loans are rare: the B&I table shows 3 awards for $15.0 million in FY2019 and 1 award in each of FY2023, FY2024 and FY2025, with the face value withheld.

What will a Connecticut hotel feasibility study cost?

In Loan Analytics' fee survey for 2026, a ground-up hotel falls in the upper band, $10,000 to $25,000, and the worked arithmetic there sets a $9,000 fee against a $3.5 million hotel loan. Connecticut hotel loans sit near that size: the state's 78 SBA hotel loans have a $3.1 million median and total $229.2 million, and 37 of them were written under 504, so even the top of the band is a small line beside the debt.

What does a feasibility study for a car wash or self storage facility in Connecticut cost?

Our 2026 fee survey groups car washes and self storage with the standard special-purpose assets, whose single-site studies run $5,000 to $12,500 in published fees; a Connecticut project spread over several sites or built in phases moves into the complex range of $10,000 to $25,000. Connecticut's 43 car wash loans have a $775,000 median and its 32 self storage loans an $864,150 median, with 13 and 14 of them written under 504.

How long will a Connecticut feasibility study take to complete?

That turns on scope, so we state the timeline in the scope we send back for your project rather than quote a standard one. Our 2026 fee survey lists the factors that stretch the work: each additional site, new construction, because the study must then review the budget and project the ramp from the day the doors open, a franchise whose system results need checking, a USDA overlay, and thin rural markets where comparables must be seen in person. A ground-up Connecticut hotel or a B&I project in the state's rural east carries several of those at once; the purchase of an operating liquor store or restaurant with its own statements carries fewer.

Do SBA loans in Connecticut default more often than elsewhere in New England?

On the floors this page can print, yes for the tracked classes: at least 5.2% of Connecticut's disbursed loans have been charged off, against 5.0% in Rhode Island, 4.0% in Vermont, 3.9% in Massachusetts, 2.2% in Maine and 1.9% in New Hampshire. Each is a minimum, because the SBA files withhold the status of loans still open. Inside Connecticut the highest class floors belong to limited-service restaurants (9.3%), liquor stores (7.8%) and beauty salons (7.7%), and a study for one of those classes should explain why the subject differs from that record.

What does a lender expect a Connecticut gas station study to cover?

Connecticut's 79 loans to gas stations and truck stops have a $400,000 median and a 23.5% cancellation floor, the highest of any class measured in the state, so the study should settle the site, its environmental condition and the cost before approval. Loan Analytics' 2026 fee survey records that fuel stations, as an environmentally sensitive use, need a Phase I site assessment whatever the loan amount, a report it prices from $3,500 to $6,000 for such sites. Census counts show 890 stations with convenience stores in 2018 and 908 in 2023, so the competitive survey starts from a rising count.

Is there demand for a new child care center or assisted living facility in Connecticut?

The Census counts point that way: child care establishments rose from 912 in 2018 to 948 in 2023 and their employees from 14,517 to 16,532, and assisted living grew from 140 to 170 establishments and from 5,181 to 6,192 employees. SBA lenders financed 123 Connecticut child care centers at a $422,000 median, with floors of 10.4% cancelled and 4.5% charged off, and 30 assisted living facilities at a $559,500 median. Statewide growth is not trade-area demand, though: the study has to find the centers or residences that opened nearby and test the subject's enrollment or occupancy against them.

What does a Connecticut lender want to see in a restaurant feasibility study?

Restaurants are the largest part of Connecticut's SBA record, 413 full-service loans at a $150,000 median and 205 limited-service loans at $155,400, and the limited-service floors, 17.5% cancelled and 9.3% charged off, are among the state's highest. The study should name and size the trade area's existing restaurants, build the subject's sales from covers and check average rather than a national figure, and carry a downside case. Census counts show limited-service establishments growing from 2,713 to 2,883 while full-service held at 3,484, so the competition a quick-service study measures is still being added.

Does Loan Analytics prepare studies for both SBA 7(a) and SBA 504 loans in Connecticut?

Yes, and for USDA Business and Industry loans. The two SBA programs bring different files: 7(a) carried 7,311 Connecticut loans for $2.62 billion from FY2017 to FY2026, and 504 carried 816 for $637.1 million. In the tracked classes the most 504 loans went to hotels (37), full-service restaurants (34) and child care centers (22). A 504 project is financed by a certified development company together with a bank, so the study covers the real estate and the operating case in one document both can rely on.

Back to the contents

Connecticut feasibility study consultant: request a scope

If your project is one of the next Connecticut loans in this record, a package store in New Haven County, a quick-service unit on a growing corridor, a hotel whose loan will sit near the state's $3.1 million median, or a B&I project in the rural east, send the scope request before the lender's underwriting starts. Tell us the class, the town, the program and whether the project is an acquisition, an expansion or ground-up construction, and Loan Analytics will reply with the scope, the timeline and the published fee band that applies.

The study we return is built from the tables on this page and carried down to your site: the class's Connecticut floors, the Census count of your competitors, the lenders likely to read it, and a downside case drawn from years like FY2009 and FY2020, when Connecticut's SBA lending fell. Use the Request Scope & Timeline form below to start.

Request Scope & Timeline

Corrections

Figures on this page were checked against SBA's and USAspending's own records and corrected where they differed. Each corrected figure is marked in the text; what it counts and where it comes from:

  1. 84: lenders with at least one 7(a) approval, Connecticut, 2025; FY2025, distinct lender keys, project state. Source: SBA loan data as of 2026-09-30.
  2. 84,840: 7(a) plus 504 gross approvals FY2025, cancellations included. Source: SBA loan data as of 2026-09-30.
  3. $45.09 billion: gross SBA 7(a) loan dollars plus 504 debenture dollars approved in FY2025, cancelled approvals included; the highest of any fiscal year in the SBA loan data, which begin in FY1991. Source: SBA loan data as of 2026-09-30.

Start with the data.

Contact Us